$544.8M. That's how much buyback capacity Griffon now has after the board added $400M on November 17, and what I'm watching is how fast…
$544.8M. That's how much buyback capacity Griffon now has after the board added $400M on November 17, and what I'm watching is how fast they actually spend it while volume is still shrinking.
- Fiscal 2026 revenue came in at $1.85B, up 3% from $1.80B. All of that growth came from 6% favorable price/mix in residential and commercial, partly offset by a 3% volume decline the company tied mainly to residential markets.
- Full-year adjusted EBITDA was $459.6M versus $461.8M the year before, so the top line moved and earnings power basically sat still.
- Q4 did clear the bar: revenue of $490.9M versus an average forecast of $481.1M, per AP, with adjusted EPS of $1.61.
- $GFF closed November 16 at $99.96, down 4.94%, and was indicated at $99.25 pre-market on November 17, about 0.71% lower.
An authorization is capacity, and the next two quarters of actual repurchases will show how much conviction is behind it. I'd pair that with whether residential volume stops falling, because price/mix can't carry growth forever. Could be wrong, but that's the read I'll be checking.
Sources:
https://www.businesswire.com/news/home/20261116340663/en/Griffon-Corporation-Announces-Annual-and-Fourth-Quarter-Results/
https://www.businesswire.com/news/home/20261116709044/en/Griffon-Announces-Additional-400-Million-Share-Buyback-Authorization/
Not financial advice. For informational and educational purposes only.
$CRM daily pick: sell Jan 15 $165 put (buy-side) after a 10% software selloff
$CRM: I'm selling the Jan 15 $165 put on @salesforce. At $193.96 (midday Tuesday, down almost 10% today): 27% off the December high and 2% under the 200-day $5.00 credit, breakeven $160 About 3% in 59 days (~19% annualized) I think a lot of today's drop is funds selling software to make room for the Anthropic IPO, which prices tomorrow.…
$TSLA deep dive: 429x earnings, flat revenue, Cybercab orders and SpaceX merger talk. I think it's a hold at $381
$TSLA is one of the most discussed stocks on X this week and I think it is a hold at $381. The business: Q3 revenue was $28.0B which was flat from a year ago. Deliveries fell 2.1% to 486,532. Gross margin improved to 19.6% but R&D rose 69% and operating margin fell to 2.6% from 5.8%. Free cash flow was…
Afternoon update
Elbit Systems rose 5.97% on record Q3 results while the S&P 500 fell 1.22% and the Nasdaq fell 1.13%.
Elbit Systems rose 5.97% on record Q3 results while the S&P 500 fell 1.22% and the Nasdaq fell 1.13%. Markets were waiting on Nvidia's earnings after the close. $ESLT ($33.9B market cap): Q3 revenue rose 17% year over year, and operating profit and EPS each…
Midday update
Salesforce ($CRM) fell 9.48% at midday, the largest drag on a Dow down nearly 900 points intraday, as investors cut tech exposure ahead of Nvidia's…
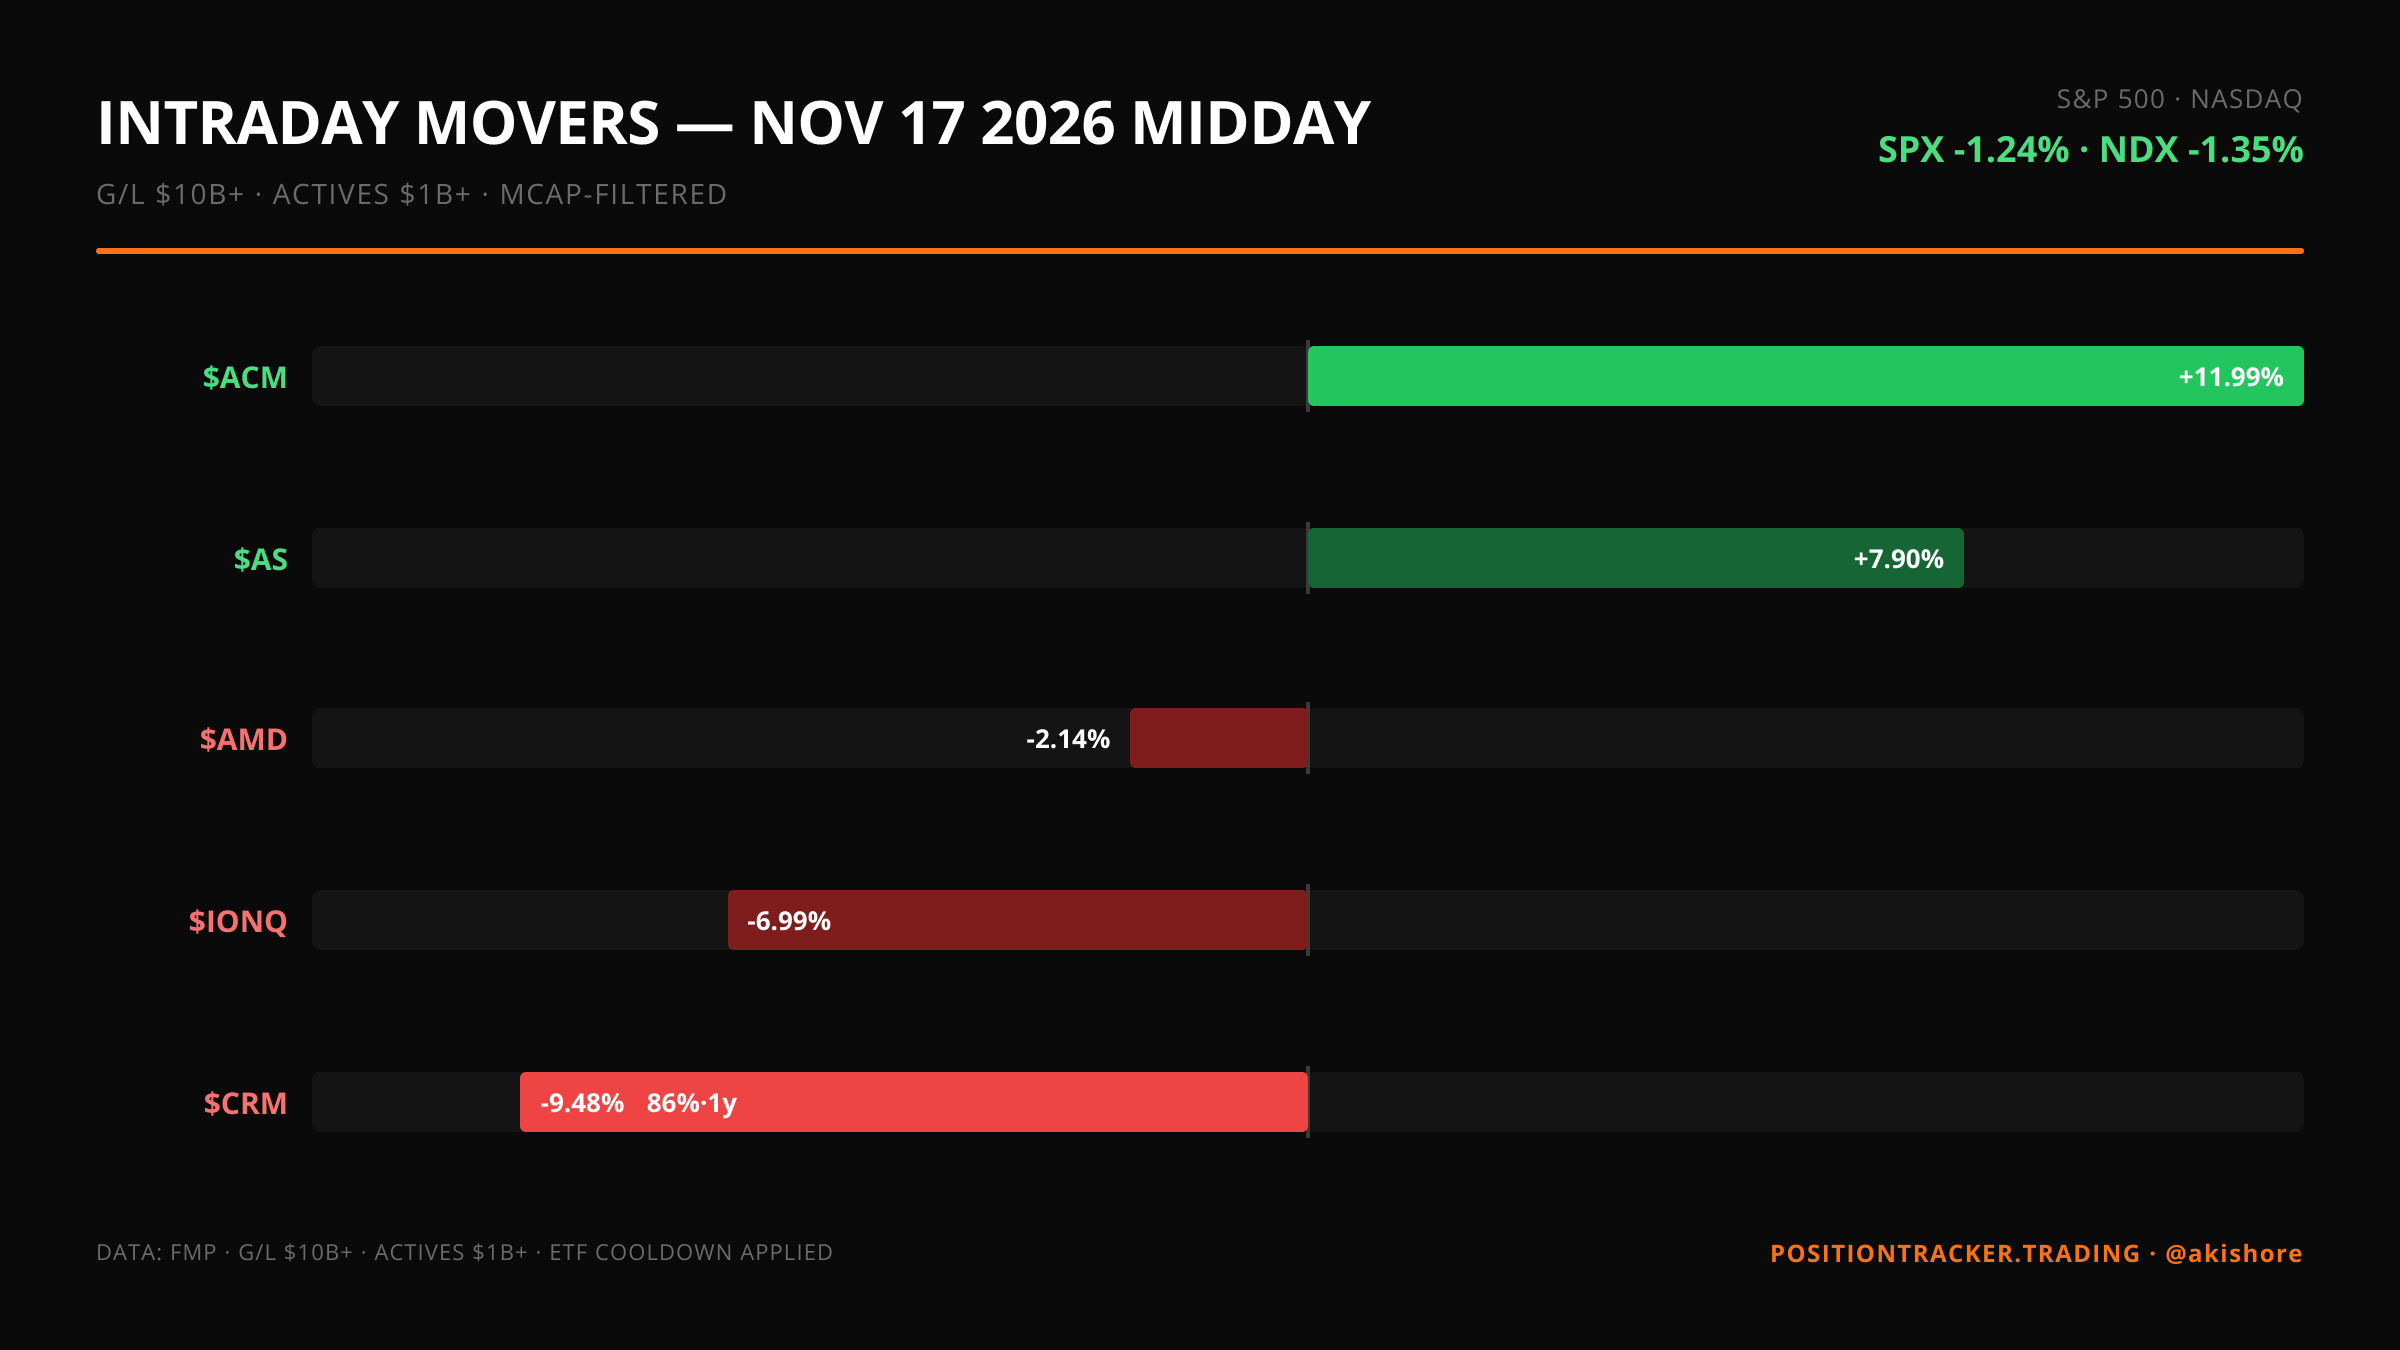
Salesforce ($CRM) fell 9.48% at midday, the largest drag on a Dow down nearly 900 points intraday, as investors cut tech exposure ahead of Nvidia's earnings and Anthropic's IPO. The S&P 500 was down 1.24% and the Nasdaq down 1.35%.