AMD's Q3 is the kind of print that puts pressure on my skeptical lean on semis.
AMD's Q3 is the kind of print that puts pressure on my skeptical lean on semis. Data Center did $8.546 billion, up 97% year over year, and management is guiding for Q4 growth to accelerate from there.
- Total Q3 revenue was $13.377 billion, up 45%, with non-GAAP EPS of $2.09 beating estimates. GAAP EPS was $1.46, and that gap is the number I'd check against cash flow before getting excited.
- AMD guided Q4 revenue to about $17 billion, plus or minus 3%. At the midpoint that's roughly 27% sequential and 66% year over year. That's company guidance, not booked revenue.
- The stock closed the regular session Nov. 3 at $483.90, up 3.65% during a broader chip bounce before the release. After hours it was $518.62, up 7.17% from the close.
- My view flips if chip demand holds for years and revenue and cash flow rise across most AI names. One company accelerating is a strong data point, but it's still one company.
If AMD actually lands near $17 billion while competing with Nvidia into year-end, I'd have to admit the demand cycle is longer than I've been assuming. Until the rest of the group shows the same, I'm treating this as AMD-specific strength. What would you need to see?
Sources:
https://ir.amd.com/news-events/press-releases/detail/1303/amd-reports-third-quarter-2026-financial-results
https://www.benzinga.com/markets/earnings/26/11/62845344/amd-posts-q3-double-beat-as-data-center-segment-shines-growth-expected-to-accelerate-in-q4
https://www.cnbc.com/2026/11/03/amd-amd-q3-earnings-report-2026-.html
Source:
YouTube earnings alert: https://www.youtube.com/watch?v=LawtU0JP1xw
Not financial advice. For informational and educational purposes only.
Arista Q3: Q4 guide beats consensus by ~10% but implies ~8% sequential growth vs 20.5% in Q3
Arista Networks (ANET) reported Q3 after the close Tuesday: revenue up 58.5% to $3.66B (its fastest growth since the 2014 IPO) and a…
AMD Q3: data center added $4.21B YoY while total revenue grew $4.13B, so everything else shrank
AMD (AMD) reported Q3 after the close Tuesday: revenue up 45% to $13.38B, data center up 97% to $8.55B and a Q4 guide of…
Priceline customers and BKNG shareholders are the ones paying for this FTC fight, and Booking just put a number on it: a $900 million…
Priceline customers and BKNG shareholders are the ones paying for this FTC fight, and Booking just put a number on it: a $900 million revenue reduction in Q3, plus a separate $100 million accrued loss. Per Reuters, the matter ties to the FTC's inquiry…
Volcker Shock & the 1980s Bull — 20% Rates to 3.75%-4.00%
In June 1981, the Federal Reserve pushed the Fed Funds rate to 20% to break inflation running at 14.8%, the most aggressive tightening cycle in Fed…
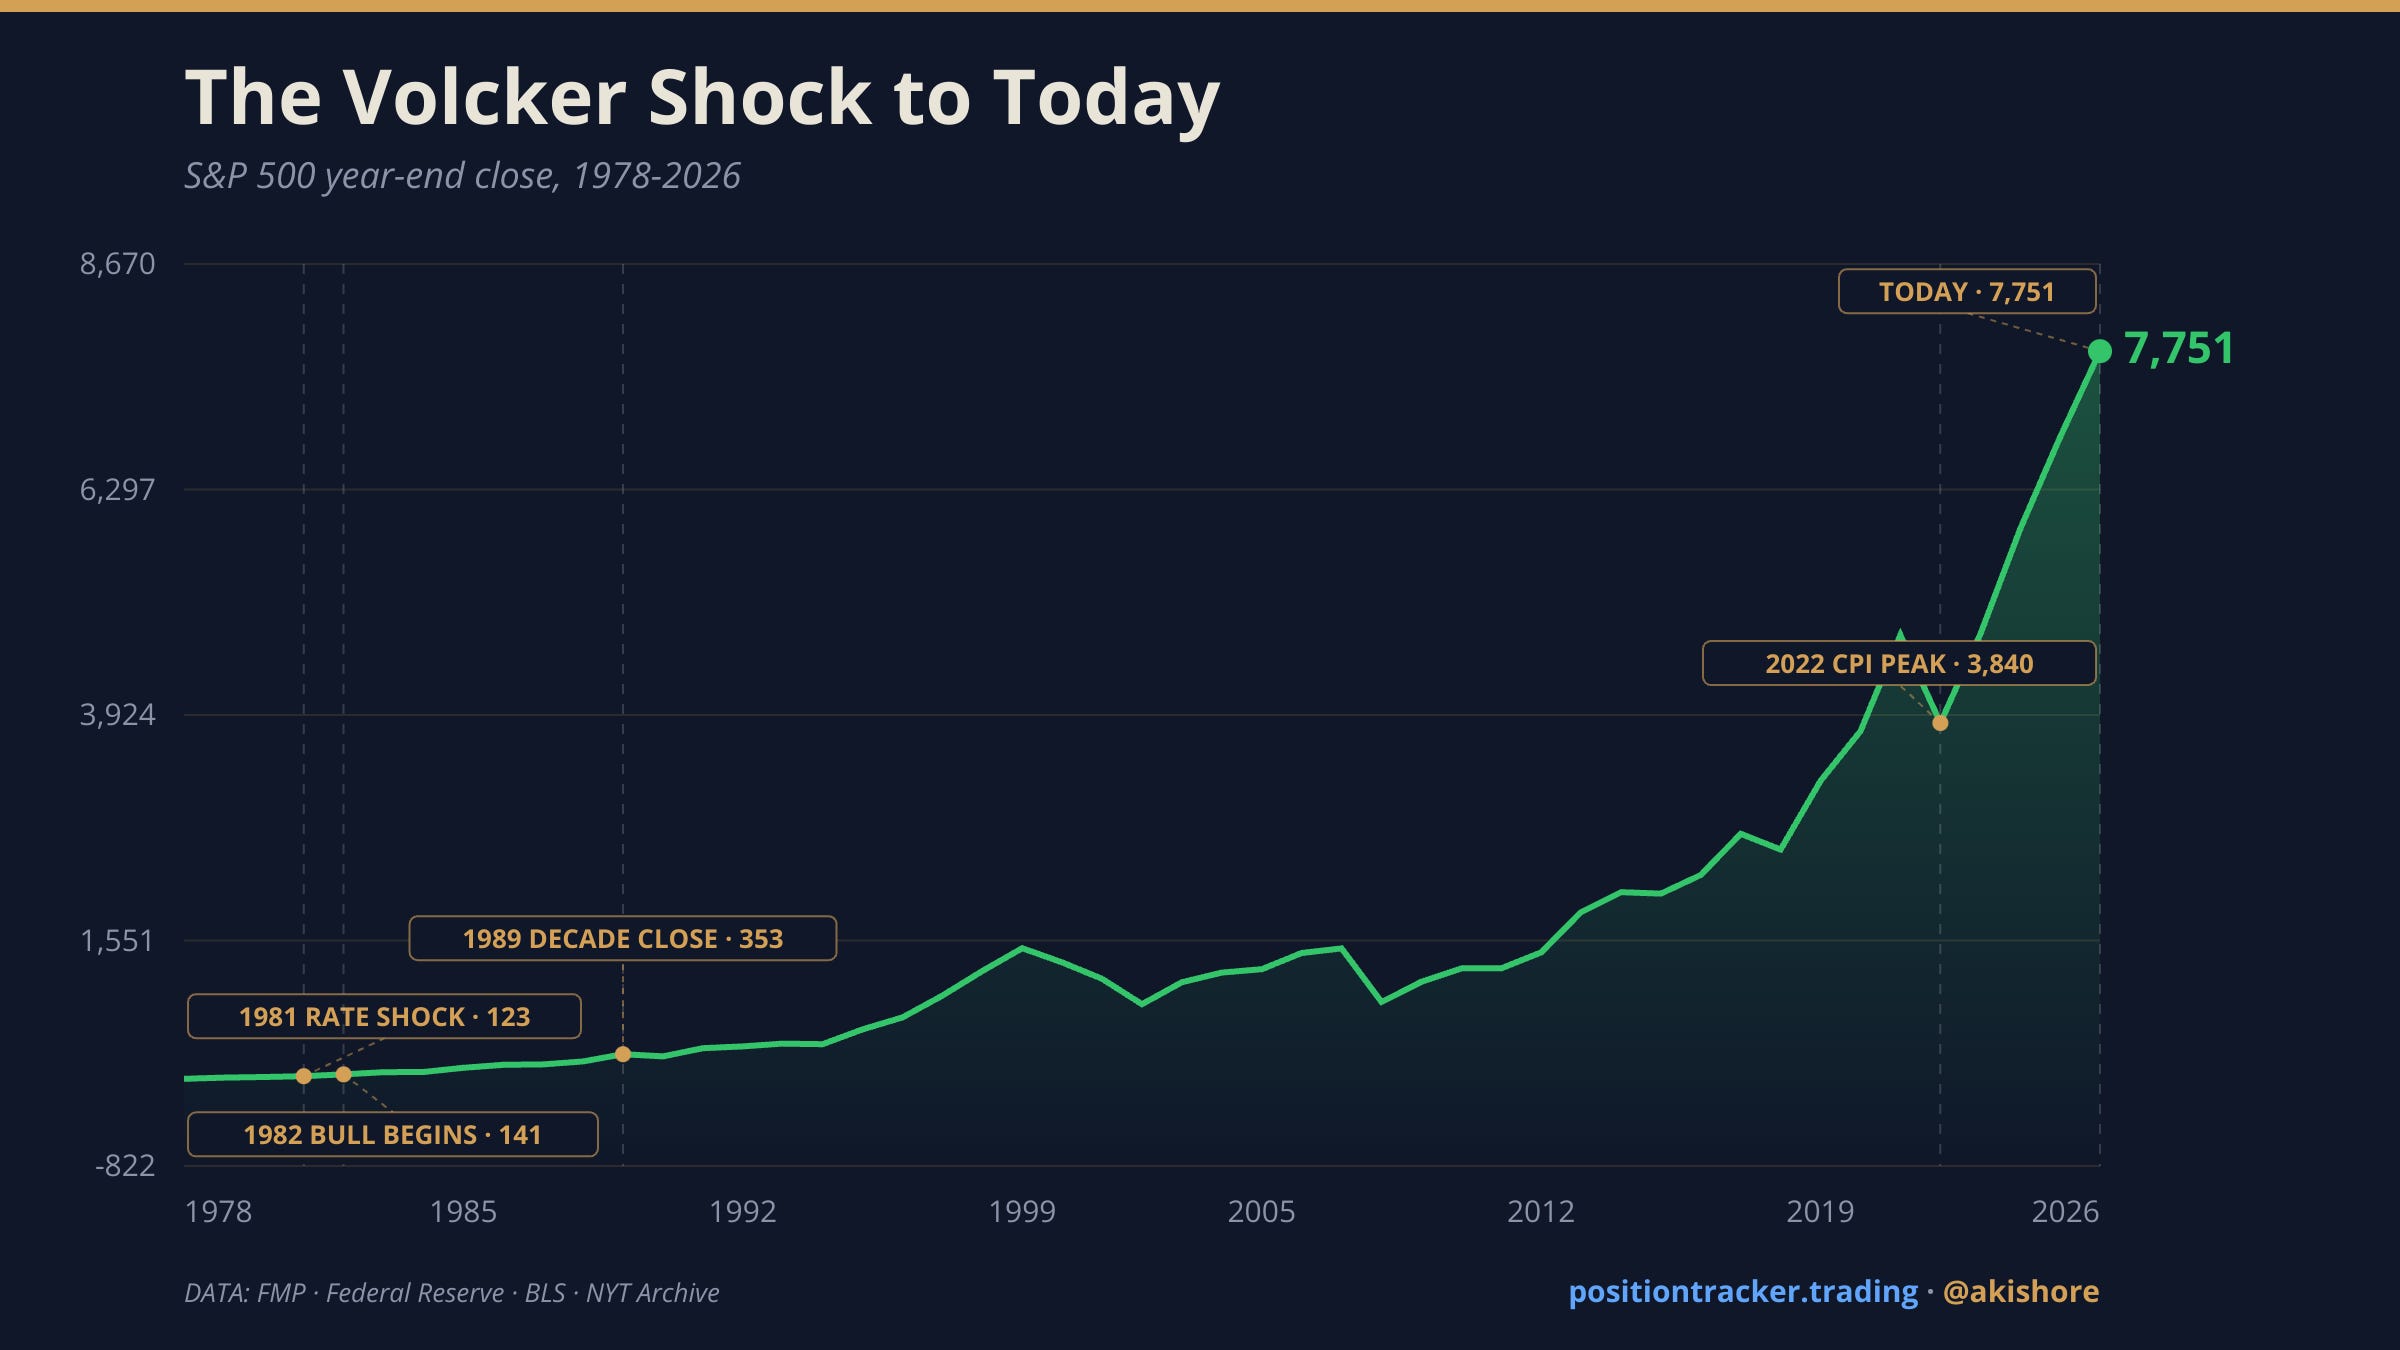
In June 1981, the Federal Reserve pushed the Fed Funds rate to 20% to break inflation running at 14.8%, the most aggressive tightening cycle in Fed history. The market absorbed the full cost of it. The S&P 500 bottomed at 102.42 on August…