$APP deep dive: worst S&P name of 2026 crushed earnings. I think it's a buy on dips to $280-$300
$APP was the worst big stock of 2026 then crushed earnings and jumped about 25%. I think it's a buy on pullbacks into the $280 to $300 zone because the Axon transition just proved itself and at ~19x earnings you still pay less than Meta for much faster growth.
Q3: revenue $2.18B (+55%) vs ~$2.08B expected. Diluted EPS $4.30 vs ~$4.04. Net margin 66%. Adjusted EBITDA $1.84B at an 84% margin. Free cash flow $1.4B and @AppLovin returned $1.4B via buybacks in the quarter. Board raised the buyback authorization by $3.2B to $3.6B.
Q4 guide: revenue $2.365B to $2.395B (Street ~$2.25B) and adjusted EBITDA $1.995B to $2.025B. Management says a next-gen Axon model is only partially rolled out and already lifting gaming. Consumer advertiser spend is up triple digits year over year.
Chart: from the $738 Dec high to the $225 Oct 30 low (~60% YTD into the print). Live near $340 above the 20 and 50 day but still under the 200 day near $411. My Elliott read is wave 1 of a new impulse off $225. A wave 2 pullback into $270 to $300 would be healthy. First real resistance is the 200 day. A close back under $225 breaks the count.
My plan: buy the $280 to $300 zone. A close under $225 makes it a sell. Reclaiming $411 turns the bounce into a trend.
Not financial advice.
Worst stock of the year just printed 55% growth and an 84% EBITDA margin. That is the setup.
Two frames from the deep dive: the post-earnings gap after a ~60% YTD wipeout and my Elliott Wave levels (W2 zone $270 to $300, invalidation $225, 200-day near $411).
Sources: 1. AppLovin Q3 2026 press release BusinessWire, 2026 11 04 — · 2. SEC Form 10 Q HTML period ended 2026 09 30 — · 11. MarketWatch — profit $1.44B / $4.30 vs FactSet $4.03 on $2.07B; Q4 guide $2.365–$2.395B vs $2.25B Street; Adj. EBITD · 12. Investing.com — EPS $4.30 vs $4.04; rev $2.18B vs $2.08B; Q4 rev guide $2.37–$2.40B vs $2.25B. · 13. StockAnalysis earnings article 2026 11 05 — confirms table vs Q3'25; ~60% YTD decline / worst S&P 500; call color on · 14. StockAnalysis transcript — CFO: growth primarily core mobile gaming from model improvements; consumer spend +QoQ dou
Not financial advice. For informational and educational purposes only.
$DDOG daily pick: buy a starter after the 15% drop on a flat Q4 guide, add $166 to $189
$DDOG: I'm buying a starter in @datadoghq after a 15% drop on a flat fourth quarter guide. Live at 12:14pm ET ($188.40): 5.5% under the 200-day 37% off the Oct 12 high Q3 revenue $1.20B, up 35% from a year ago Q4 guide $1.19B to $1.20B, about flat with Q3
EXL Service acquires AI consulting firm Aimpoint Digital
EXL Service announced the acquisition of Aimpoint Digital, a data and AI consulting firm specializing…
Volcker Shock & the 1980s Bull — 20% Rates to 3.75%-4.00%
In June 1981, the Federal Reserve pushed the Fed Funds rate to 20% to break inflation running at 14.8%, the most aggressive tightening cycle in Fed…
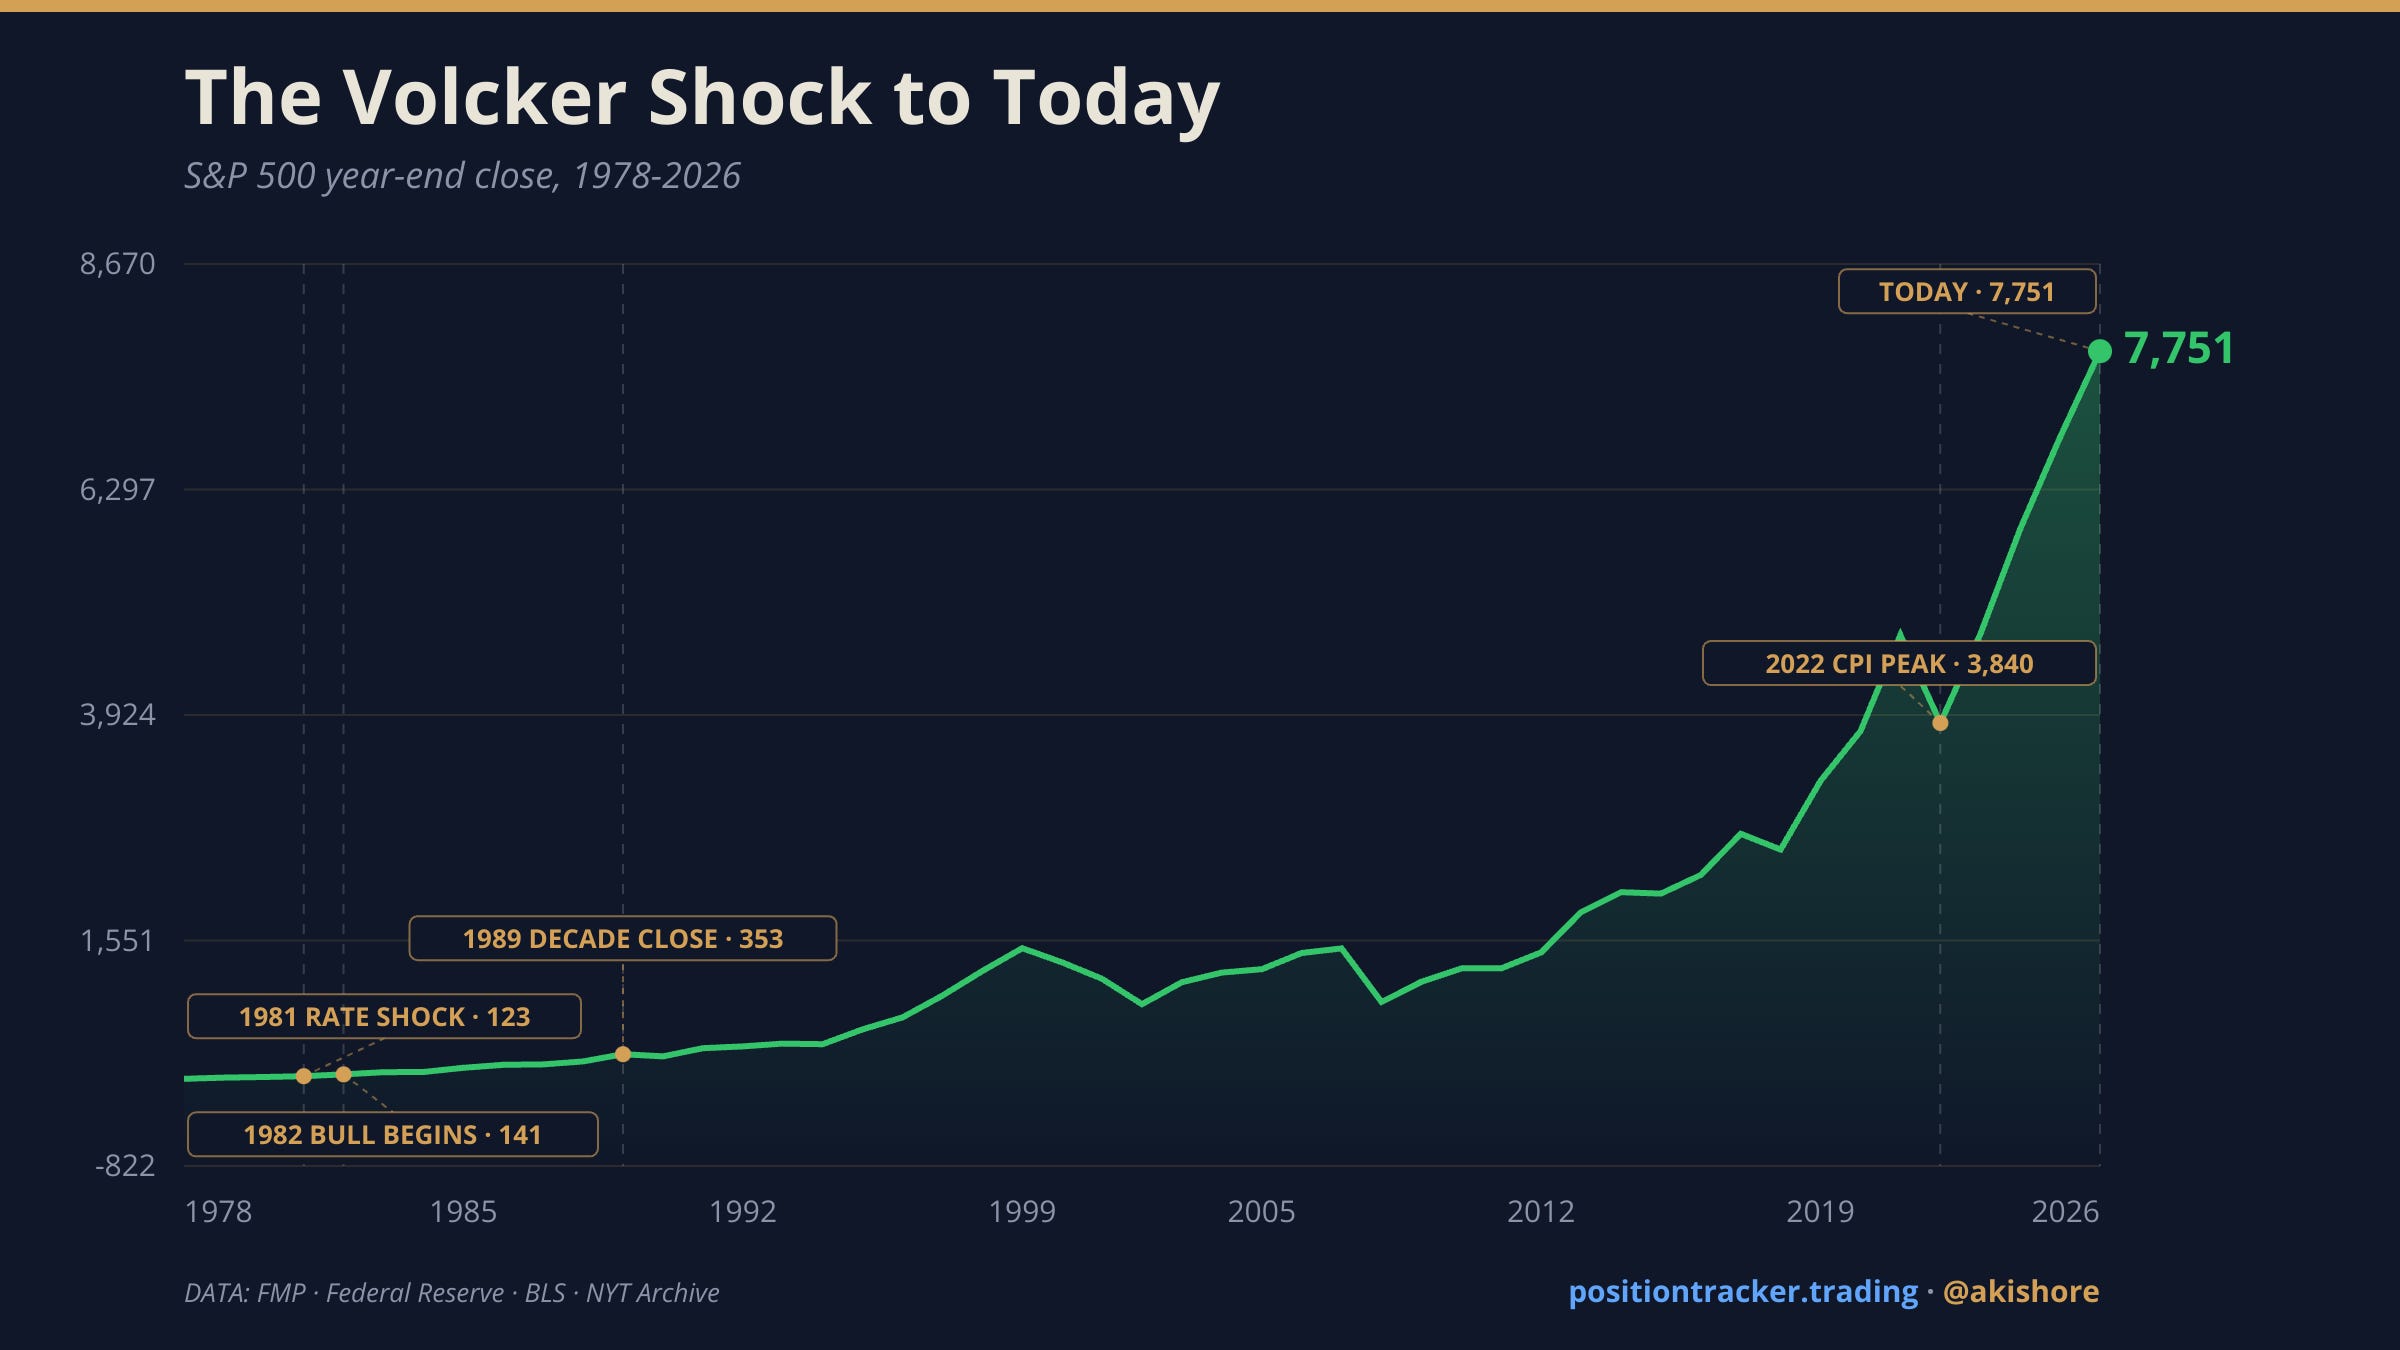
In June 1981, the Federal Reserve pushed the Fed Funds rate to 20% to break inflation running at 14.8%, the most aggressive tightening cycle in Fed history. The market absorbed the full cost of it. The S&P 500 bottomed at 102.42 on August…
Afternoon update
$LITE fell 16.57% and Marvell 10.68% this afternoon as investor skepticism grew over Marvell's $115B all-stock acquisition of Lumentum. • Lumentum…
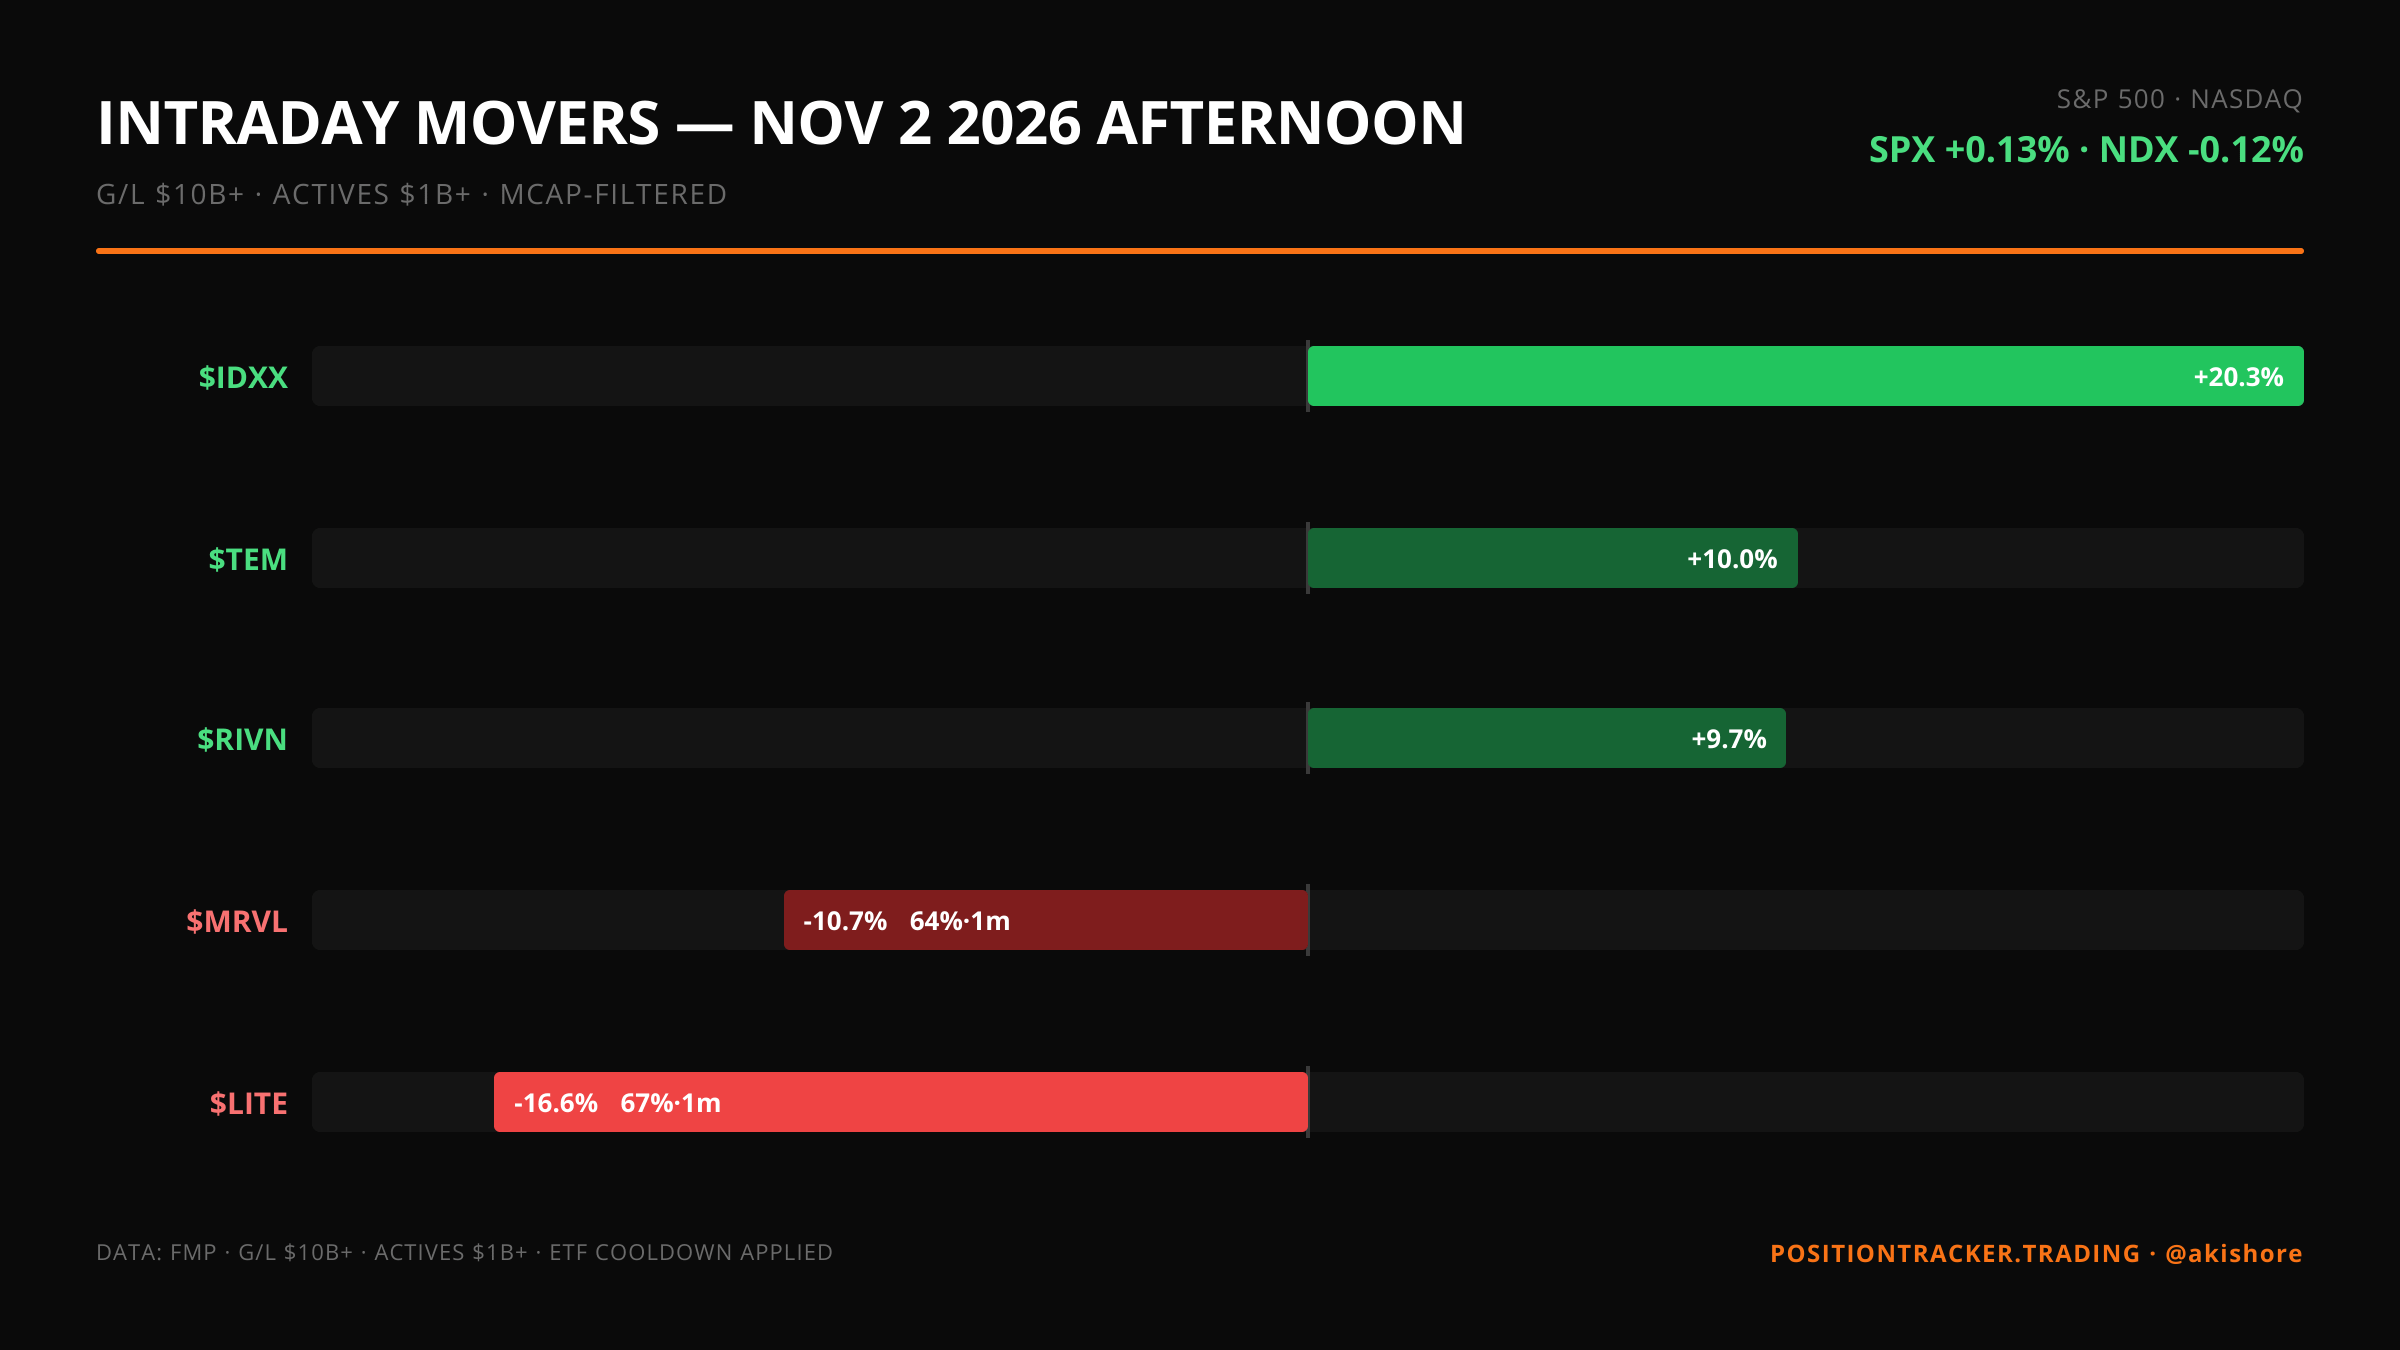
$LITE fell 16.57% and Marvell 10.68% this afternoon as investor skepticism grew over Marvell's $115B all-stock acquisition of Lumentum. Lumentum closed at $701.43 ($62.9B market cap). The deal, valued at $115B by enterprise value, gives Marvell shareholders 67% of the combined…