$BJ is down 6.03% in pre-market trading at $104.07 on November 20, 2026, from a $110.75 November 19 close, despite a 44.4% jump in Q3…
$BJ is down 6.03% in pre-market trading at $104.07 on November 20, 2026, from a $110.75 November 19 close, despite a 44.4% jump in Q3 net income. When a beat gets sold off like that, I look past the headline to what clean earnings look like next quarter.
- Q3 FY2026 revenue grew 17.5% year over year to $6.28 billion, with diluted EPS at $1.73 and adjusted EBITDA up 39.9% to $421.6 million.
- That profit jump included roughly $240 million net of legal fees from an interchange-fee settlement, partly offset by about $95 million in related expenses, and management left the benefit inside adjusted EPS and adjusted EBITDA.
- Underneath the headline numbers, merchandise gross-margin rate fell about 170 basis points, primarily from birthday-event promotions.
- Management raised FY2026 guidance to 2.5% to 3.0% ex-gas comparable-sales growth and $5.10 to $5.30 in adjusted EPS, a range that still carries the Q3 settlement boost.
I always scrutinize adjusted numbers when a one-time settlement stays in the math. What I am watching next is whether BJ's merchandise margins rebound after the promotions end and whether holiday-quarter ex-gas comps hold up on core operating results.
Sources:
TradingView: https://www.tradingview.com/news/tradingview:30d4940907a00:0-bj-s-wholesale-club-reports-q3-fy2026-results-raises-full-year-outlook/
Investing.com: https://www.investing.com/news/earnings/bjs-wholesale-club-beats-estimates-raises-guidance-5041448
Not financial advice. For informational and educational purposes only.
Anthropic slipped another 1.13% after-hours to $88.30.
Anthropic slipped another 1.13% after-hours to $88.30. In Friday's regular session, shares touched $83.05, nearly their $83 IPO price and 14.53% below the previous close. They recovered to close at $89.305, down 8.09%…
Citi shares touched $110.175 in the regular session, 4.43% below the previous close, and finished at $110.72, down 3.96%.
Citi shares touched $110.175 in the regular session, 4.43% below the previous close, and finished at $110.72, down 3.96%. They traded at $110.99 after hours, up 0.24% from that close. Reuters reported that incorrectly recorded trades at Citi's UK trading subsidiary led to an understatement of about…
The one number that actually matters in HSBC's Nov.
The one number that actually matters in HSBC's Nov. 20 upgrade of $TSLA is $212. Everything above that in the bank's $359 price target rests on a hypothetical SpaceX deal that has no formal terms on the table. HSBC analyst…
Afternoon update
Global Payments rose 10.51% on reported GTCR takeover interest as semiconductor weakness weighed on the broader market.
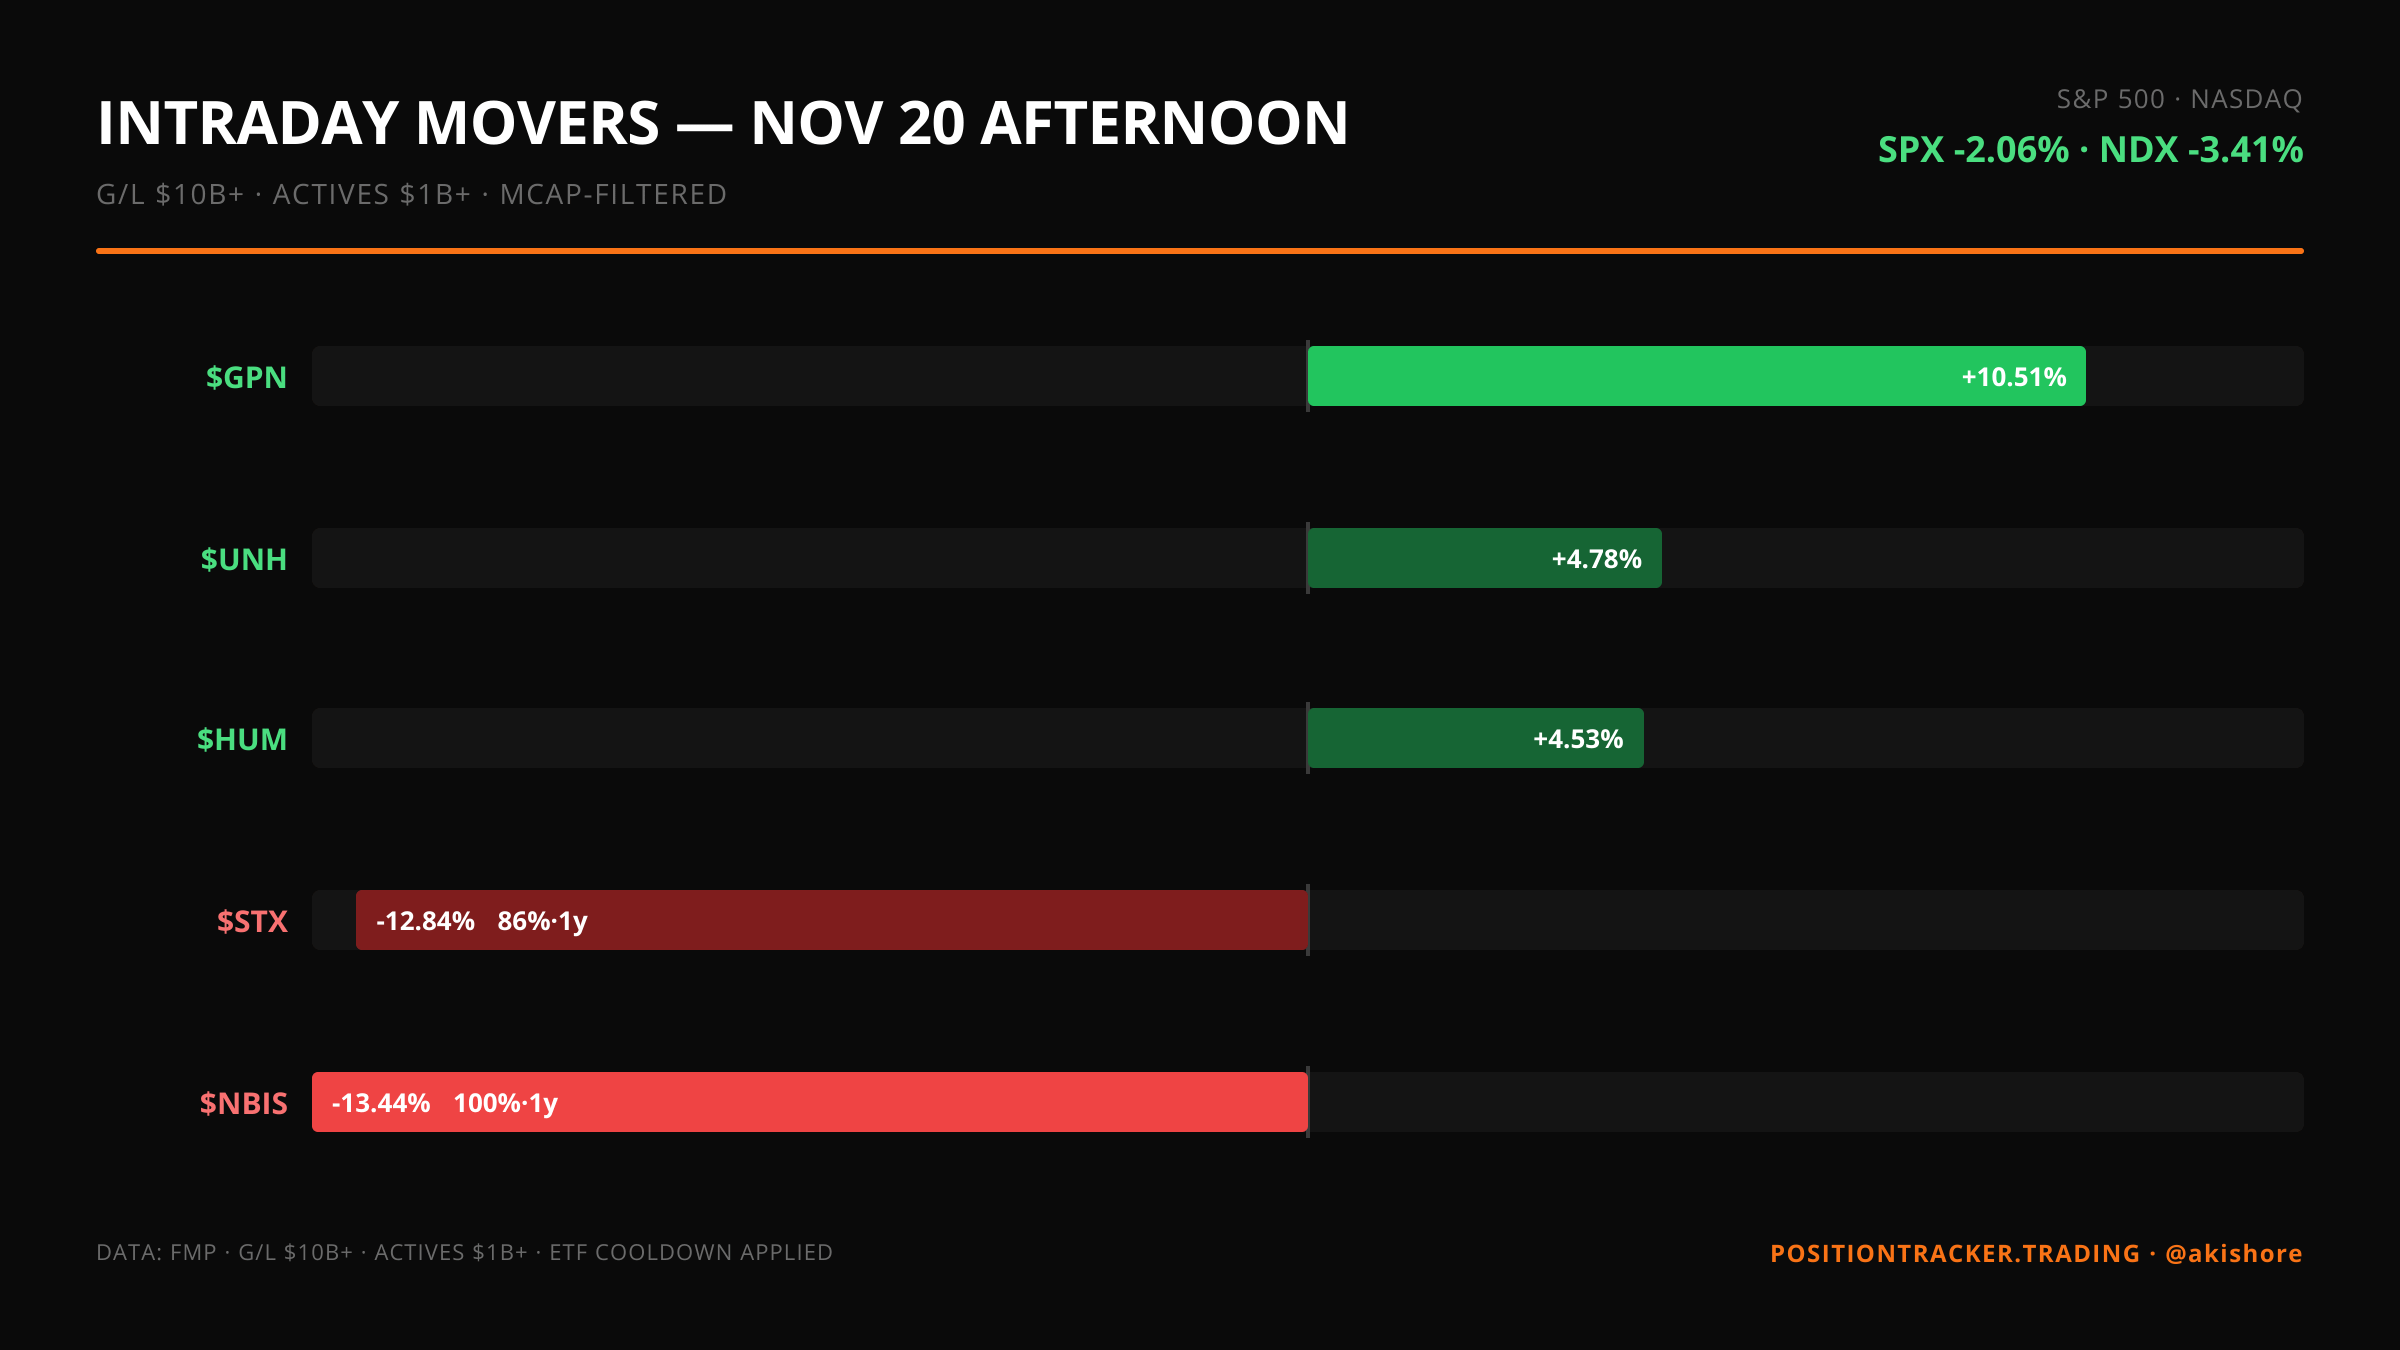
$GPN rose 10.51% on November 20 after a report that GTCR is considering a $50B takeover bid. The Nasdaq fell 3.41% in the afternoon session. Global Payments gained 10.51% at a $24.4B market cap. Shares jumped on the reported GTCR interest; the bid remains a report, not a confirmed…