End-of-day recap
Chip stocks gave back part of this week's rotation trade on Nov 13 as Nvidia stabilized, while two earnings beats and a 5.15% 10-year yield set the…
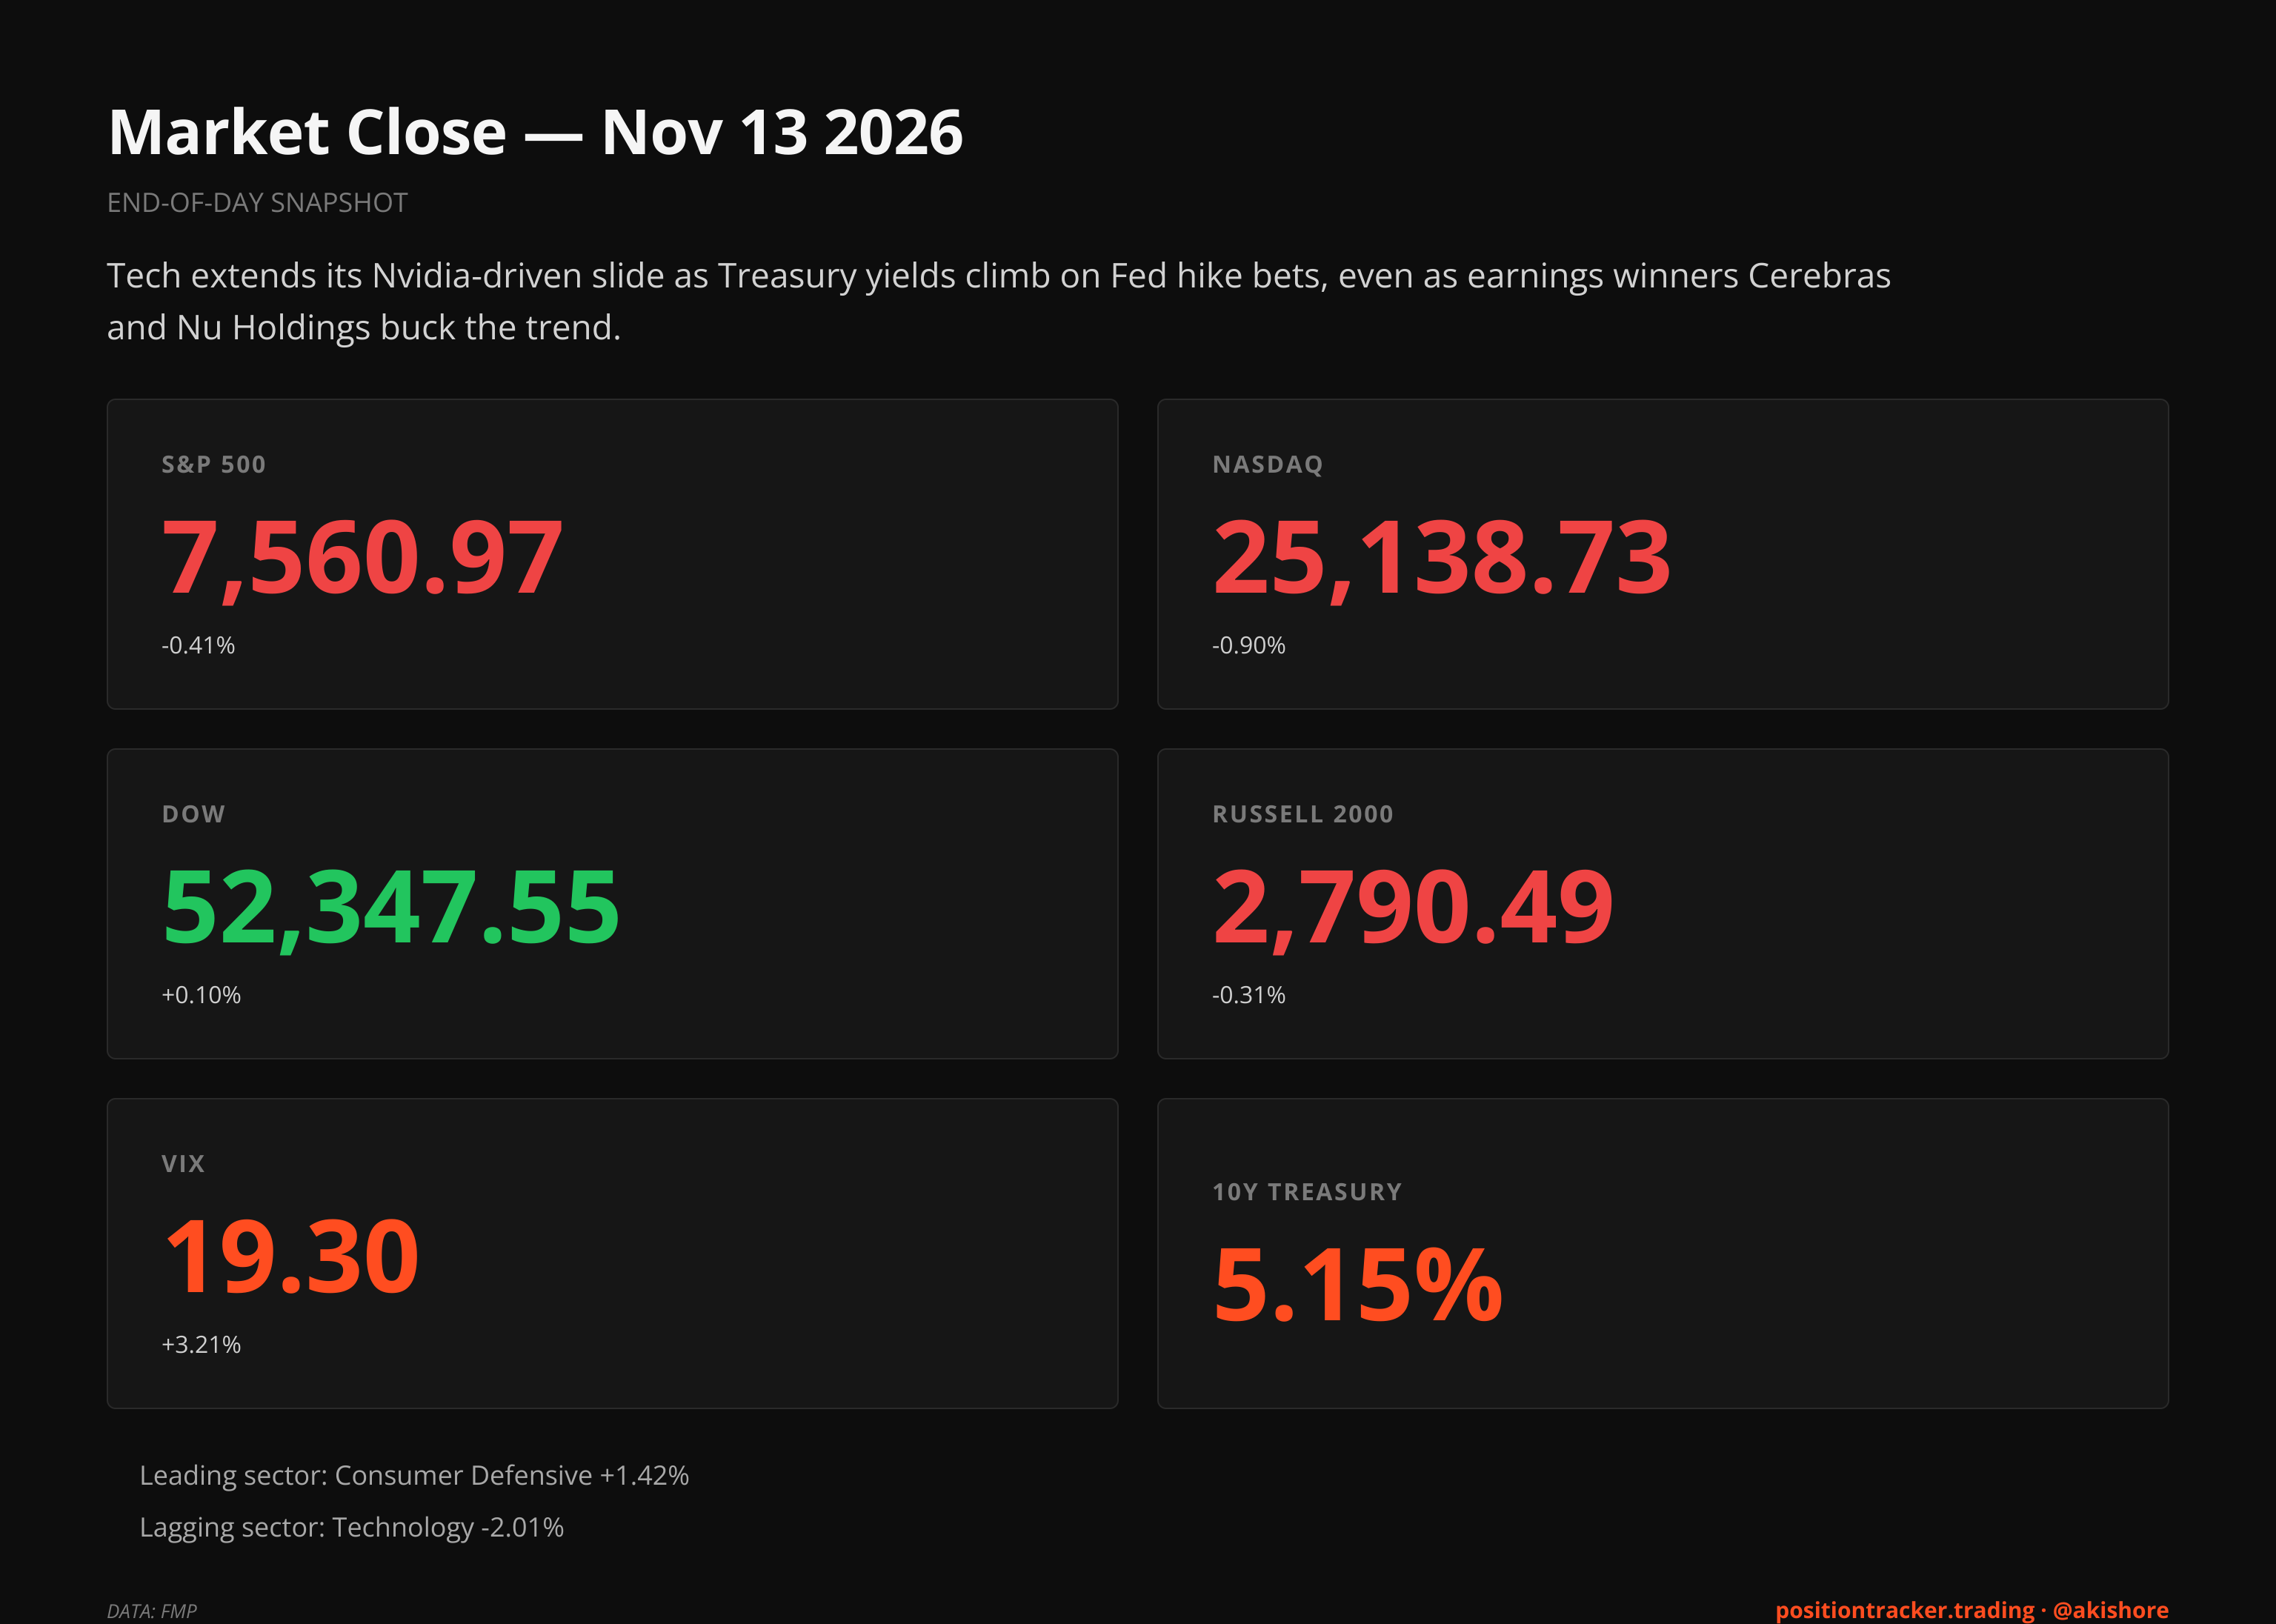
Chip stocks gave back part of this week's rotation trade on Nov 13 as Nvidia stabilized, while two earnings beats and a 5.15% 10-year yield set the rest of the tape.
Cerebras (CBRS) rose 11.22% to 108.72. Q3 core revenue grew 70%, the company raised its Q4 guidance above consensus, and it announced new hyperscaler cloud deals including Microsoft.
Nu Holdings (NU) gained 11.75% to 13.22 on record Q3 net income, up 31% currency-neutral. Revenue rose 37%, and customers reached 143 million after 3.7 million additions in the quarter.
AMD fell 8.75% to 534.06 as the AI-chip rotation trade unwound. The move erased part of a roughly 30% weekly gain built on Jensen Huang's resignation, with profit-taking amid scrutiny of a valuation near 125 times trailing earnings.
Broadcom (AVGO) dropped 4.76% to 347.01 after Rothschild and Co Redburn downgraded it to neutral from buy and cut its price target, cooling a 24% weekly rally built on Nvidia-rotation bets.
Nvidia (NVDA) slipped 2.01% to 162.85 and is on pace for its worst week since January 2025. DA Davidson's Gil Luria set a new price target amid Jensen Huang's CEO departure.
Nvidia options volume hit 6.86 million contracts, 198.70% of average, with 3.92 million calls and 2.94 million puts. The Nov 13 162.50 call traded at 37.76x open interest and the Nov 13 160 put at 15.95x, showing two-way positioning ahead of next week's earnings.
Nebius (NBIS) fell 9.92% to 115.88 despite a Q3 revenue beat. Colocation delays, including a site tied to Microsoft, pushed its 2026 revenue guide to the low end of the range and raised its 2027 capex outlook. Baird, Compass Point and Truist trimmed targets and kept Buy ratings.
HTFL lost 19.13% to 48.46 after a Q3 revenue beat, a narrower EPS loss and a raised FY26 revenue guide. Wells Fargo, Stifel, Canaccord and Baird raised targets as the stock gave back part of a 106% year-to-date rally.
The 10-year Treasury yield sat at 5.15%, the 2-year at 4.88% and the 30-year at 5.47%, while the VIX rose 3.21% to 19.30. Hawkish Fed rhetoric, stubborn inflation and growing debt supply kept December hike bets fully priced.
Technology fell 2.01% as the day's laggard on chip selling tied to Nvidia's leadership turmoil. Consumer Defensive led, up 1.42%, as investors rotated into staples as a hedge.
Upstart (UPST) CEO Paul Gu bought 50,000 shares on Nov 11, disclosed in a Form 4 filed today.
StoneX lowered its price target on Hancock Whitney (HWC), tied to the bank's all-stock acquisition of Trustmark (TRMK).
Stifel analyst Brian Chin lowered his Applied Materials (AMAT) price target, citing datacenter buildout fears.
With the 10-year at 5.15% and Nvidia earnings due next week, the question for chip stocks is whether this week's rotation has finished unwinding.
Not financial advice. For informational and educational purposes only.