For $INTC shareholders, PC weakness is setting the pace even as Data Center and AI revenue grows 78%.
For $INTC shareholders, PC weakness is setting the pace even as Data Center and AI revenue grows 78%. I think the Q4 outlook explains why shares fell 20.71% after hours to $73.
- Data Center and AI revenue reached $7.3 billion in Q3, up 78% year over year. I'm watching whether Intel can expand Xeon supply to meet demand.
- Client Computing and Physical AI revenue was $8.1 billion, down 5%. CFO David Zinsner expects the PC slowdown to continue at least through the first half of 2027.
- Total Q3 revenue was $16.5 billion, up 21%, while Q4 guidance is $15 billion–$16 billion. Non-GAAP EPS guidance is $0.25 versus $0.52 reported for Q3.
- Intel also guides to a 38.0% non-GAAP gross margin in Q4, down from 44.1% in Q3. Shares were at $73 after hours at 22:25:20 UTC, versus a $92.07 regular-session close.
I'd want to see PC demand stabilize alongside more Xeon supply before treating the data-center growth as a company-wide earnings turnaround. That could take time if management's PC outlook holds.
Sources:
https://www.intc.com/news-events/press-releases/detail/1786/intel-reports-third-quarter-2026-financial-results
https://www.cnbc.com/2026/10/29/intel-intc-q3-earnings-report-2026-.html
Source:
TheStreet: after-hours results analysis: https://pro.thestreet.com/stock-market-today/2026-10-29
Not financial advice. For informational and educational purposes only.
Intel Q4 guide misses by ~$1.6B at the midpoint; Israel fab hit is ~$300M, so ~80% of the gap is the PC slump
Intel beat on Q3 Thursday but guided Q4 revenue to $15B to $16B vs ~$17.1B expected. Shares fell ~20%…
Amazon Q3: small miss, AWS +39% to $46.0B; $77.3B capex is ~1.7x AWS quarterly revenue and AWS made 63% of operating profit
Amazon reported Q3 Thursday: a small miss on revenue and EPS, but AWS grew 39% to $46.0B. Shares fell…
End-of-day recap
Oct 29 brought sharp tech drops, a cash deal and mixed index closes.
Oct 29 brought sharp tech drops, a cash deal and mixed index closes. Alphabet closed at $283.82, down 12.64%. Earnings and revenue missed expectations, and Search revenue missed forecasts for a second straight quarter. CNBC tied the drop to those results and fears AI chat and agents are taking Search volumes.
End of the Gold Standard — $35 Peg to $4,038 Gold
On August 15, 1971, Nixon closed the gold window, ending the dollar's fixed $35-an-ounce peg from Bretton Woods and setting gold free to float.
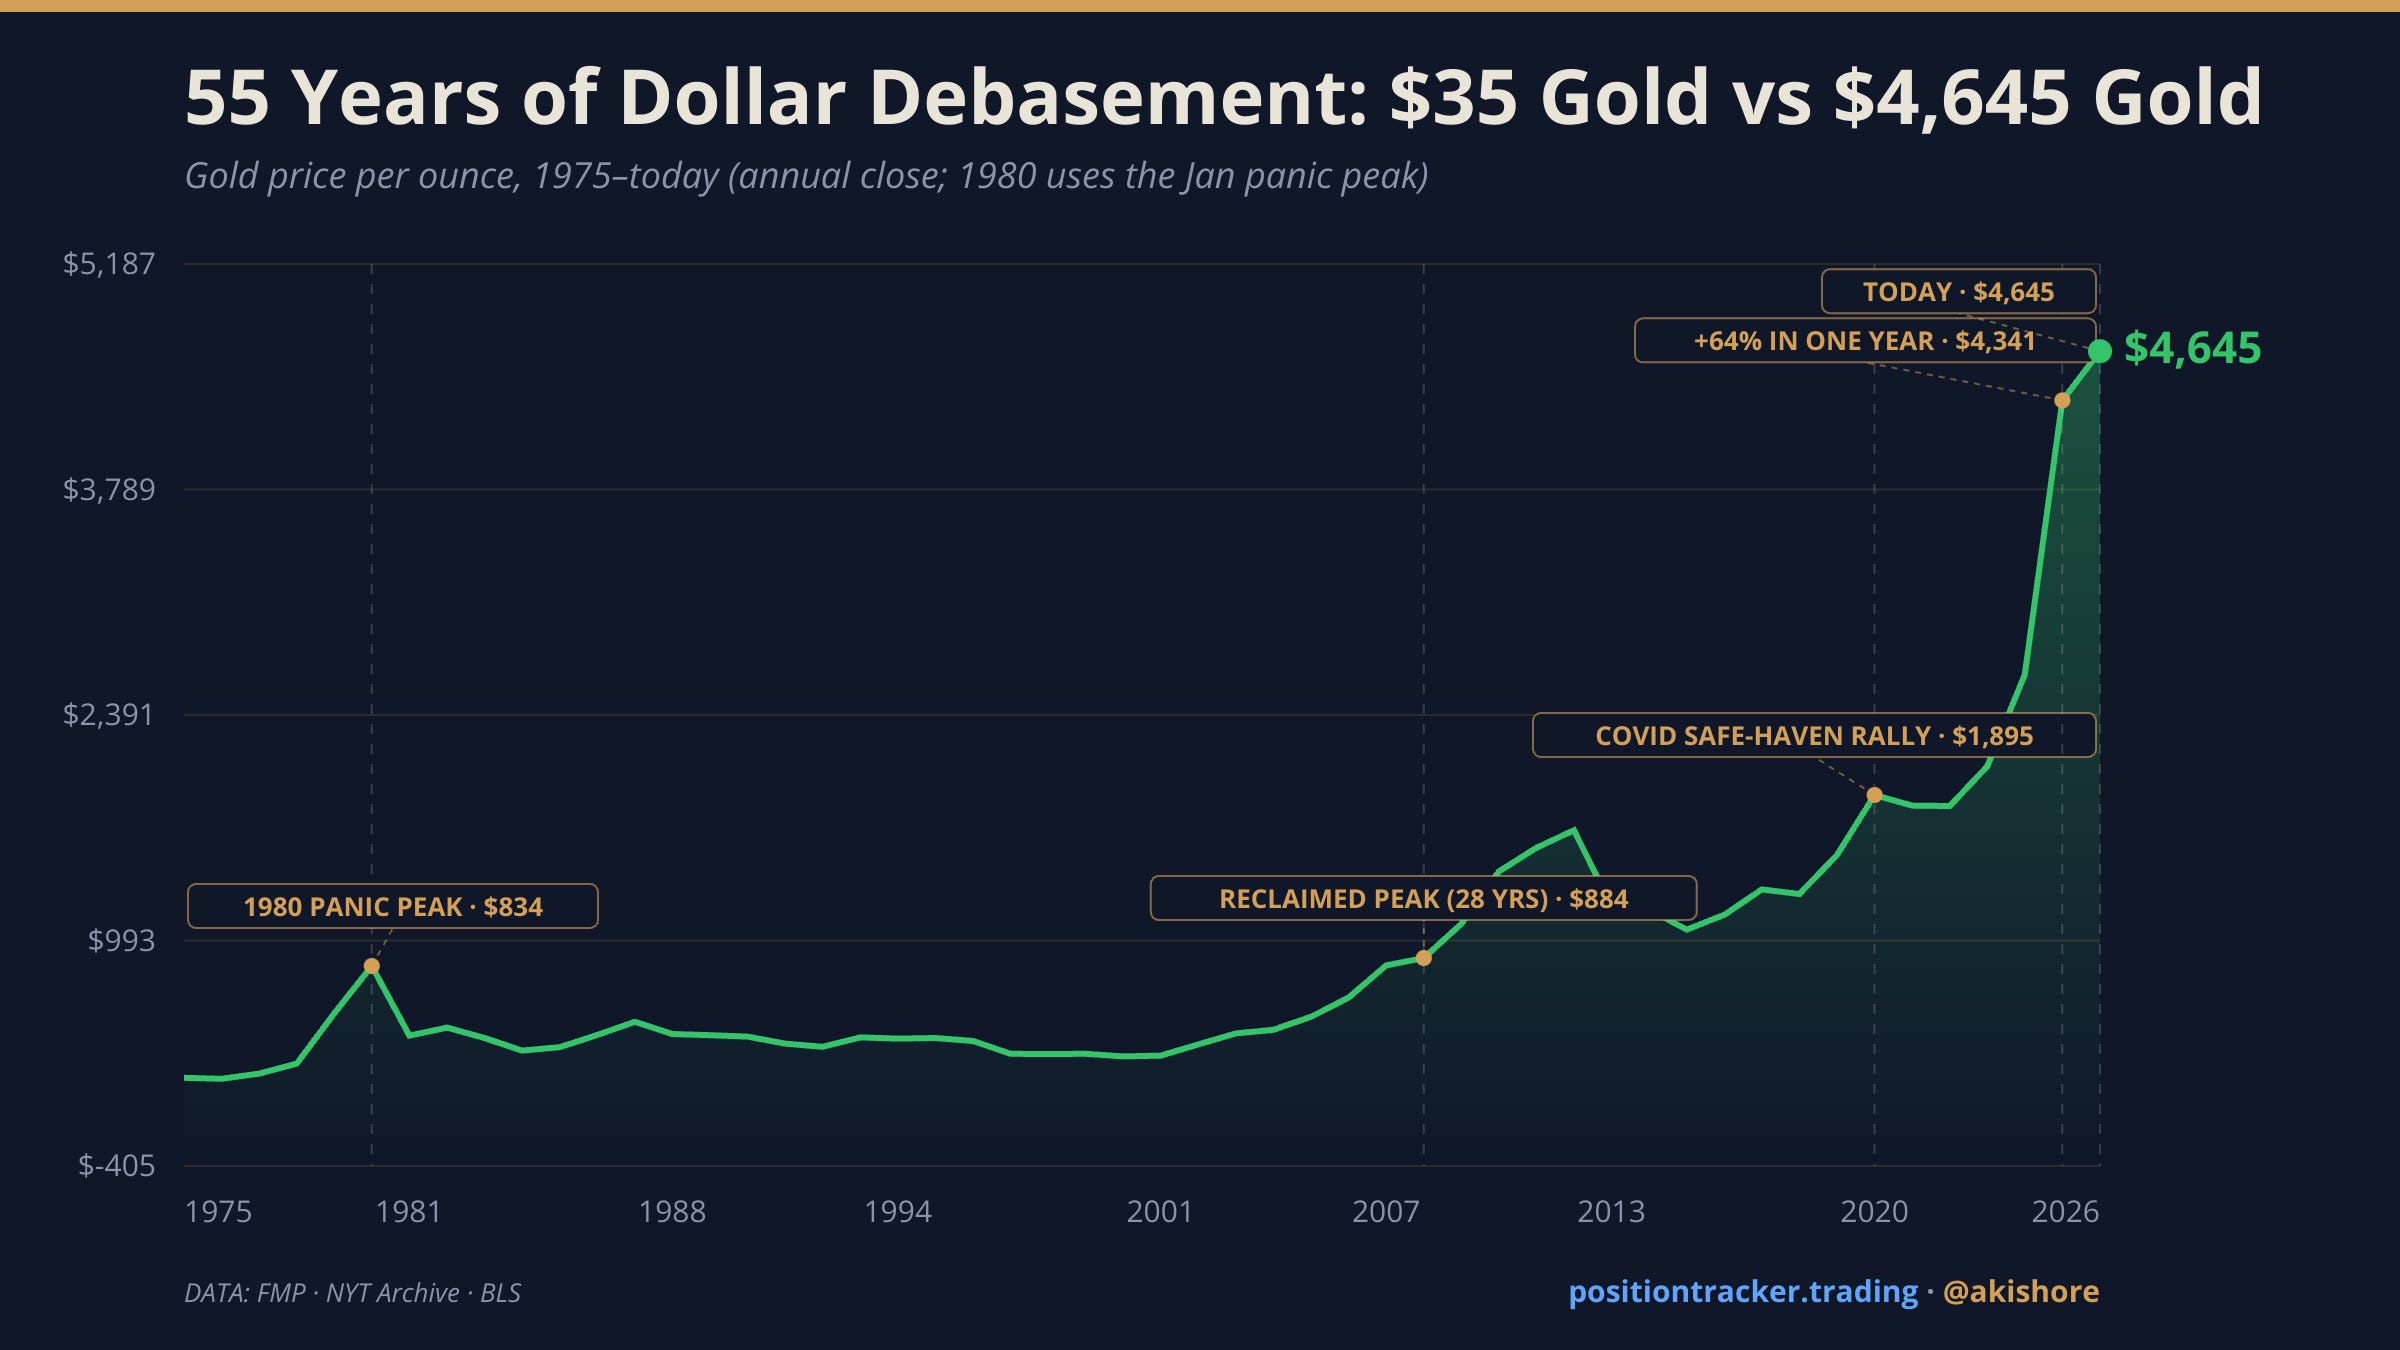
On August 15, 1971, Nixon closed the gold window, ending the dollar's fixed $35-an-ounce peg from Bretton Woods and setting gold free to float. Fifty-five years later, gold futures are at $4,038.20 an ounce, about 115 times the old peg.