$FTNT daily pick: sell Jan 15 $110 put (buy-side) below the post-earnings low
$FTNT: I'm selling the Jan 15 $110 put on @Fortinet.
At Friday's close ($127.22, markets closed today):
35% off the October high and 3% under the 200-day
Q3 revenue up 20% and billings up 29%
$2.16 credit, breakeven $107.84
About 2% in 61 days (~12% annualized)
I think the selloff went too far because the miss was a small cut to service revenue guidance while billings, revenue and EPS guidance all went up. The $110 strike is below the lowest close since the drop.
At $107.84 I would own Fortinet at about 30x this year's adjusted EPS guide, which I think is a fair price for a company that just raised its outlook again.
Not financial advice
What happened: on Oct 28 Fortinet reported Q3 revenue of $2.08B (up 20%) and adjusted EPS of $0.91 against $0.86 expected. Product revenue rose 37% but service revenue grew only 13% and the company cut its full-year service revenue guide to $5.15B to $5.17B from $5.18B to $5.22B. The stock fell 20% the next day.
Why I still want to own it: management raised full-year revenue guidance to $8.125B to $8.215B and adjusted EPS guidance to $3.54 to $3.58. The CFO said the services gap comes from large new customers that buy hardware first and turn on services in stages. Fortinet also added $1.2B to its buyback, leaving $2B authorized.
Why a put and not the stock: even after the drop the stock is up about 60% this year, so I would rather get paid to wait. The $110 put pays $216 per contract and gives me a cost basis of $107.84, below the Nov 6 close of $118.84.
The risks: Q4 revenue guidance implies about 15% growth (down from 20% in Q3) and BofA downgraded it to Neutral on slower product growth. Mizuho cut its target to $118 and Wells Fargo to $115. The trade expires before the next report, which Robinhood has as Feb 4 (tentative).
Sources: Yahoo Finance: Q3 revenue $2.08B +20%, product +37% to $765M, billings +29% to $2.34B, adj. EPS $0.91, FY26 revenue and · SiliconANGLE: Q3 adj. EPS $0.91 vs $0.86 expected, services +13% to $1.31B, service guide cut to $5.15B-$5.17B, raised r · 24/7 Wall St: CFO on services timing, service guide cut, Q4 guide implies ~15% revenue growth · Investing.com Q3 call transcript: FY26 guidance, Q4 guide (15% revenue growth at midpoint), $1.2B buyback increase to $2 · TIKR: Q3 figures, $1.2B buyback with $2B authorized, CFO on gradual service activation, Wells Fargo $115 · Investing.com: BofA downgrades to Neutral, PT $140 from $220, product growth slowed from 52% to 37%
Not financial advice. For informational and educational purposes only.
Social Security trust fund ran a record ~$220B deficit in FY2026: about $600M a day, income covers ~85% of costs vs the 77% benefit level after 2032
Social Security's retirement trust fund ran a record deficit of about $220 billion in fiscal 2026, which ended September 30.…
QQQ short interest at 11%, highest since 2023: 82.8M shares is ~$56B at $679.89, and 1.9 days to cover means about two sessions to unwind
Short interest in the Invesco QQQ Nasdaq 100 ETF hit 11% of shares outstanding, the highest since 2023, The Kobeissi Letter said Sunday. That is…
Anthropic IPO ~7x oversubscribed; company and backers seek up to $90.4B
Anthropic's IPO is roughly 7x oversubscribed, according to Bloomberg sources, with the company and some…
fmp-historical-post · Volcker's employment toll
U.S. unemployment was 10.8% in December 1982 and 4.2% in September 2026: a gap of 6.6 percentage points.
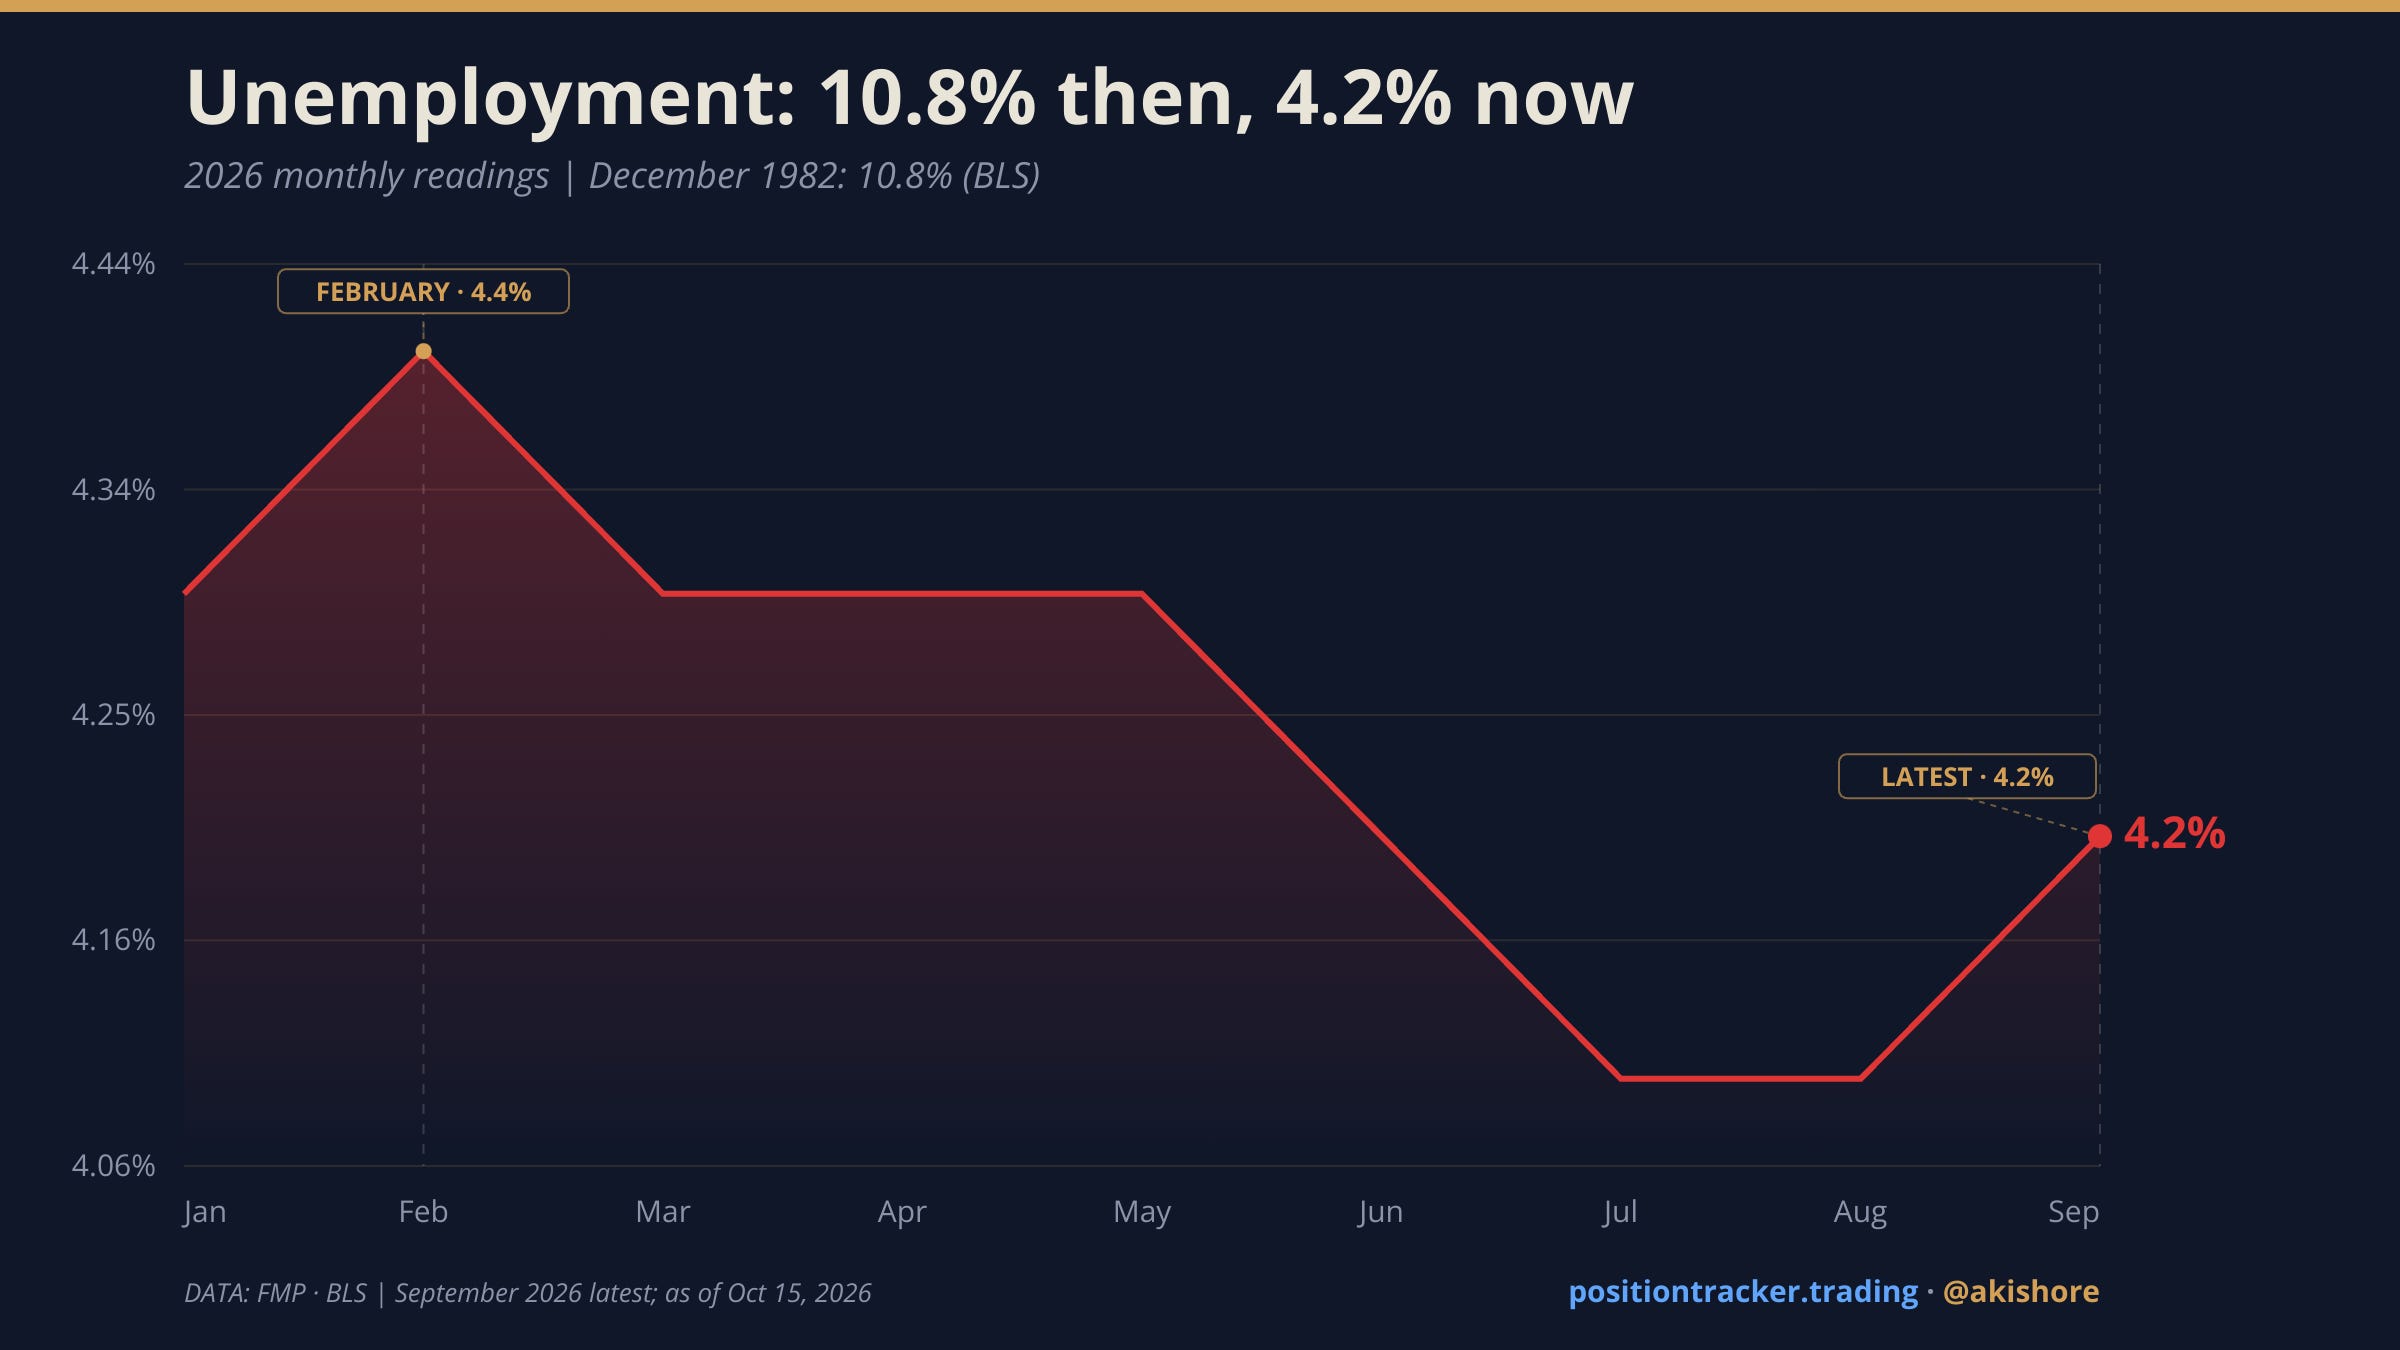
U.S. unemployment was 10.8% in December 1982 and 4.2% in September 2026: a gap of 6.6 percentage points. The rate at the end of the Volcker recession was more than twice the September 2026 reading. That puts the job market of…