I like the open-weight angle, but I'd treat $PANW's $4.5 billion Applied Compute agreement as an adoption bet.
I like the open-weight angle, but I'd treat $PANW's $4.5 billion Applied Compute agreement as an adoption bet. I want to see what customers do with it.
- The all-stock deal was announced Nov. 18 and is subject to adjustments. Palo Alto's pitch is secure model tuning. Closing is expected in fiscal Q3 2027, pending regulatory clearance and customary conditions.
- Palo Alto says it evaluated Applied Compute as a prospective customer. I see that as useful product diligence. Palo Alto's 70,000+ customers are the buyer's customers, so I wouldn't use that figure to judge demand for Applied Compute.
- The shares were $371.08 premarket on Nov. 19, up 9.17% from the prior close. Reuters tied the rise chiefly to raised FY2027 guidance. Fiscal Q1 revenue was $3.44 billion, up 39% year over year.
I'd watch for clearance, then disclosed customer adoption after integration. The stronger outlook gives me something concrete today; the AI deal still has to earn its price.
Sources:
https://www.paloaltonetworks.com/company/press/2026/palo-alto-networks-to-acquire-applied-compute--bringing-secure-open-weight-ai-to-the-enterprise
https://www.reuters.com/legal/litigation/palo-altos-raised-sales-forecast-powers-cybersecurity-stock-rally-2026-11-19/
Source:
Agentdex: deal timeline and source links: https://agentdex.app/news/2026-11-19/
Not financial advice. For informational and educational purposes only.
Anthropic slipped another 1.13% after-hours to $88.30.
Anthropic slipped another 1.13% after-hours to $88.30. In Friday's regular session, shares touched $83.05, nearly their $83 IPO price and 14.53% below the previous close. They recovered to close at $89.305, down 8.09%…
Citi shares touched $110.175 in the regular session, 4.43% below the previous close, and finished at $110.72, down 3.96%.
Citi shares touched $110.175 in the regular session, 4.43% below the previous close, and finished at $110.72, down 3.96%. They traded at $110.99 after hours, up 0.24% from that close. Reuters reported that incorrectly recorded trades at Citi's UK trading subsidiary led to an understatement of about…
The one number that actually matters in HSBC's Nov.
The one number that actually matters in HSBC's Nov. 20 upgrade of $TSLA is $212. Everything above that in the bank's $359 price target rests on a hypothetical SpaceX deal that has no formal terms on the table. HSBC analyst…
Afternoon update
Global Payments rose 10.51% on reported GTCR takeover interest as semiconductor weakness weighed on the broader market.
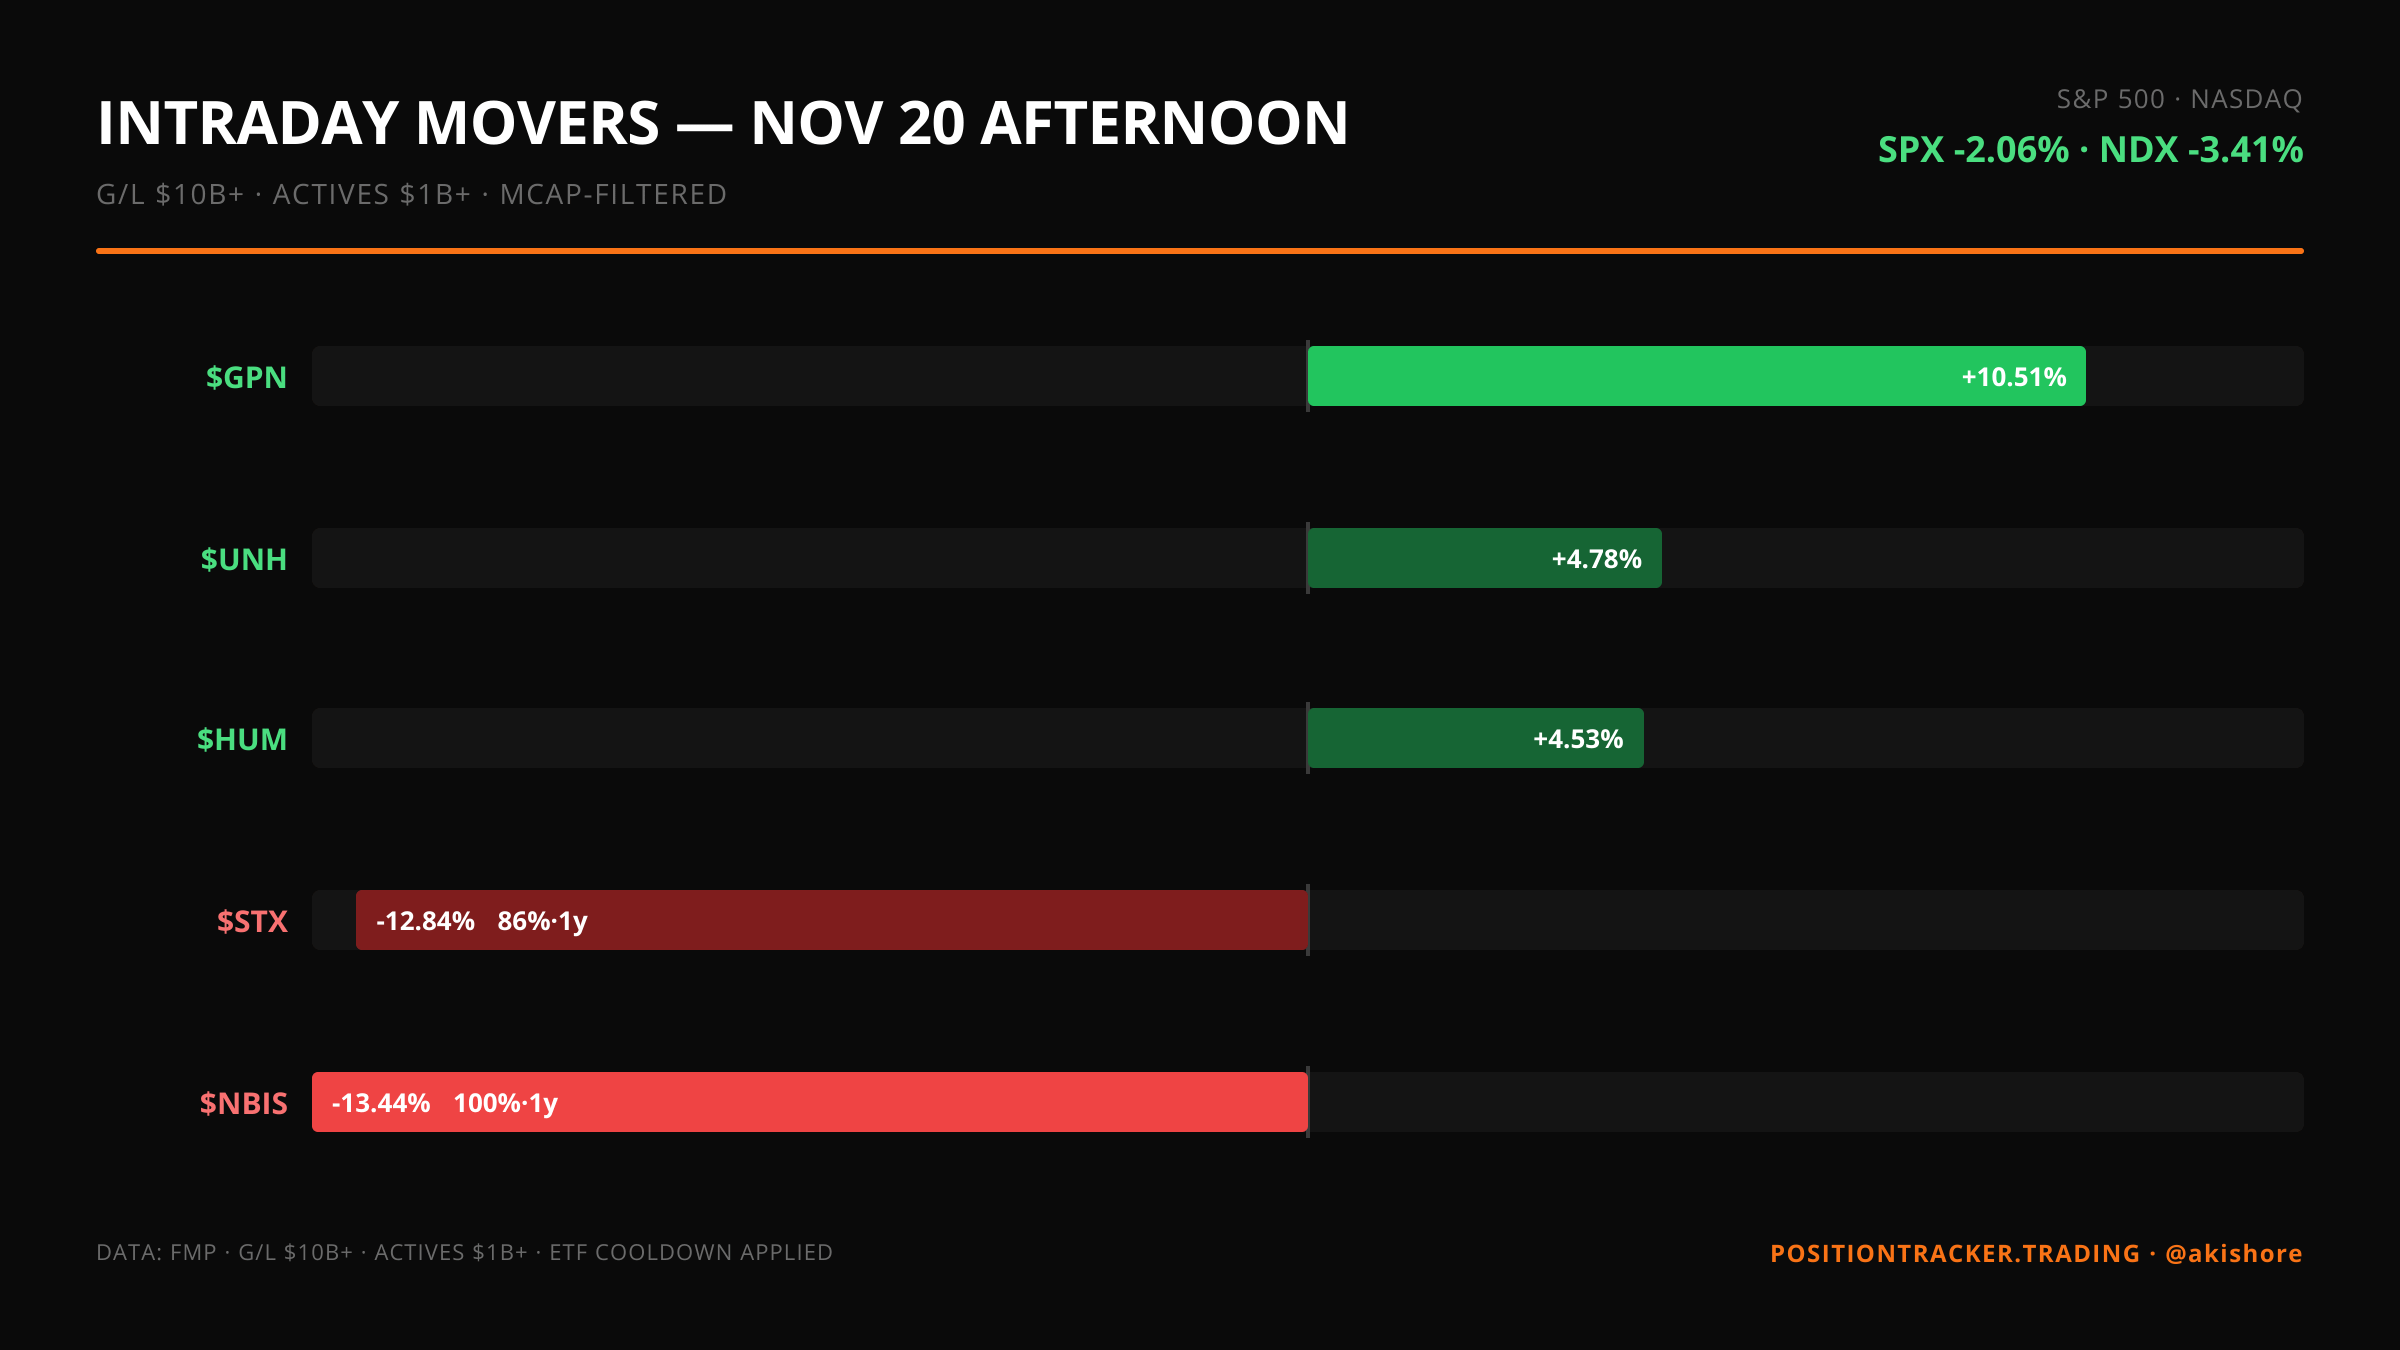
$GPN rose 10.51% on November 20 after a report that GTCR is considering a $50B takeover bid. The Nasdaq fell 3.41% in the afternoon session. Global Payments gained 10.51% at a $24.4B market cap. Shares jumped on the reported GTCR interest; the bid remains a report, not a confirmed…