I think $DHI's outlook matters more than its earnings miss.
I think $DHI's outlook matters more than its earnings miss. Homebuyers may keep seeing incentives, while investors have to judge how much those incentives cost Horton.
- Fiscal Q4 EPS was $2.67, below the $3.03 Zacks estimate reported by AP. Revenue beat the Zacks estimate, though net income fell 18% to $741.8 million.
- Horton's initial fiscal 2027 revenue guide is $30–32 billion, compared with $33.043 billion in fiscal 2026. It expects 79,000–84,000 closings, compared with 84,202 this year.
- The company said orders fell 7% in Q4 and expects incentives to remain elevated in fiscal 2027. That puts homebuilding margins and the conversion of orders into closings on my watch list.
- A $91.4 million rental inventory impairment also weighed on the quarter. I'd keep that separate from the homebuilding trend.
My read: the lower initial guide calls for patience. I want to see whether incentives help turn orders into closings without putting more pressure on margins.
Sources:
https://investor.drhorton.com/news-and-events/press-releases/2026/10-29-2026-103058484
https://wtop.com/national/2026/10/d-r-horton-fiscal-q4-earnings-snapshot/
Not financial advice. For informational and educational purposes only.
Quote post: @unusual_whales on Microsoft's first bond sale since 2017
Microsoft is selling at least $25B of bonds, its first deal since a $17B raise in 2017. That's 47% bigger. I…
Microsoft seeks $25B+ in first US investment-grade bond sale since 2017 to fund AI capex
Microsoft is looking to raise at least $25 billion in its first US investment-grade bond…
$MSFT deep dive: beat on everything with Azure up 48% and the stock barely moved. I think it's a buy
$MSFT beat on everything last night and the stock barely moved. I think it's a buy. FY27 Q1: revenue $92.3B (+19%) with an operating margin near 50%. Azure grew 48% to $33.2B and the commercial backlog jumped 73% to $677B. Next quarter Azure is guided to 49% to 50% growth.
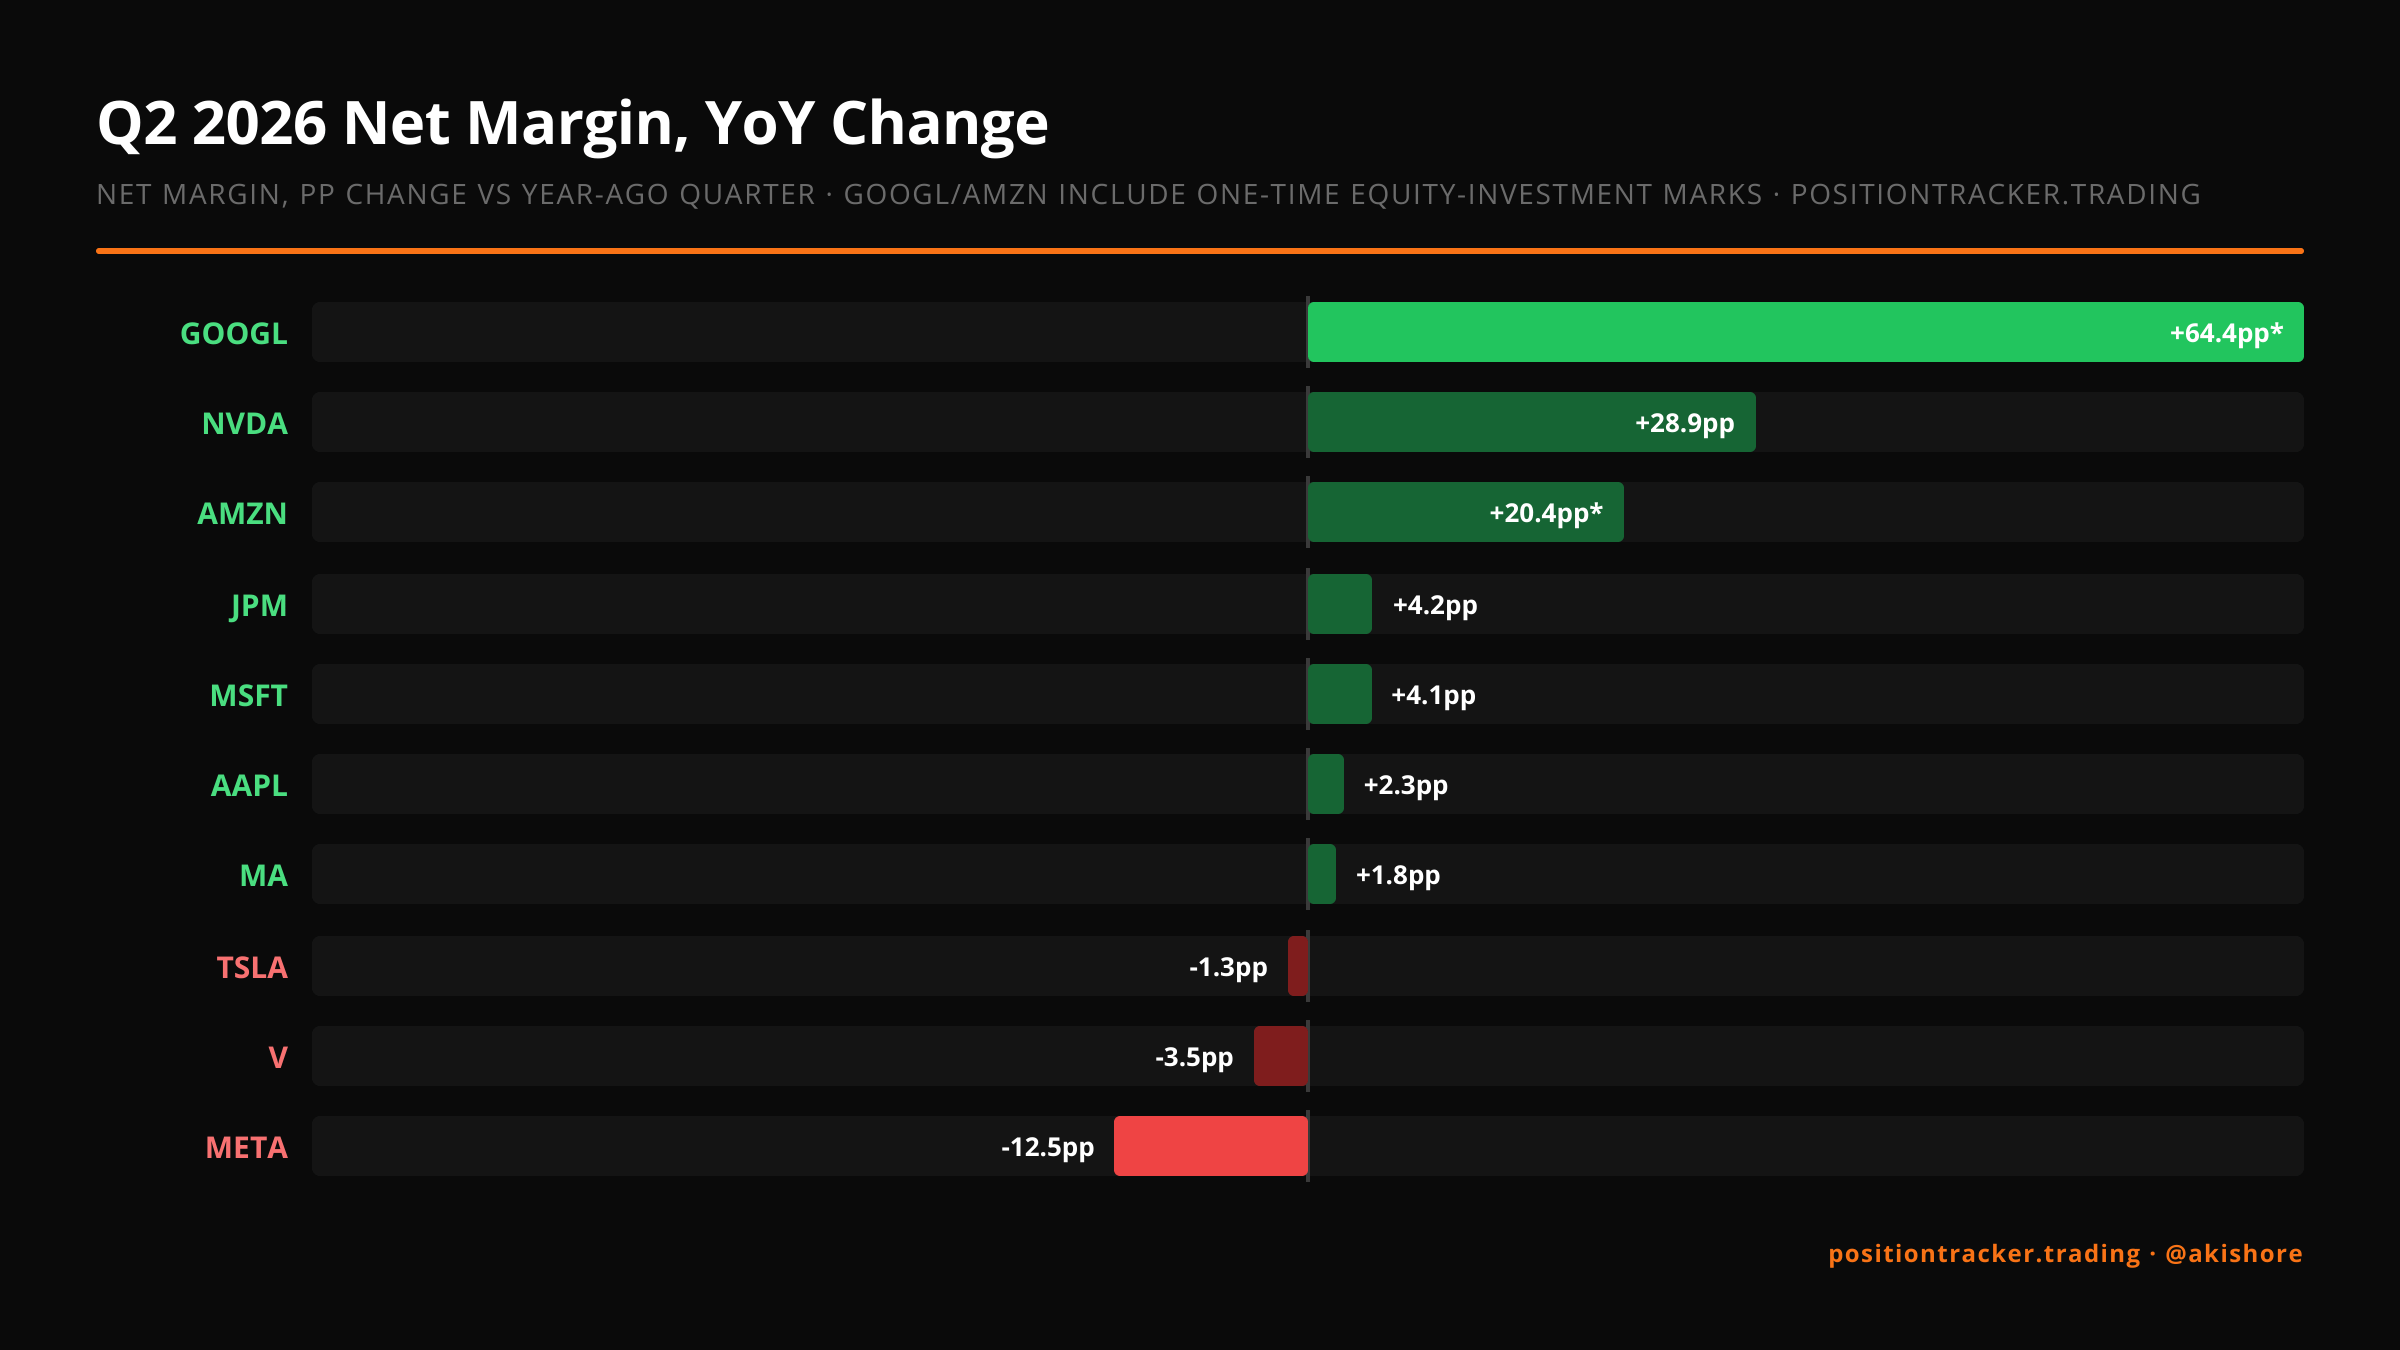
Latest Earnings Show Why Net Margins Need Context
$GOOGL reached $280.36 this morning, 13.71% below its pre-earnings close, after Alphabet reported Q3 EPS and revenue below estimates.
$GOOGL reached $280.36 this morning, 13.71% below its pre-earnings close, after Alphabet reported Q3 EPS and revenue below estimates. Shares recovered 1.59% from that low to $284.82, still down 12.33%. Search advertising growth slowed to 12%, while $51.4B in capital spending…