I think $MMS shareholders need to read the fiscal 2027 cash-flow forecast with a timing footnote.
I think $MMS shareholders need to read the fiscal 2027 cash-flow forecast with a timing footnote. The jump from fiscal 2026 is partly a collection catch-up, so I'd want to see how much of it holds once collections settle.
- Fiscal 2026 free cash flow was $69.1 million, down from $366.2 million in fiscal 2025. Maximus guides to $700–$800 million for fiscal 2027.
- The company says it collected more than $330 million from a major customer after year-end through November 13. Those shifted collections are included in the fiscal 2027 outlook.
- The forecast assumes days sales outstanding falls from 93 days at September 30 to its historical 60–70-day range. That's the number I'd watch for evidence that cash conversion is recovering.
- Fiscal 2027 adjusted EPS guidance of $7.50–$8.00 follows $8.24 in fiscal 2026, which included an estimated $1.05 per-share incentive benefit. The outlook also includes roughly ten months of Agile Defense following its November 18 acquisition.
My read: the guidance has a plausible bridge, but shareholders need to see the collections and Agile Defense integration flow through to cash. The next DSO update matters more to me than the headline jump.
Source:
MT Newswires: Maximus earnings and outlook: https://www.fidelity.com/news/article/company-news/202611190651MIDNIGHTUSEQUITY_A3757238
Not financial advice. For informational and educational purposes only.
Anthropic slipped another 1.13% after-hours to $88.30.
Anthropic slipped another 1.13% after-hours to $88.30. In Friday's regular session, shares touched $83.05, nearly their $83 IPO price and 14.53% below the previous close. They recovered to close at $89.305, down 8.09%…
Citi shares touched $110.175 in the regular session, 4.43% below the previous close, and finished at $110.72, down 3.96%.
Citi shares touched $110.175 in the regular session, 4.43% below the previous close, and finished at $110.72, down 3.96%. They traded at $110.99 after hours, up 0.24% from that close. Reuters reported that incorrectly recorded trades at Citi's UK trading subsidiary led to an understatement of about…
The one number that actually matters in HSBC's Nov.
The one number that actually matters in HSBC's Nov. 20 upgrade of $TSLA is $212. Everything above that in the bank's $359 price target rests on a hypothetical SpaceX deal that has no formal terms on the table. HSBC analyst…
Afternoon update
Global Payments rose 10.51% on reported GTCR takeover interest as semiconductor weakness weighed on the broader market.
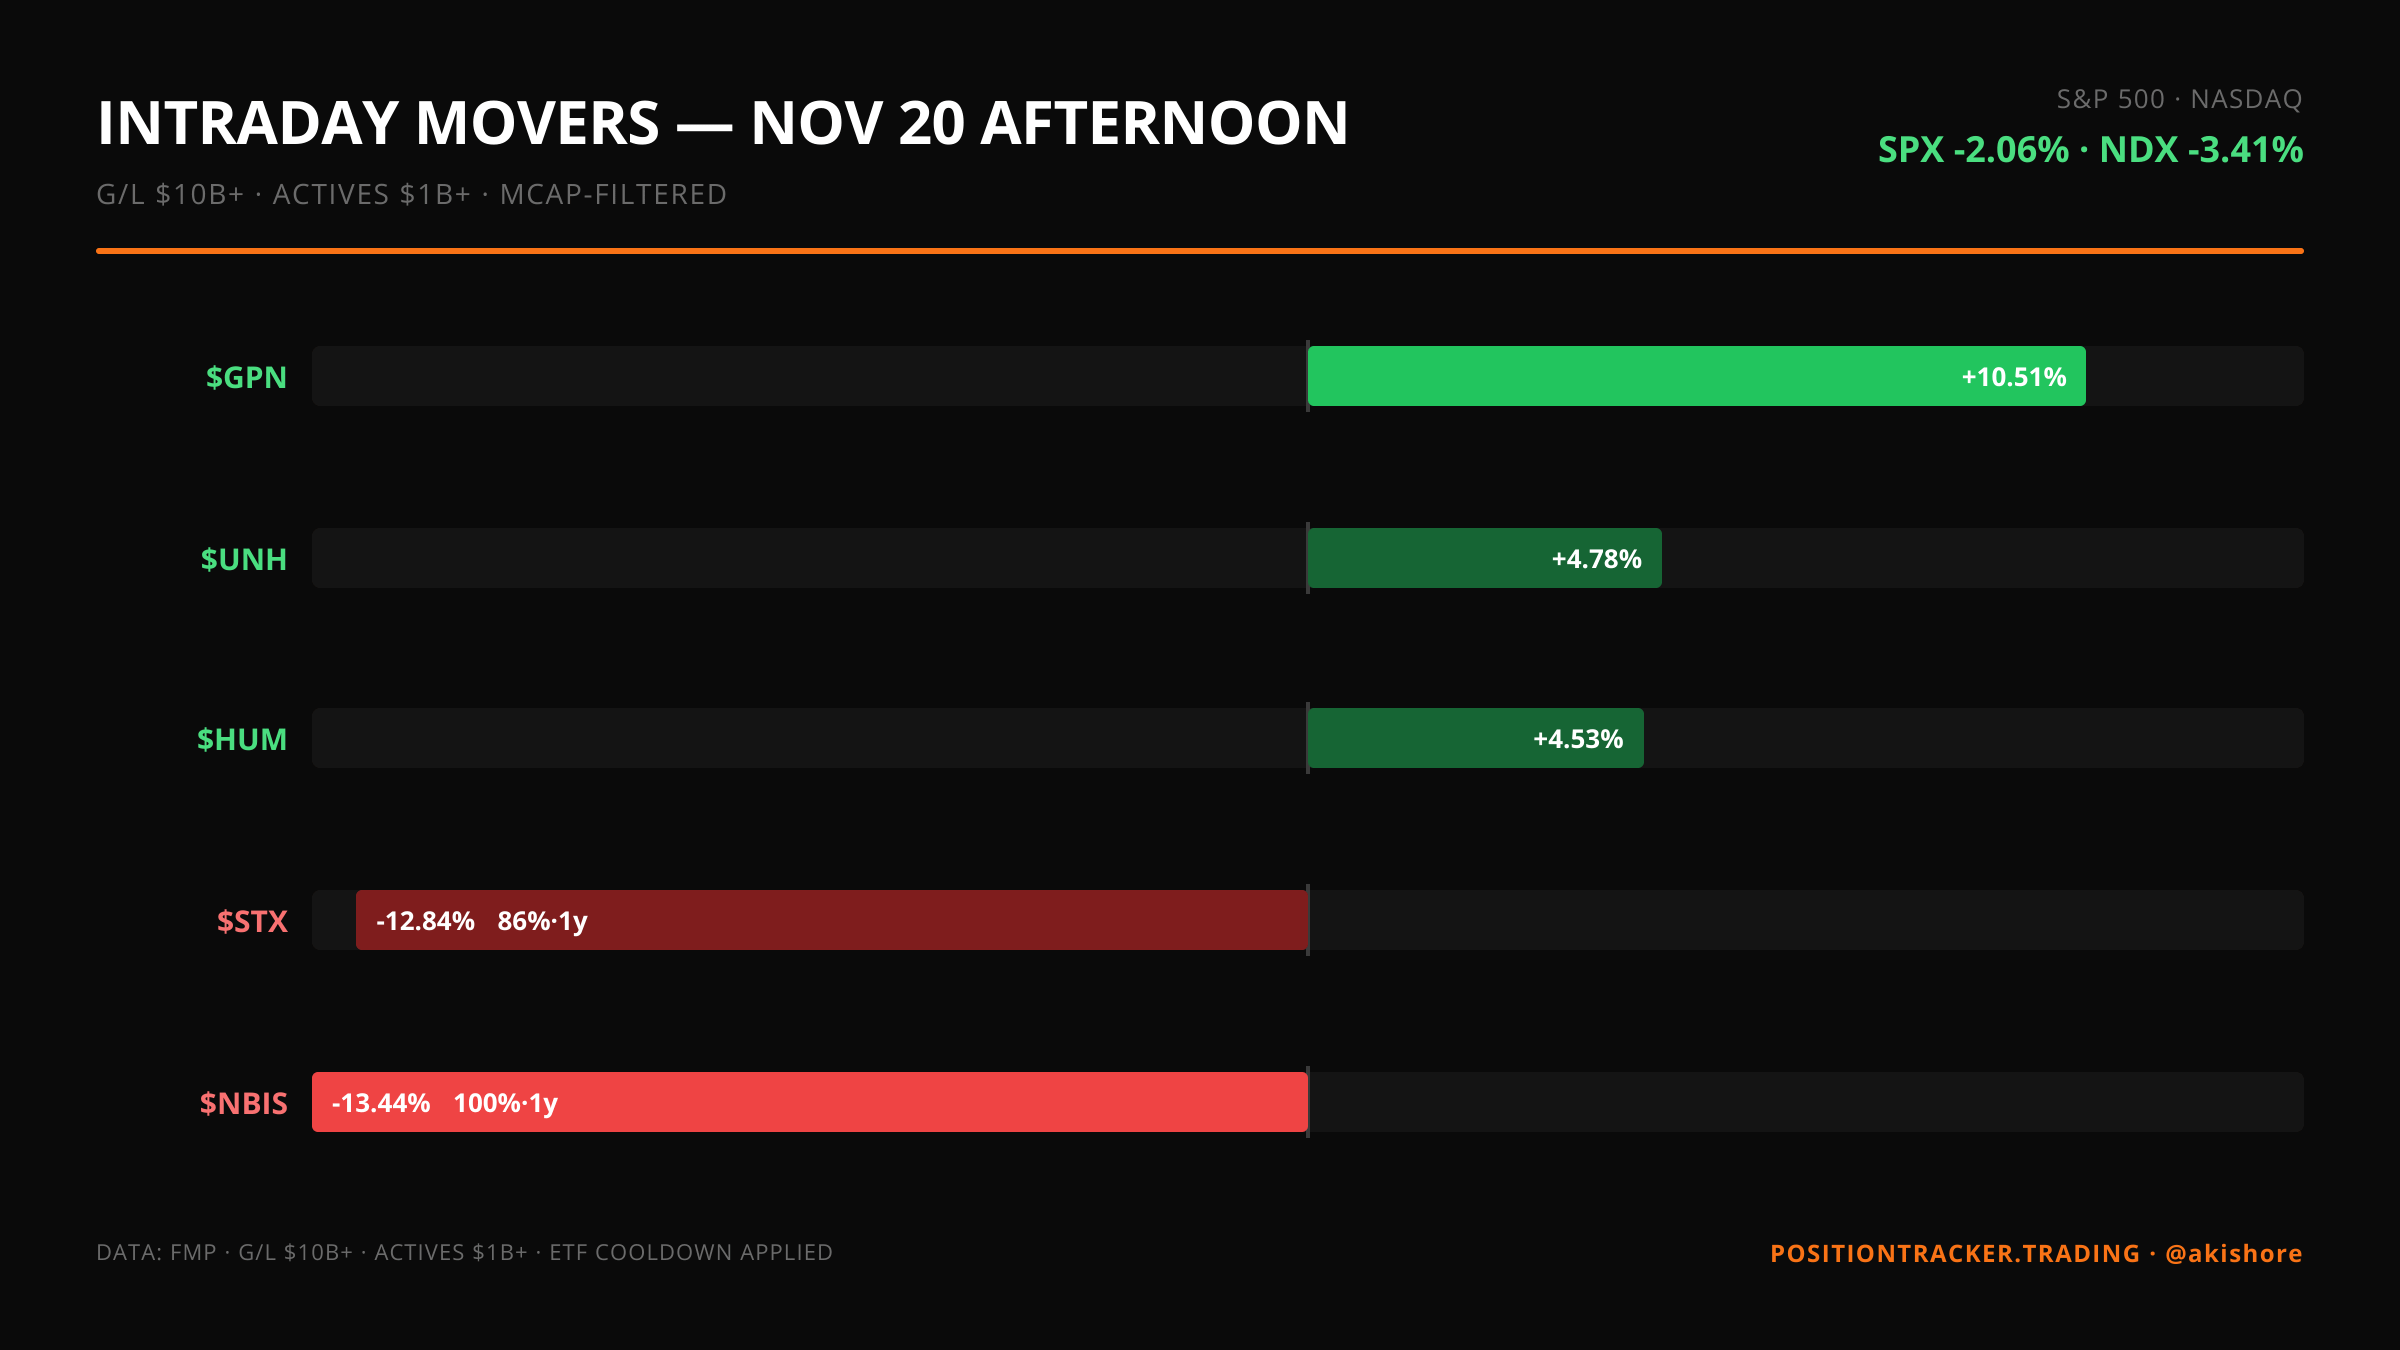
$GPN rose 10.51% on November 20 after a report that GTCR is considering a $50B takeover bid. The Nasdaq fell 3.41% in the afternoon session. Global Payments gained 10.51% at a $24.4B market cap. Shares jumped on the reported GTCR interest; the bid remains a report, not a confirmed…