I think Walmart's upper-income share gains make digital convenience the part of this quarter worth watching.
I think Walmart's upper-income share gains make digital convenience the part of this quarter worth watching. I want to see whether that growth helps margins through the holiday quarter.
- Fiscal Q3 revenue rose 5.2% to $188.8 billion. Walmart says U.S. share gains were led by upper-income households.
- U.S. e-commerce grew 23%, well ahead of the 2.9% rise in U.S. comparable sales excluding fuel. Global e-commerce grew 17%.
- Walmart raised its full-year outlook to 4.9%–5.2% constant-currency net-sales growth and $2.84–$2.89 in adjusted EPS. That earnings range is non-GAAP; Q3 GAAP EPS was $0.62.
- For $WMT, I'd watch whether faster delivery and digital growth support margins through the holiday quarter. The sales growth is clear; the margin payoff is the next thing to check.
My read: Walmart is winning shoppers who have options, and convenience looks like a reason to keep paying attention. I'd keep the adjusted outlook separate from GAAP earnings when judging what that growth is worth.
Sources:
https://www.foxbusiness.com/retail/walmart-raises-full-year-outlook-wealthier-shoppers-fuel-sales-growth
https://corporate.walmart.com/news/2026/11/walmart-releases-q3-fy27-earnings
Not financial advice. For informational and educational purposes only.
Anthropic slipped another 1.13% after-hours to $88.30.
Anthropic slipped another 1.13% after-hours to $88.30. In Friday's regular session, shares touched $83.05, nearly their $83 IPO price and 14.53% below the previous close. They recovered to close at $89.305, down 8.09%…
Citi shares touched $110.175 in the regular session, 4.43% below the previous close, and finished at $110.72, down 3.96%.
Citi shares touched $110.175 in the regular session, 4.43% below the previous close, and finished at $110.72, down 3.96%. They traded at $110.99 after hours, up 0.24% from that close. Reuters reported that incorrectly recorded trades at Citi's UK trading subsidiary led to an understatement of about…
The one number that actually matters in HSBC's Nov.
The one number that actually matters in HSBC's Nov. 20 upgrade of $TSLA is $212. Everything above that in the bank's $359 price target rests on a hypothetical SpaceX deal that has no formal terms on the table. HSBC analyst…
Afternoon update
Global Payments rose 10.51% on reported GTCR takeover interest as semiconductor weakness weighed on the broader market.
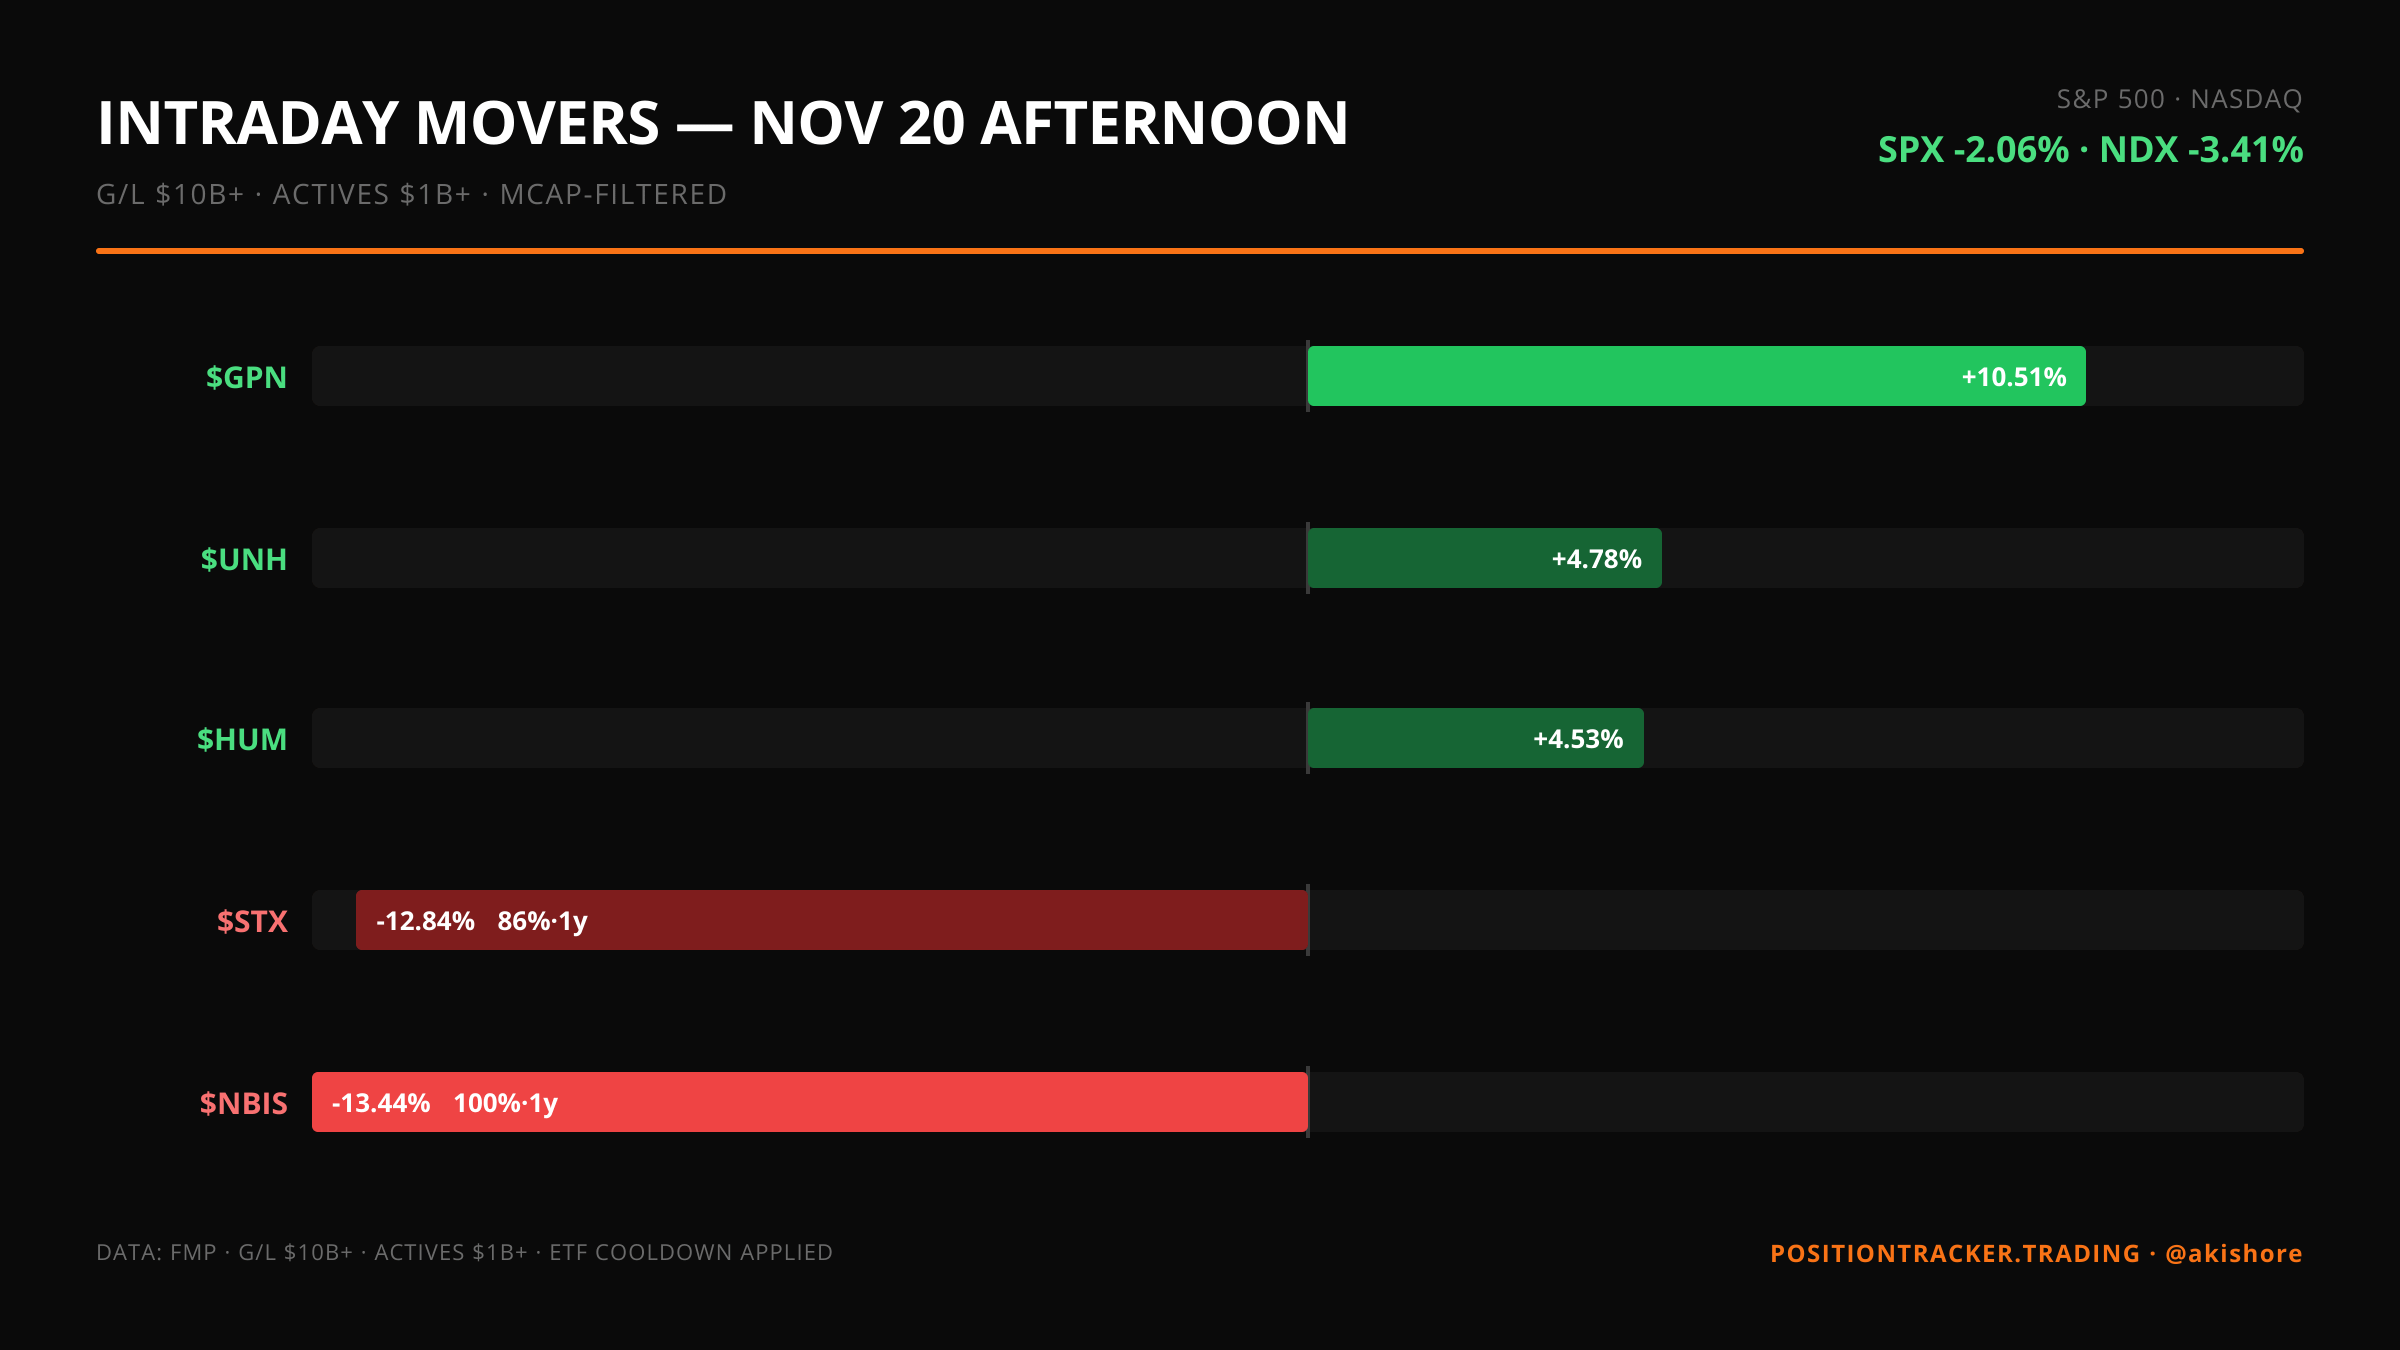
$GPN rose 10.51% on November 20 after a report that GTCR is considering a $50B takeover bid. The Nasdaq fell 3.41% in the afternoon session. Global Payments gained 10.51% at a $24.4B market cap. Shares jumped on the reported GTCR interest; the bid remains a report, not a confirmed…