Keysight's quarter is the kind of AI-adjacent print I trust: hard test equipment that customers had to pay for, with cash flow to back…
Keysight's quarter is the kind of AI-adjacent print I trust: hard test equipment that customers had to pay for, with cash flow to back it up. To me this is real spending, separate from the hype I worry about elsewhere in AI capex.
- Q4 FY26 revenue was $1.99B, up 41% year over year. Non-GAAP EPS rose 89% to $3.61, and GAAP EPS more than doubled to $2.82, so the adjusted number isn't doing all the work.
- Communications Solutions Group grew 51% to $1.496B, with commercial communications up 73%. On the call I want to hear how much of that came from optical and data-center test versus telecom.
- Keysight reported record FY26 revenue of $7.16B, up 33%, and free cash flow of $1.75B. That's the number I check first, and it holds up.
- Q1 FY27 guidance is $2.04B-$2.06B in revenue and $3.63-$3.69 in non-GAAP EPS, a step up from Q4.
$KEYS closed down 1.67% at $281.51 in the November 19 regular session, then traded at $286.99 after hours, up 1.95%. I still think the smaller, debt-heavy AI names are at risk, but suppliers like this one with real cash flow look much better placed to me. I could be wrong if the communications jump turns out to be a one-time pull-forward.
Sources:
https://www.sec.gov/Archives/edgar/data/1601046/000160104626000040/exhibit991-q426pressrelease.htm
Not financial advice. For informational and educational purposes only.
Anthropic slipped another 1.13% after-hours to $88.30.
Anthropic slipped another 1.13% after-hours to $88.30. In Friday's regular session, shares touched $83.05, nearly their $83 IPO price and 14.53% below the previous close. They recovered to close at $89.305, down 8.09%…
Citi shares touched $110.175 in the regular session, 4.43% below the previous close, and finished at $110.72, down 3.96%.
Citi shares touched $110.175 in the regular session, 4.43% below the previous close, and finished at $110.72, down 3.96%. They traded at $110.99 after hours, up 0.24% from that close. Reuters reported that incorrectly recorded trades at Citi's UK trading subsidiary led to an understatement of about…
The one number that actually matters in HSBC's Nov.
The one number that actually matters in HSBC's Nov. 20 upgrade of $TSLA is $212. Everything above that in the bank's $359 price target rests on a hypothetical SpaceX deal that has no formal terms on the table. HSBC analyst…
Afternoon update
Global Payments rose 10.51% on reported GTCR takeover interest as semiconductor weakness weighed on the broader market.
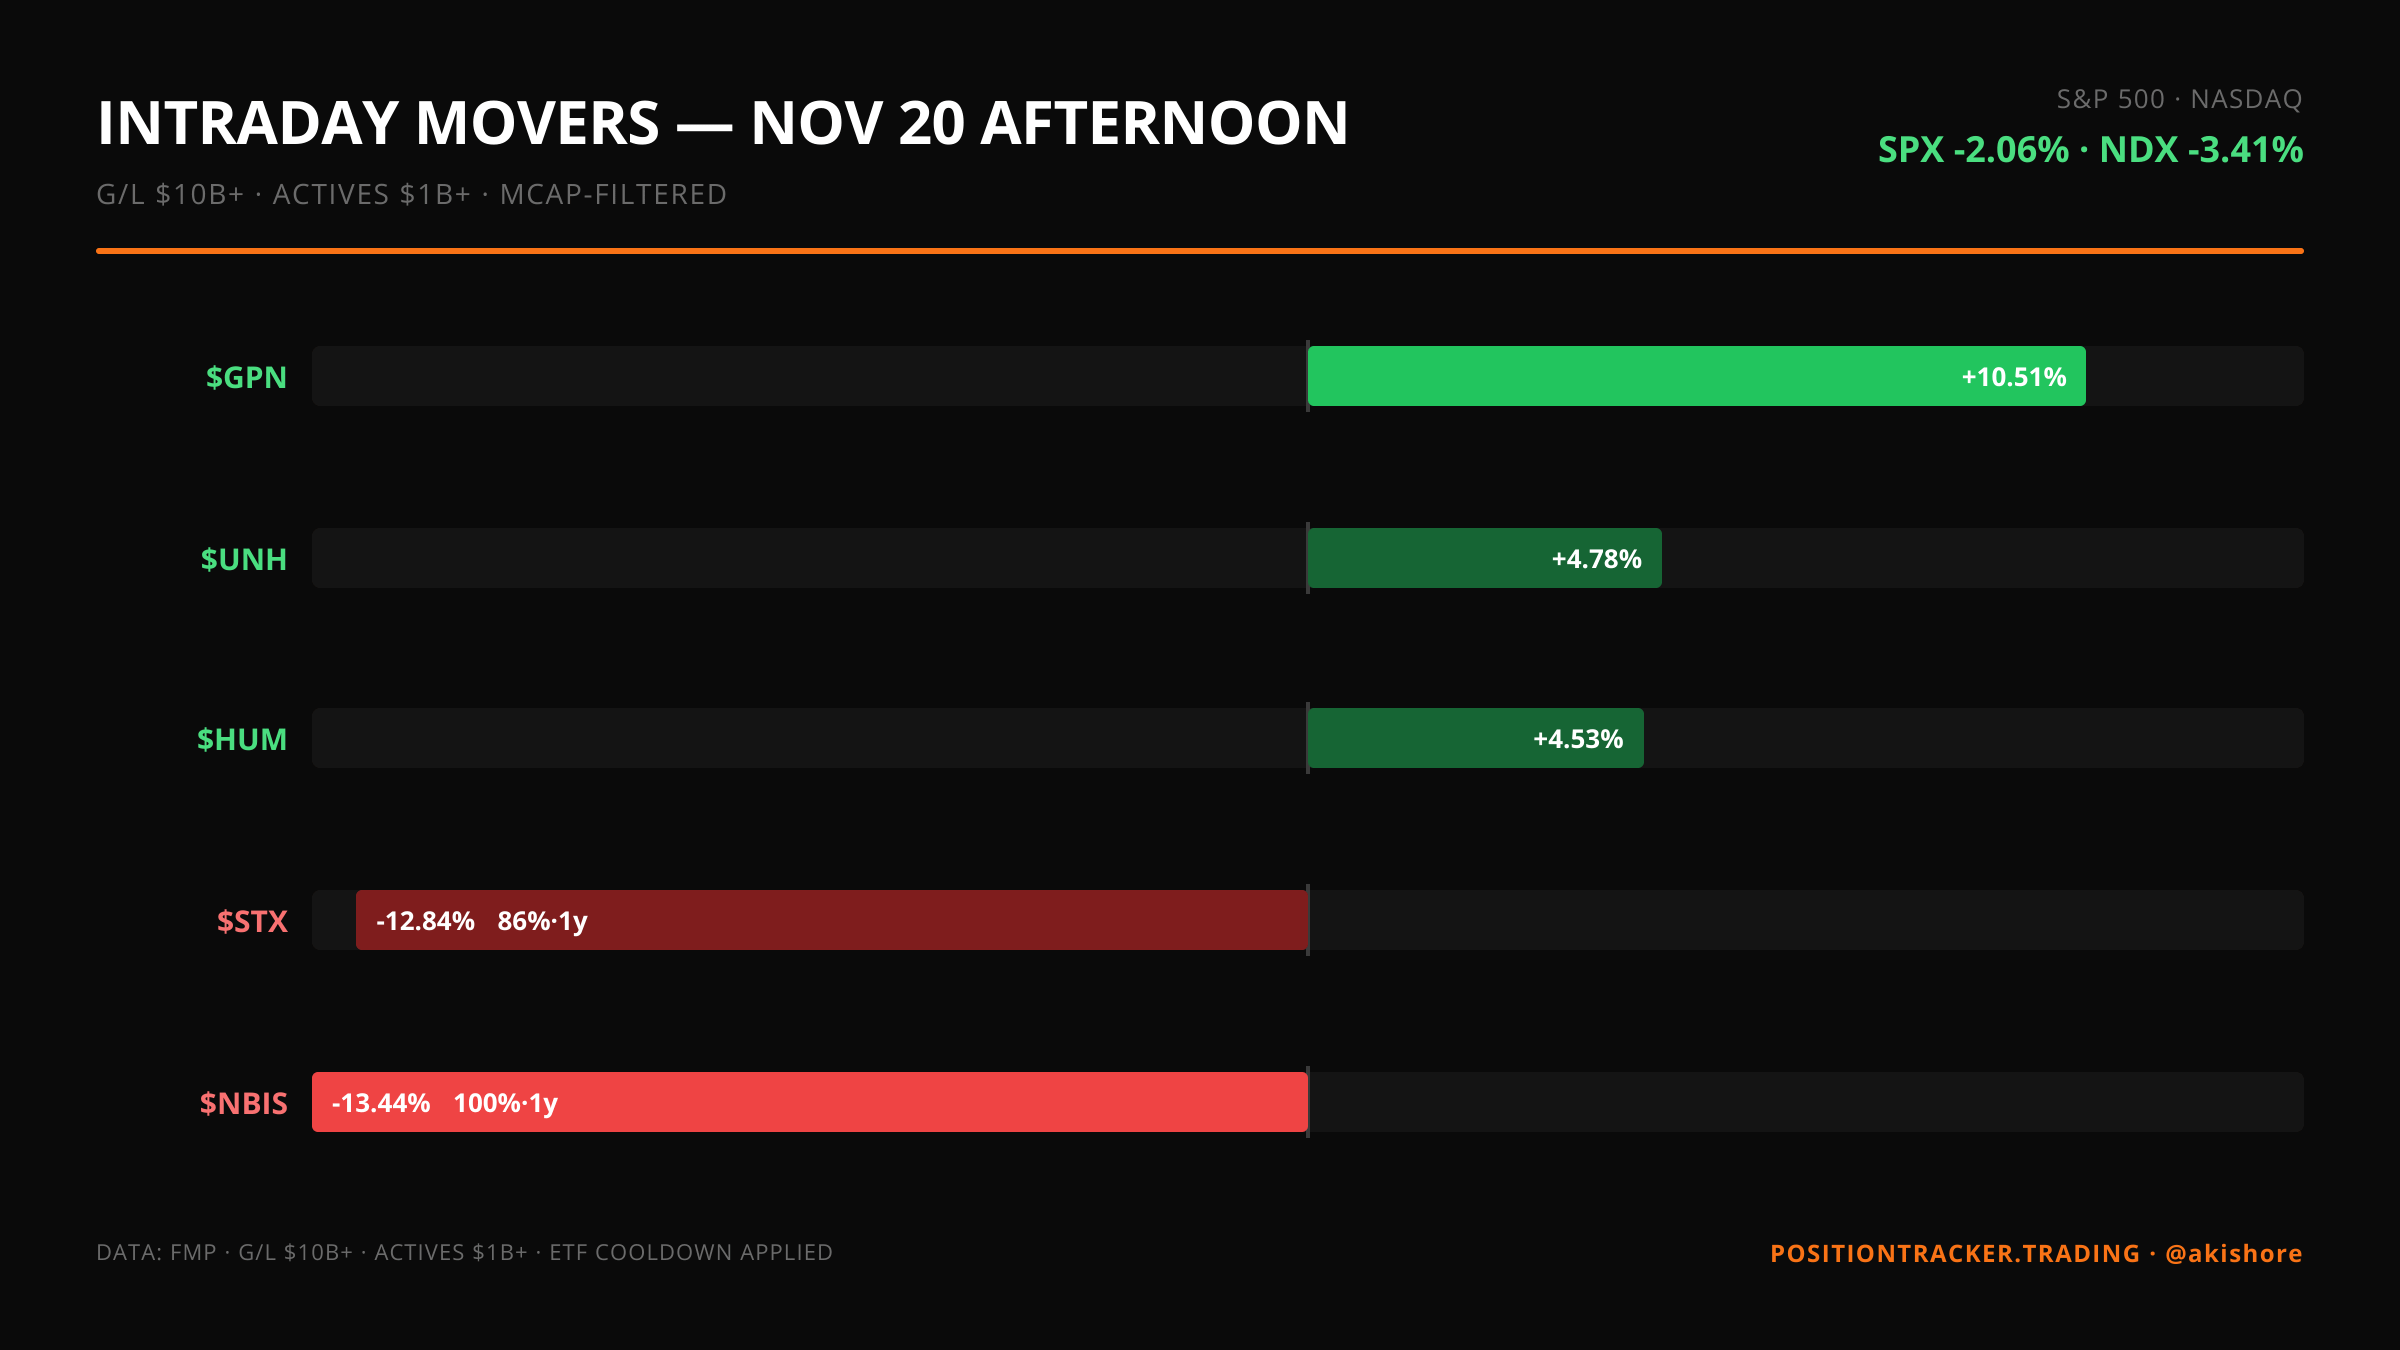
$GPN rose 10.51% on November 20 after a report that GTCR is considering a $50B takeover bid. The Nasdaq fell 3.41% in the afternoon session. Global Payments gained 10.51% at a $24.4B market cap. Shares jumped on the reported GTCR interest; the bid remains a report, not a confirmed…