Negative $434 million.
Negative $434 million. That's Supermicro's operating cash flow in a quarter where it booked $1.594B of net income, and it's the number I'd watch over the headline revenue.
- Q1 FY2027 net sales came in at $19.946B versus $5.018B a year earlier, roughly 4x. GAAP gross margin was 12.7%, down from 17.5% last quarter but up from 9.3% a year ago.
- Receivables absorbed $3.56B of cash and inventory another $2.477B. A $3.054B jump in deferred revenue offset part of it, but not enough to keep operations cash positive.
- Cash sits at $6.897B against $8.6B of bank debt and convertible notes. I wouldn't call that a liquidity crisis, but it leaves less cushion than the profit line suggests.
- Guidance is for $19.5B to $21.5B in Q2 and $72B to $82B for FY2027. Growth at that pace usually keeps eating working capital. $SMCI closed at $31.39 on November 3 and traded at $33.96 after hours, up 8.19%.
The market is paying for the guide, and fair enough. My read is that Q2 receivables and cash conversion will tell us whether this growth turns into cash, and I could be wrong if deferred revenue keeps scaling with sales.
Sources:
https://www.wsj.com/business/earnings/super-micro-computer-revenue-surges-on-ai-infrastructure-demand-32e5542c
https://www.fool.com/investing/2026/11/03/supermicro-s-sales-quadruple-as-cash-drains-rapid-earnings-reaction/
Not financial advice. For informational and educational purposes only.
Arista Q3: Q4 guide beats consensus by ~10% but implies ~8% sequential growth vs 20.5% in Q3
Arista Networks (ANET) reported Q3 after the close Tuesday: revenue up 58.5% to $3.66B (its fastest growth since the 2014 IPO) and a…
AMD Q3: data center added $4.21B YoY while total revenue grew $4.13B, so everything else shrank
AMD (AMD) reported Q3 after the close Tuesday: revenue up 45% to $13.38B, data center up 97% to $8.55B and a Q4 guide of…
Priceline customers and BKNG shareholders are the ones paying for this FTC fight, and Booking just put a number on it: a $900 million…
Priceline customers and BKNG shareholders are the ones paying for this FTC fight, and Booking just put a number on it: a $900 million revenue reduction in Q3, plus a separate $100 million accrued loss. Per Reuters, the matter ties to the FTC's inquiry…
Volcker Shock & the 1980s Bull — 20% Rates to 3.75%-4.00%
In June 1981, the Federal Reserve pushed the Fed Funds rate to 20% to break inflation running at 14.8%, the most aggressive tightening cycle in Fed…
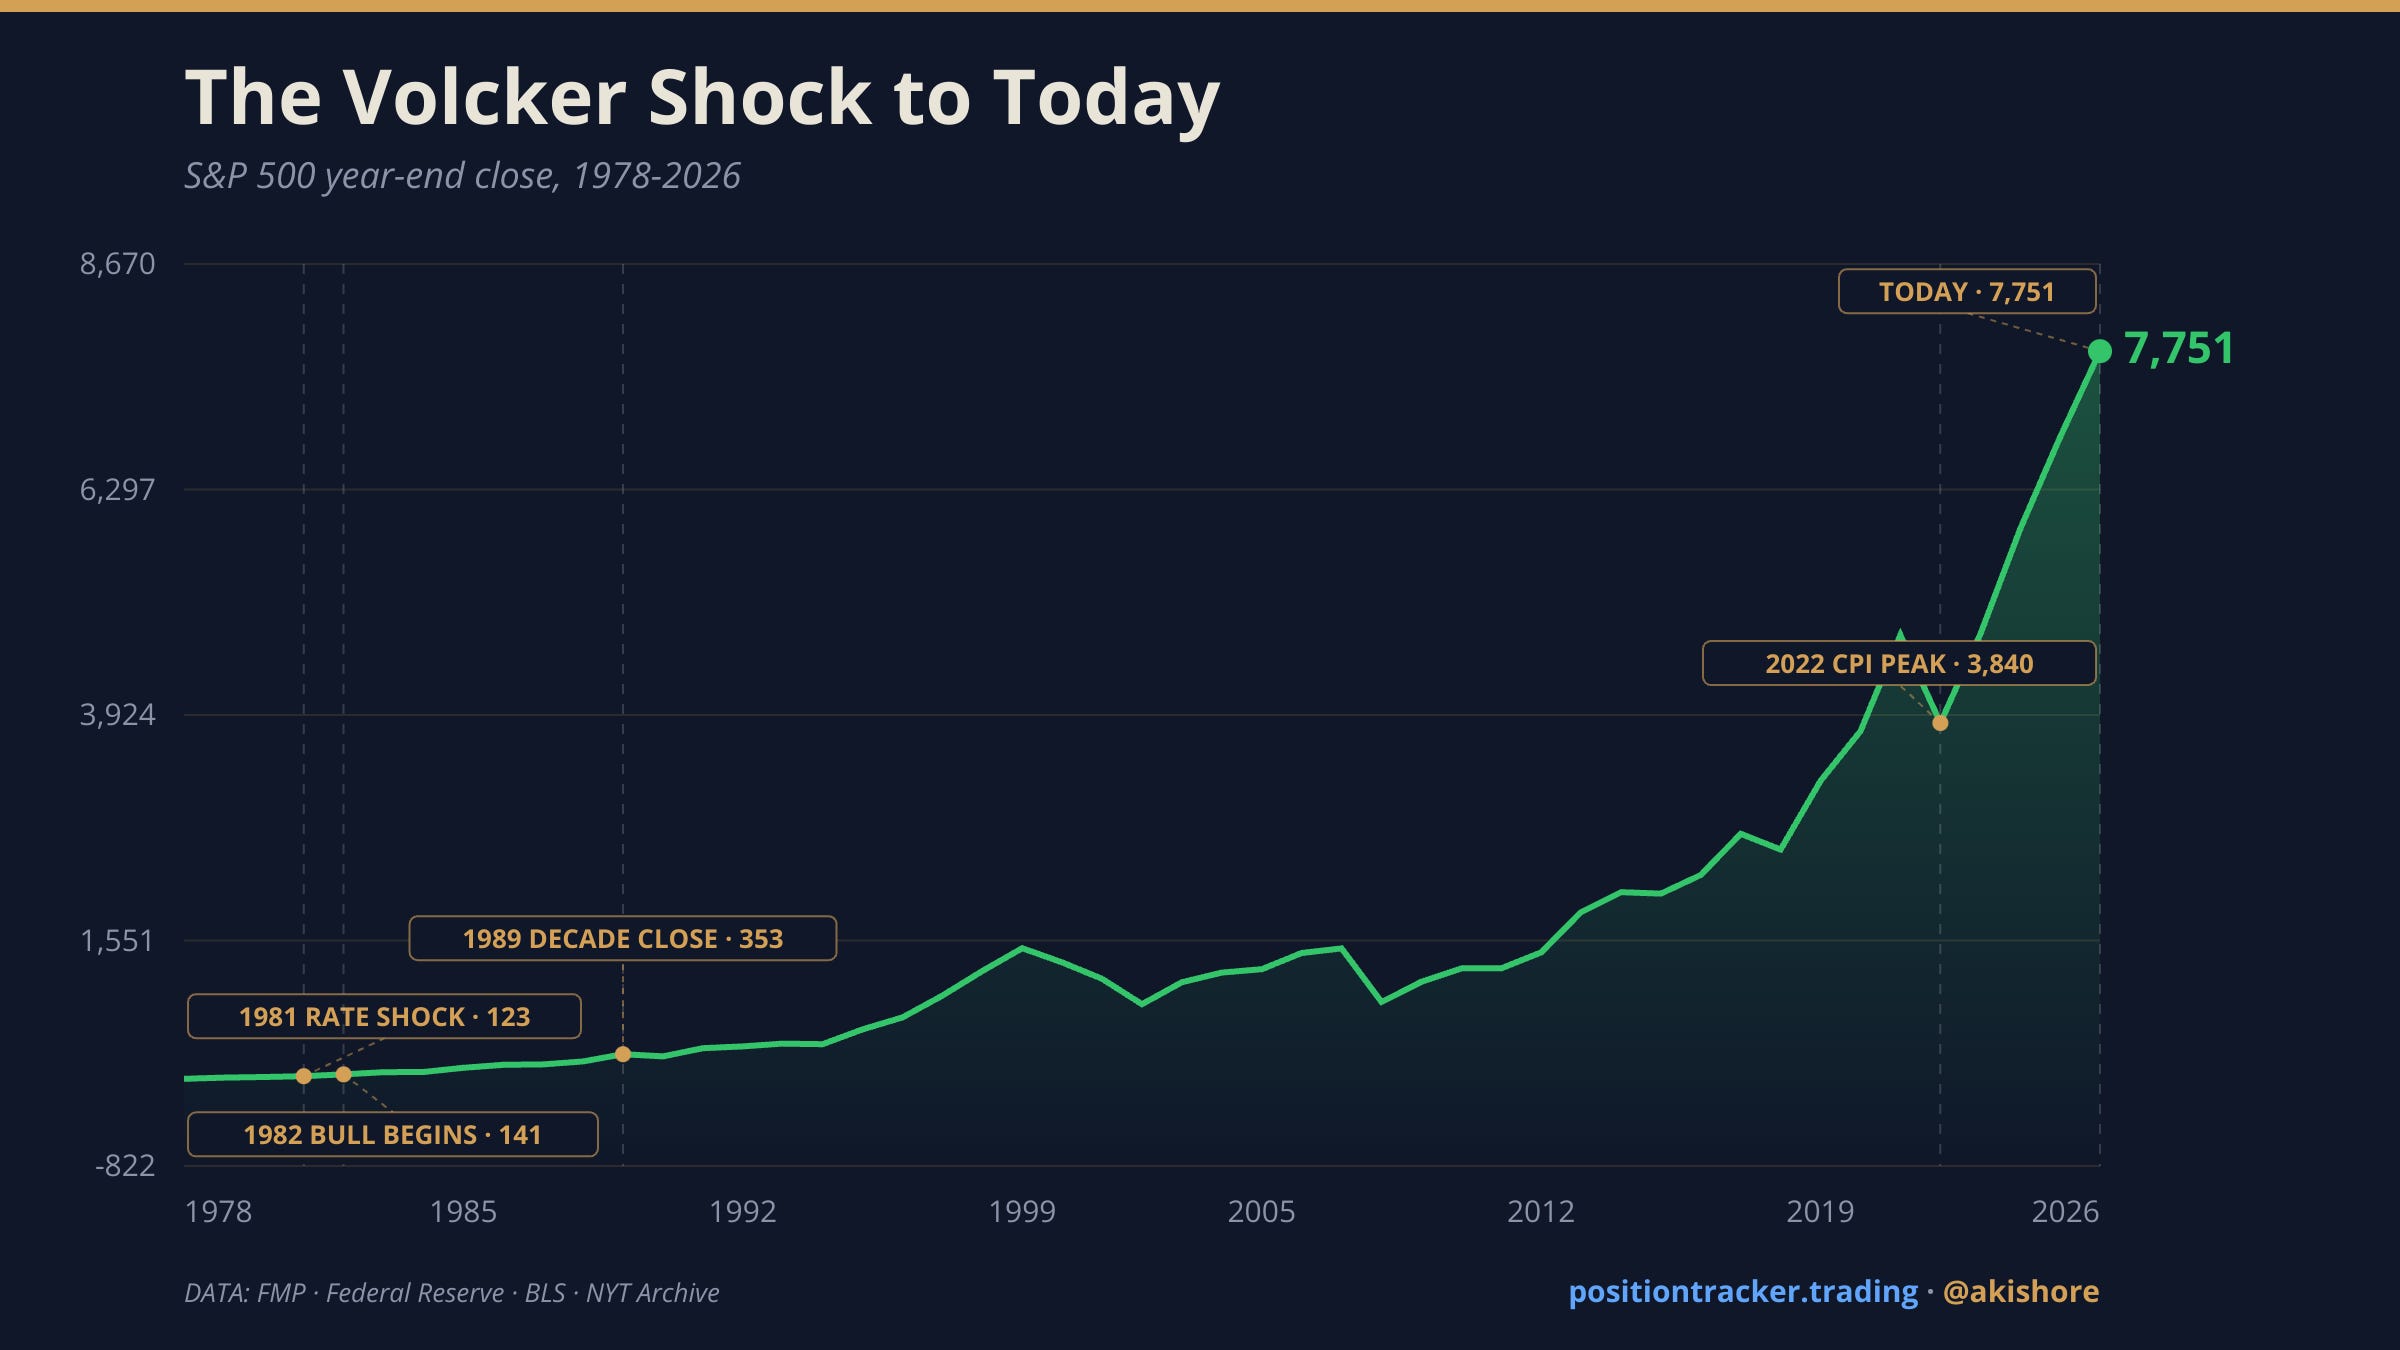
In June 1981, the Federal Reserve pushed the Fed Funds rate to 20% to break inflation running at 14.8%, the most aggressive tightening cycle in Fed history. The market absorbed the full cost of it. The S&P 500 bottomed at 102.42 on August…