Novo Nordisk ($NVO): buy in pieces $35 to $42, long term
$NVO: I think Novo Nordisk is a buy because the outlook just got raised and the multiple did not.
8% below its 200-day
About 11x trailing earnings vs a 5-year average near 30x
4.5% dividend yield
I'm buying in pieces between $35 and $42 to hold for years.
Not financial advice
The bear case is Eli Lilly and US pricing. Injectable Wegovy still loses share to Zepbound and Wegovy's US price eroded about 30% to 35% in Q3. Citi kept a neutral rating after the print citing pricing uncertainty and a fuzzy next act after Wegovy.
The chart: I read the fall from the $94 top on Feb 25 2025 as an A-B-C correction. A ended near $47 in July 2025, B bounced to $64 in January and C bottomed at $35.12 on March 30. The Oct 5 low of $36.85 held above it. Price is still under the 200-day near $44.
The business: Q3 sales were DKK 79.2B ($11.9B), up 4% at constant currency. Adjusted operating profit was DKK 31.7B and beat estimates. Wegovy pill sales hit DKK 5.4B and took about 80% of US new oral obesity starts. Management raised 2026 adjusted sales and operating profit growth to -2% to +2%.
My plan: I'm adding between $35 and $42 and holding for years. A weekly close below $34, under the March low, means I'm wrong. The stock trades near 7x EV/EBITDA versus a 5-year average near 22x. This is a multi-year hold, not a trade.
Sources: CNBC: Novo Q3 2026, Wegovy pill beat, outlook raised to -2% to +2% · Novo Nordisk Q3 2026 investor presentation · Fierce Pharma: Wegovy pill Q3 DKK 5.4B and launch plans · Cestrian: NVO Q3 figures, guidance raise and FCF guide DKK 60-70B · Motley Fool: Novo Nordisk Q3 2026 earnings call transcript · Yahoo Finance: Novo raises 2026 outlook after Q3
Not financial advice. For informational and educational purposes only.
Bank of England pays the inflation insurance premium
The Bank of England raised Bank Rate from 3.75% to 4% today on an 8–1 vote. Catherine L Mann wanted a larger increase to 4.25%. I keep coming back to that split because it shows how much judgment this decision…
$SNDK $MU settle scenarios Nov 5
$SNDK closed around $806 (−22%) and $MU around $658 (−17%). Base case: they settle in…
Meta beat revenue estimates but shares fell on spending and cash flow concerns, as Doctorow’s book examines the costs of platform growth.
Meta Platforms beat on revenue, and the stock still trades well below where it stood before the results. $META closed the latest session at $630.00, up 1.44%, and was indicated at $635.51 pre-market this morning, against a $697.52 close before the report. The shares fell about 7% in the session after results as investors focused on spending and cash flow.
Volcker Shock & the 1980s Bull — 20% Rates to 3.75%-4.00%
In June 1981, the Federal Reserve pushed the Fed Funds rate to 20% to break inflation running at 14.8%, the most aggressive tightening cycle in Fed…
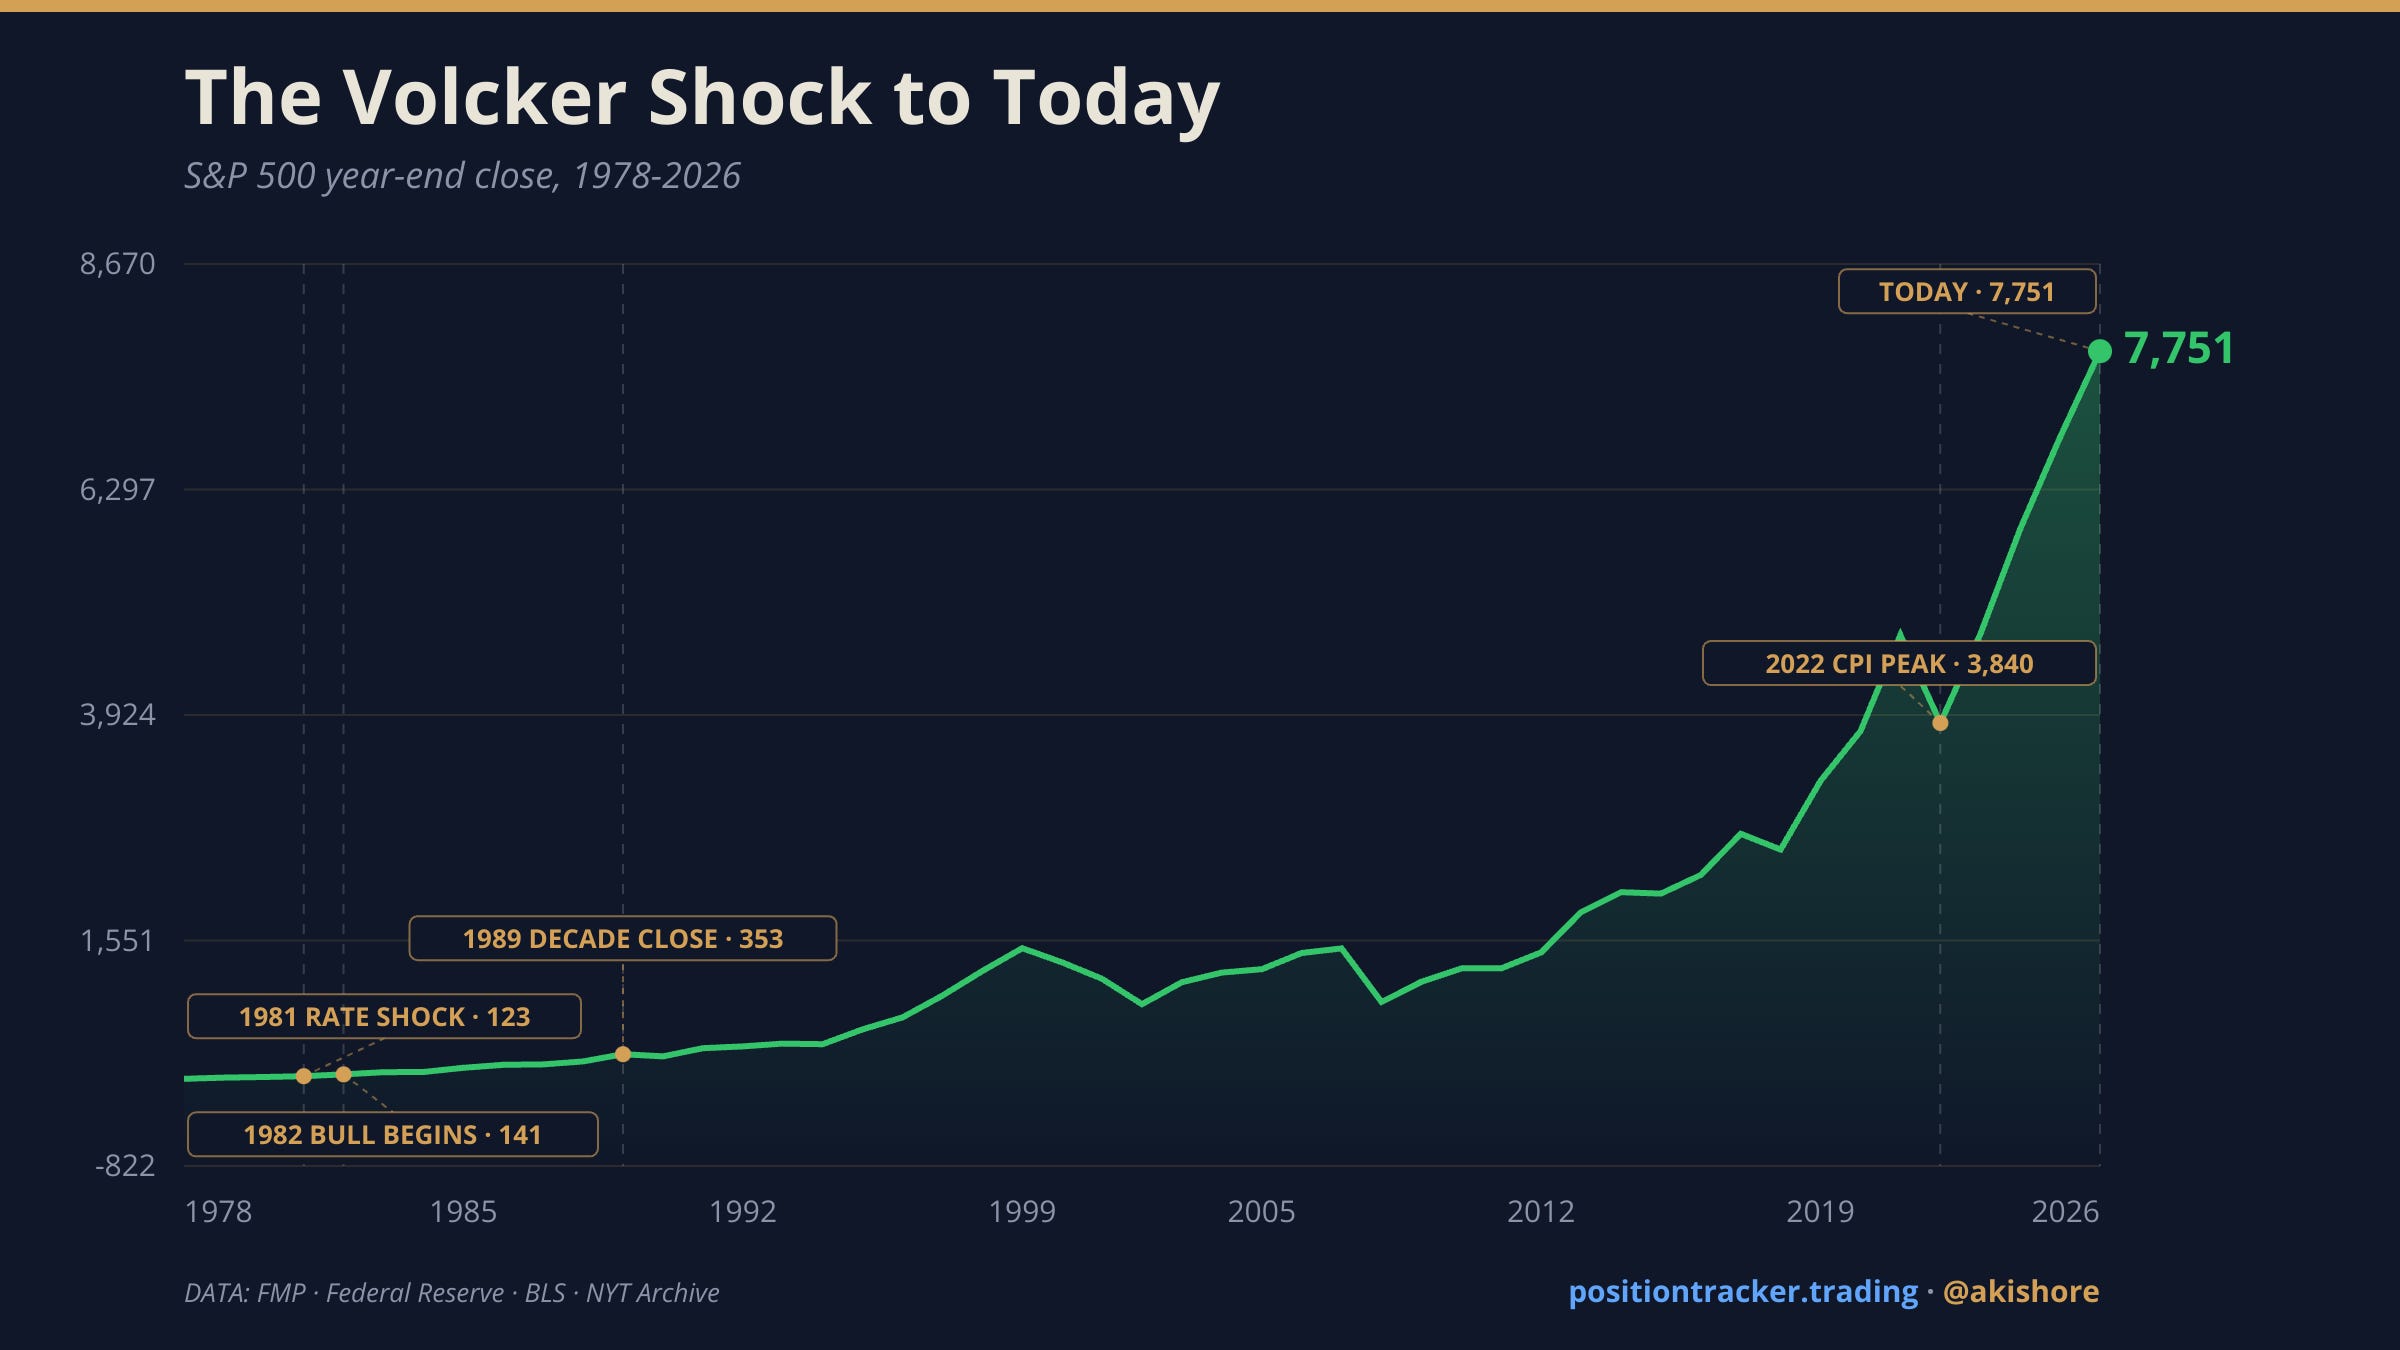
In June 1981, the Federal Reserve pushed the Fed Funds rate to 20% to break inflation running at 14.8%, the most aggressive tightening cycle in Fed history. The market absorbed the full cost of it. The S&P 500 bottomed at 102.42 on August…