$QCOM daily pick: sell Dec 18 $135 put (buy-side) after the 12% earnings drop
$QCOM: I'm selling the Dec 18 $135 put on @Qualcomm after an 11.7% drop on its earnings report.
Live at 12:17pm ET ($153.02):
10% under the 200-day
About 15x fiscal 2027 EPS estimates
$4.30 credit, breakeven $130.70
About 3.2% in 43 days (~27% annualized)
I think the selloff is overdone because the weak spot is phones squeezed by memory costs while automotive revenue grew 89% to a record $1.99B.
Not financial advice
What happened: adjusted EPS of $2.17 beat by a penny, but handset revenue fell 26% to $5.14B and the first quarter EPS guide of $2.15 to $2.35 has a midpoint below estimates. Rising memory prices are pushing phone prices up and demand down.
Why a put and not the stock: implied volatility is about 58% after the drop, so the premium is rich. The $135 strike is under the August low of $142.89 and 11.8% below the current price. If I get assigned I own Qualcomm at $130.70 net, about 15% under today's price.
The risk: if the handset market keeps shrinking and the stock goes back to the April low of $121.99, I own shares at a loss. A smaller version is the Dec 18 135/125 put spread for $1.74, which caps the risk at $826.
What I'd watch: Qualcomm guided data center revenue above $650M this quarter and kept its $5B target for fiscal 2027. The Dec 18 expiry comes before the next report (FMP lists Feb 3), so earnings are not inside this trade. The $0.92 quarterly dividend works out to about 2.4% a year at this price.
Sources: CNBC: Qualcomm sinks after earnings, handsets -26%, light guide · CNBC: Qualcomm Q4 2026 results, EPS $2.17 vs $2.16, Q1 guide · Reuters via Investing.com: handset revenue -26% to $5.14B · Quartz: auto +89% to record $1.99B, $5B FY27 data center target · Converge Digest: $650M+ Q1 data center, $5B FY27, auto $1.99B · The Verge: ~$650M Q1 data center revenue, $5B by end of FY27
Not financial advice. For informational and educational purposes only.
OpenAI president Brockman says company could be IPO ready in 2027
OpenAI co-founder and president Greg Brockman said at a Wall Street Journal tech conference on…
Quote post: @KobeissiLetter on the VIX rebound (from 16.61 yesterday to ~25.8, up more than 50%)
$VIX closed at 16.61 yesterday. It's already back near 23.7, up about 43% on the day after a brief spike higher.…
Volcker Shock & the 1980s Bull — 20% Rates to 3.75%-4.00%
In June 1981, the Federal Reserve pushed the Fed Funds rate to 20% to break inflation running at 14.8%, the most aggressive tightening cycle in Fed…
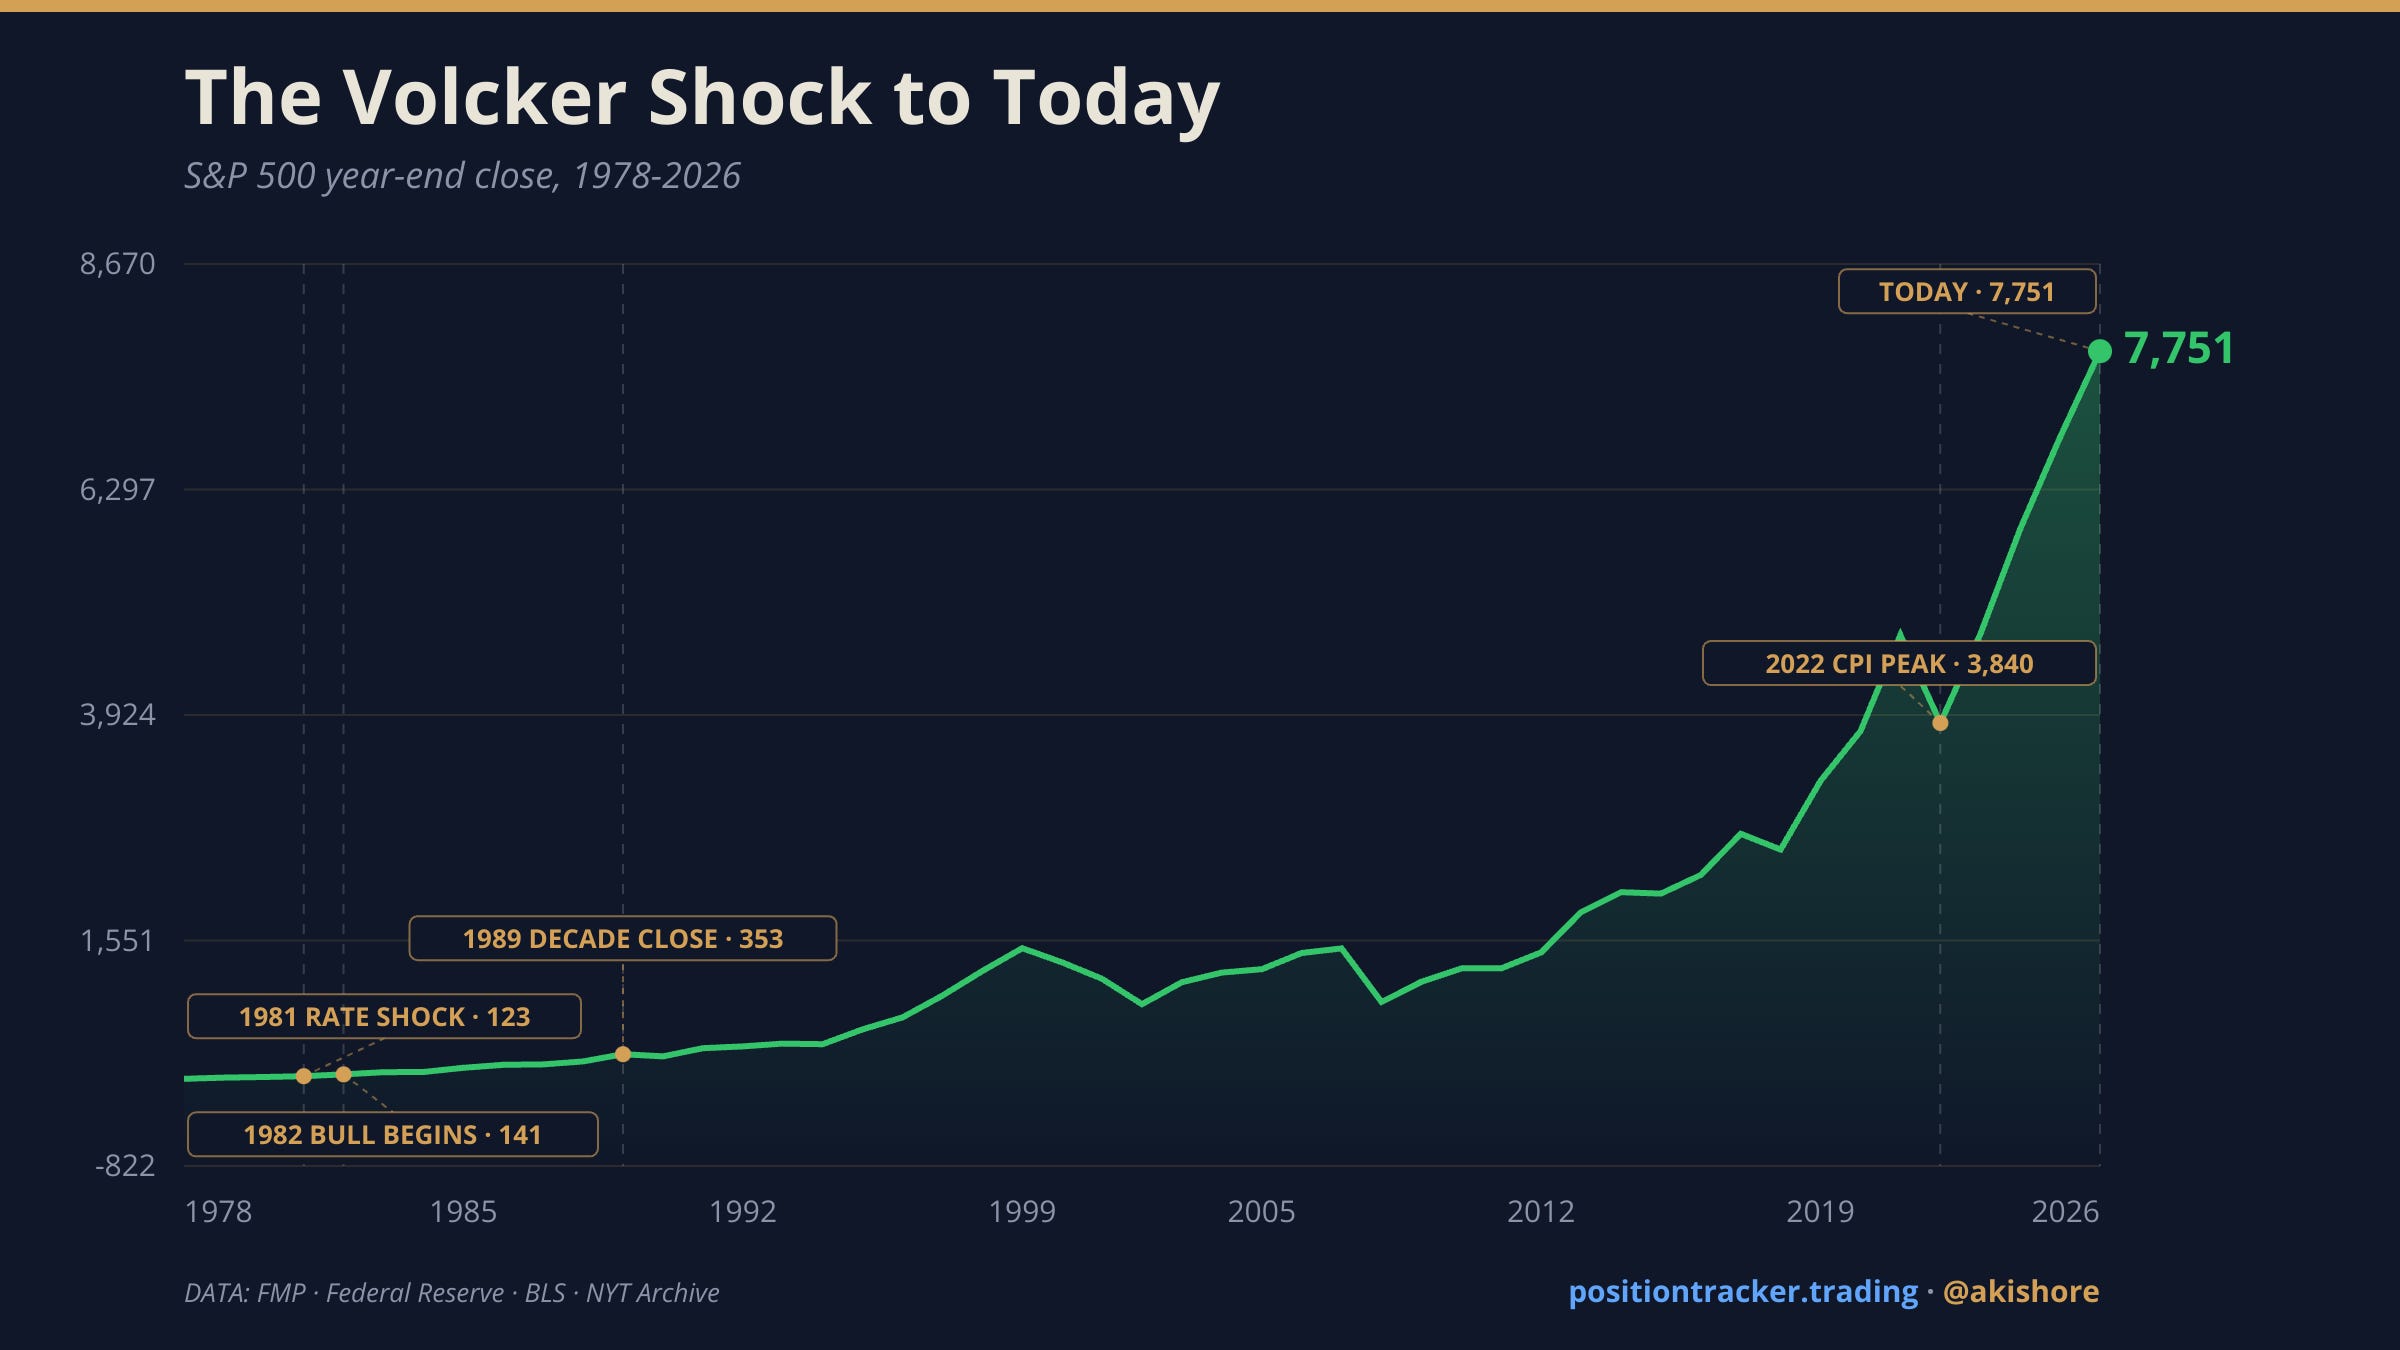
In June 1981, the Federal Reserve pushed the Fed Funds rate to 20% to break inflation running at 14.8%, the most aggressive tightening cycle in Fed history. The market absorbed the full cost of it. The S&P 500 bottomed at 102.42 on August…
Afternoon update
$LITE fell 16.57% and Marvell 10.68% this afternoon as investor skepticism grew over Marvell's $115B all-stock acquisition of Lumentum. • Lumentum…
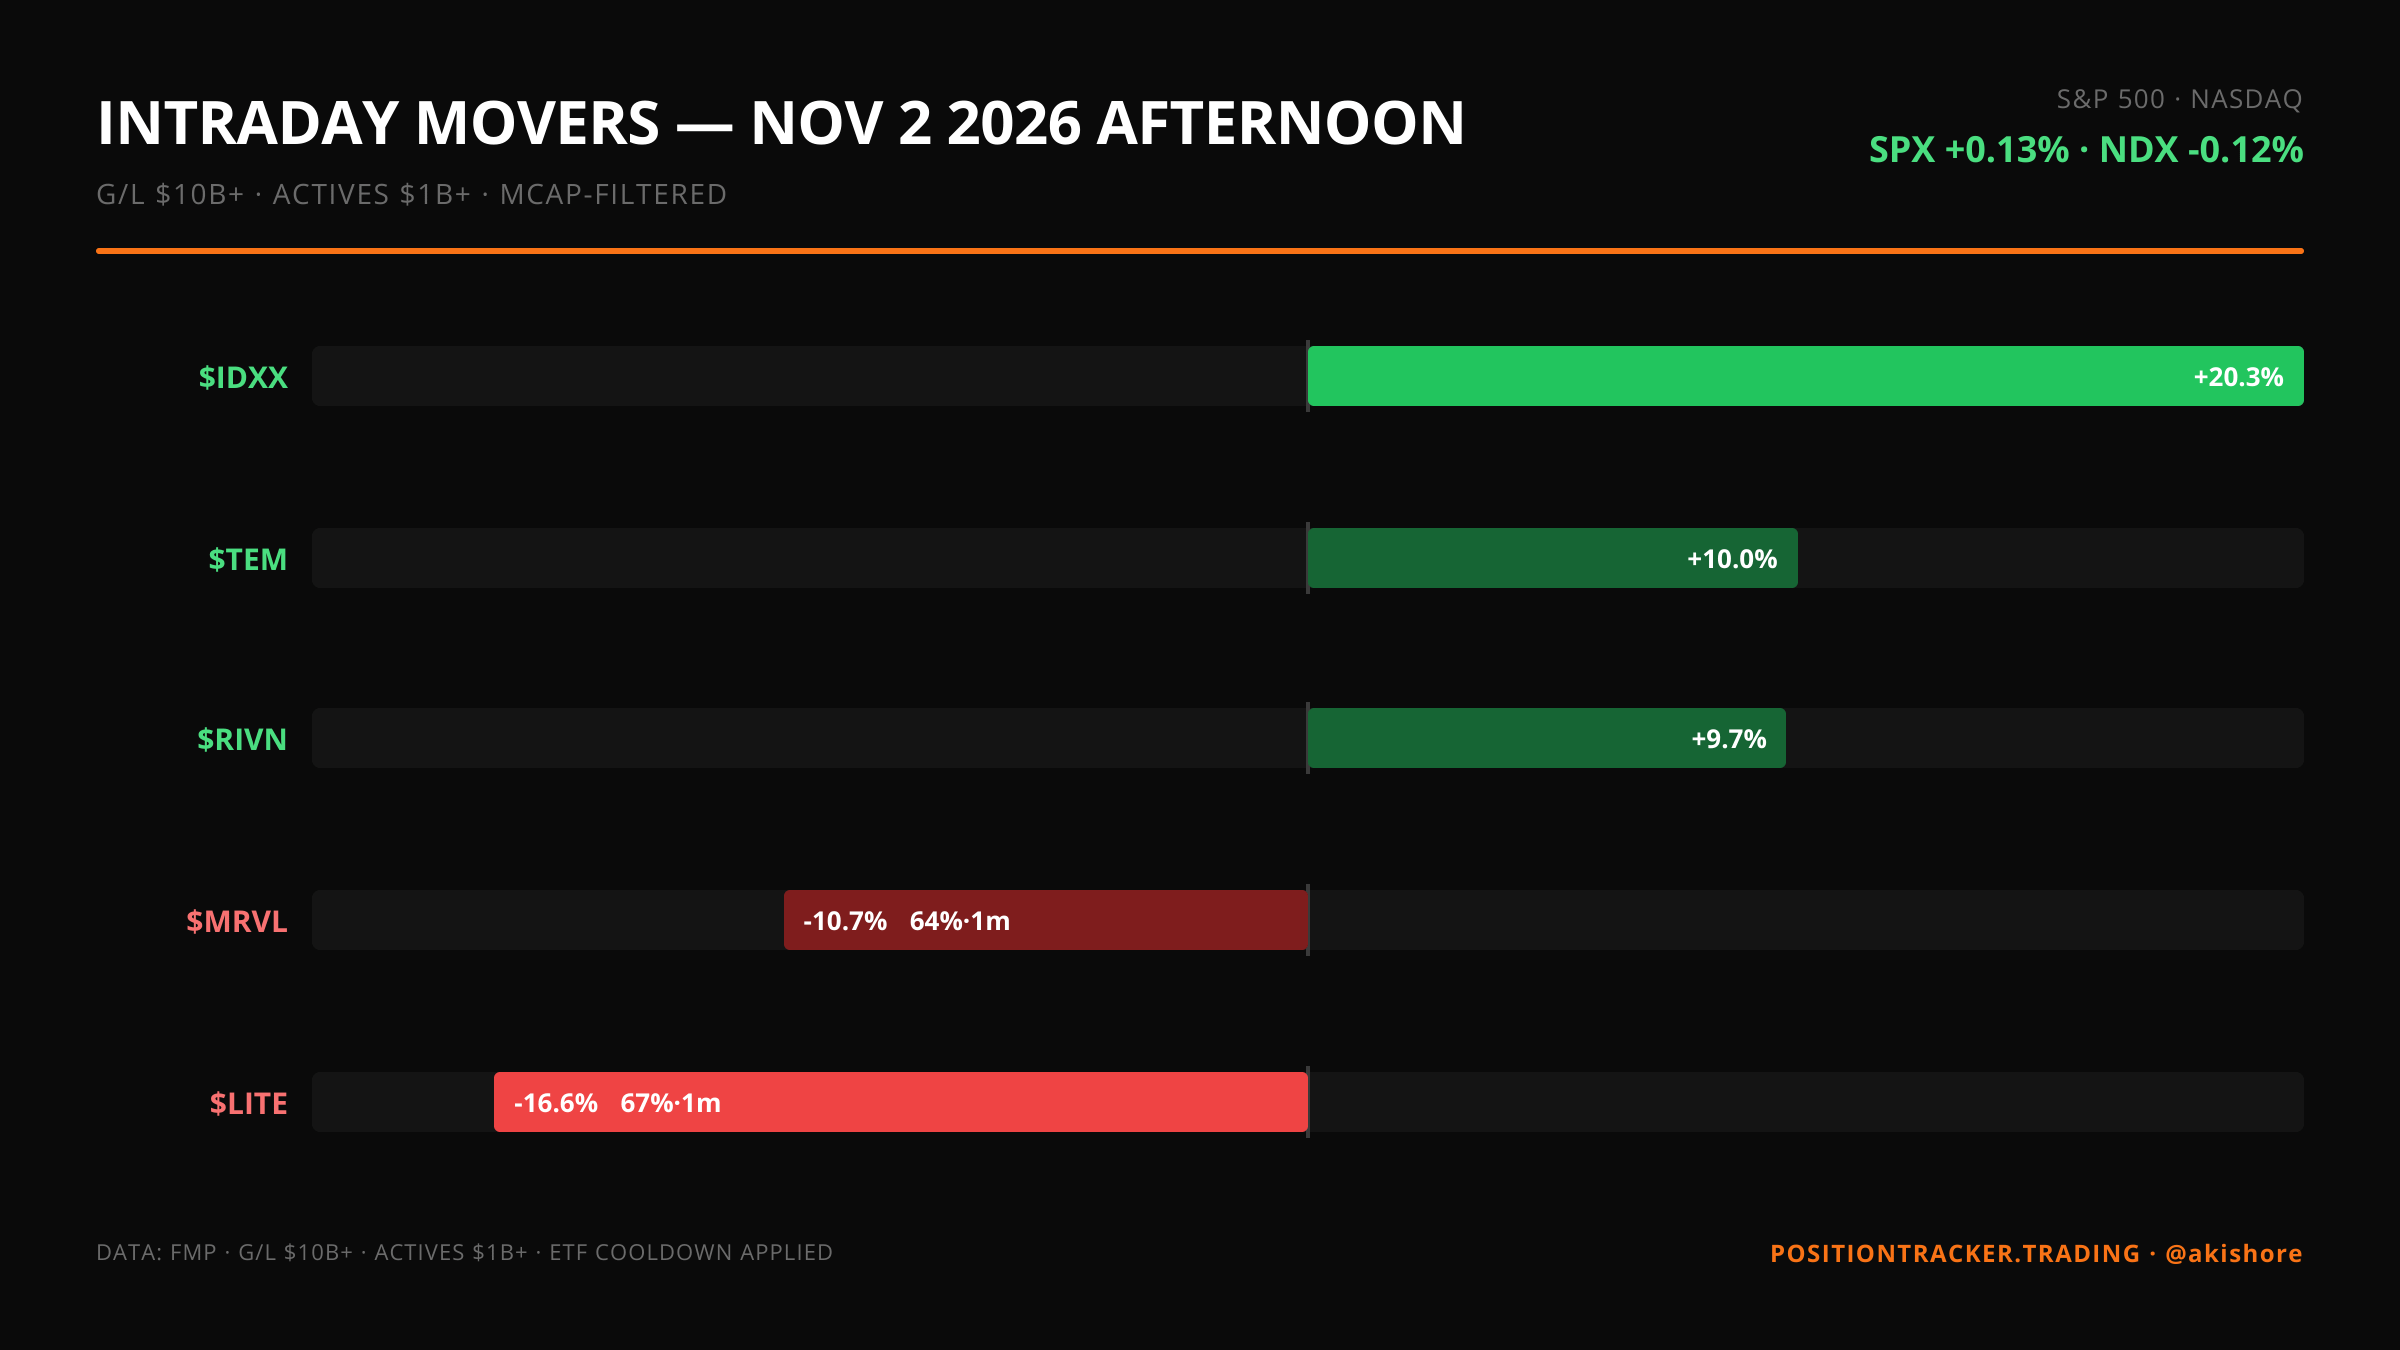
$LITE fell 16.57% and Marvell 10.68% this afternoon as investor skepticism grew over Marvell's $115B all-stock acquisition of Lumentum. Lumentum closed at $701.43 ($62.9B market cap). The deal, valued at $115B by enterprise value, gives Marvell shareholders 67% of the combined…