$ROST is down 5.37% after hours at $208.06, after already closing down 3.41%.
$ROST is down 5.37% after hours at $208.06, after already closing down 3.41%. That looks like a fair reaction to me. The Q3 numbers were strong, and the FY26 raise gets a lot of its size from a tariff refund.
- Q3 sales rose 12% to $6.256B on 8% comps, and traffic drove those comps. Operating margin was 12.3%, up 70 bps. EPS came in at $1.91, above Ross's own $1.75-$1.83 plan.
- Holiday comps are guided to 4%-5%, against a 9% gain in last year's Q4. Q4 EPS guidance is $2.16-$2.25, and Reuters reports that range is one cent lower at both ends than before.
- FY26 EPS guidance went up to $8.75-$8.84, but it includes about $0.60/share from $253M in IEEPA tariff refunds booked in Q2. My own math takes that out and gets closer to $8.15-$8.24.
- Ross opened 51 stores in Q3, which finishes its 115-store plan. It also bought back $319M of stock and is on track for $1.275B in buybacks this year.
I'm still worried about tariffs and inflation. I'd change my mind if refunds like this kept showing up as real, repeatable money, but a one-time refund doesn't count. For me, holiday traffic against that 9% comparison is what decides whether this drop turns into a cash-secured put setup.
Sources:
https://www.sec.gov/Archives/edgar/data/745732/000074573226000047/q326exhibit991.htm
https://www.barrons.com/articles/ross-stores-earnings-stock-price-6d303547
Not financial advice. For informational and educational purposes only.
Anthropic slipped another 1.13% after-hours to $88.30.
Anthropic slipped another 1.13% after-hours to $88.30. In Friday's regular session, shares touched $83.05, nearly their $83 IPO price and 14.53% below the previous close. They recovered to close at $89.305, down 8.09%…
Citi shares touched $110.175 in the regular session, 4.43% below the previous close, and finished at $110.72, down 3.96%.
Citi shares touched $110.175 in the regular session, 4.43% below the previous close, and finished at $110.72, down 3.96%. They traded at $110.99 after hours, up 0.24% from that close. Reuters reported that incorrectly recorded trades at Citi's UK trading subsidiary led to an understatement of about…
The one number that actually matters in HSBC's Nov.
The one number that actually matters in HSBC's Nov. 20 upgrade of $TSLA is $212. Everything above that in the bank's $359 price target rests on a hypothetical SpaceX deal that has no formal terms on the table. HSBC analyst…
Afternoon update
Global Payments rose 10.51% on reported GTCR takeover interest as semiconductor weakness weighed on the broader market.
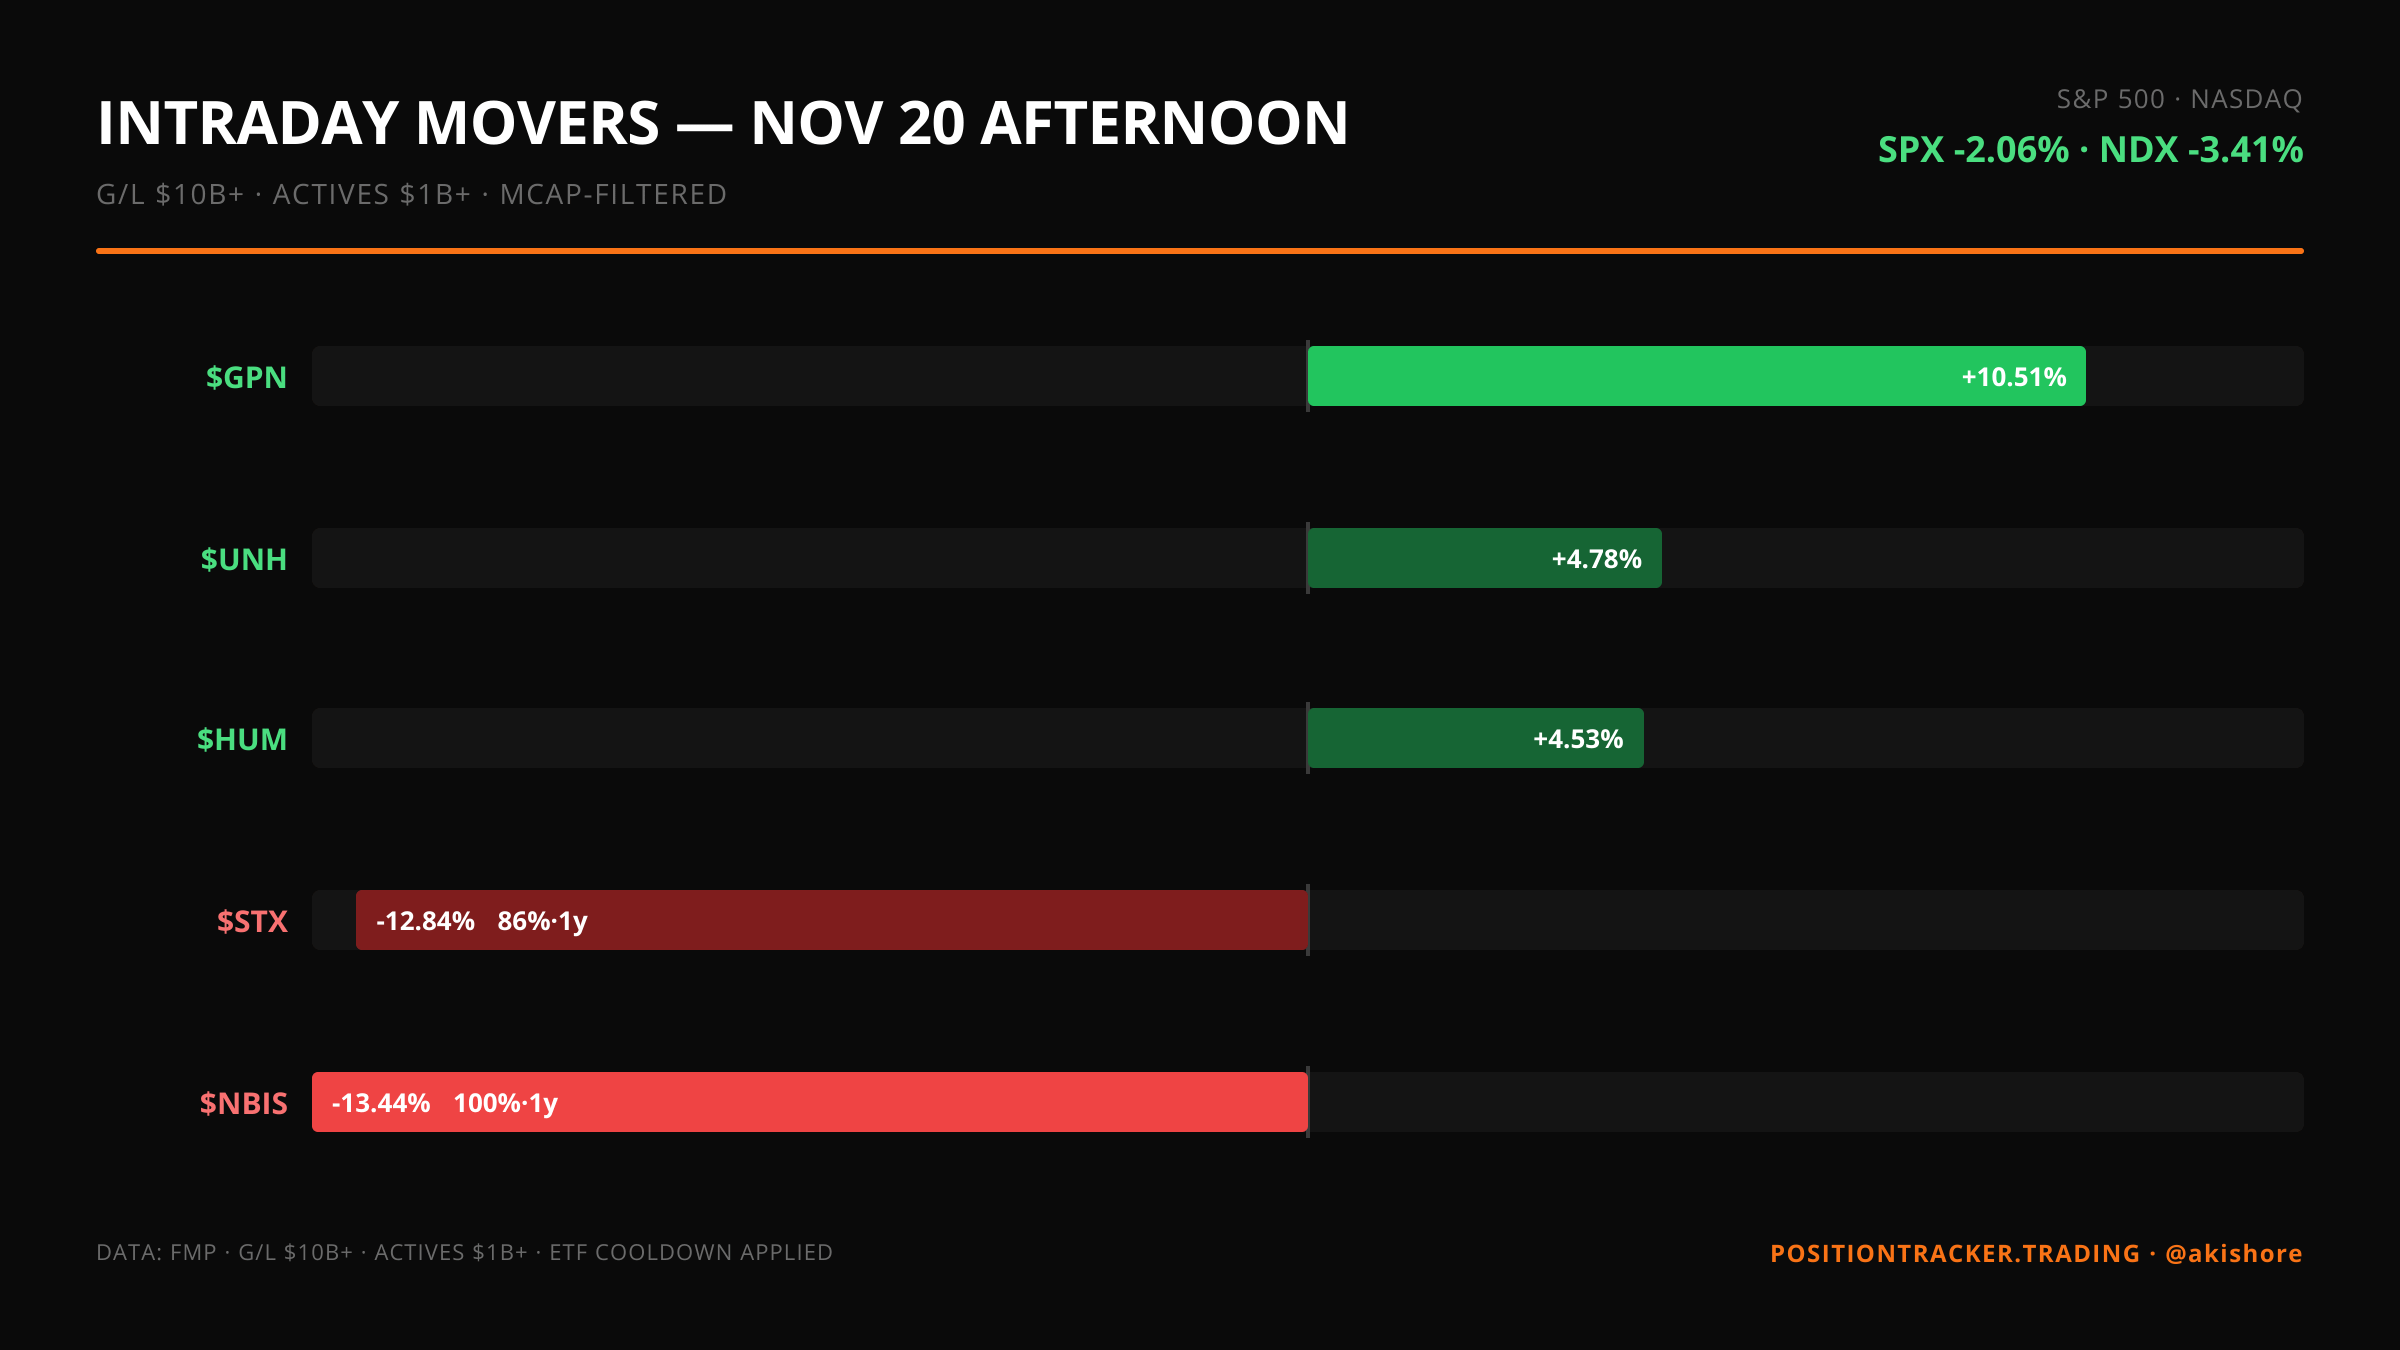
$GPN rose 10.51% on November 20 after a report that GTCR is considering a $50B takeover bid. The Nasdaq fell 3.41% in the afternoon session. Global Payments gained 10.51% at a $24.4B market cap. Shares jumped on the reported GTCR interest; the bid remains a report, not a confirmed…