S&P putting Meta on negative outlook tells me the credit desks now treat AI capex as a balance-sheet question.
S&P putting Meta on negative outlook tells me the credit desks now treat AI capex as a balance-sheet question. My lean is still that the big names adapt, but this is the kind of pressure that could change my mind.
- On Oct 30, S&P Global Ratings revised Meta's outlook from stable to negative and affirmed its existing ratings. That's a warning shot from the agency, with the rating itself unchanged.
- S&P cited uncertainty over how long elevated capex lasts and negative free operating cash flow. Its own forecasts project deficits of $22B in 2026, $71B in 2027 and $39B in 2028.
- Meta's reported 2026 capex guide is $135-145B, and S&P flagged a $2.1B free operating cash flow deficit in Q3 despite revenue growth. Delayed AI monetization could stretch the pressure out, per S&P.
- $META closed at $614.99, down 1.53%, during a broad tech selloff, and sat at $613.25 after hours. A modest move for now.
What flips me: if those projected deficits start showing up as real numbers instead of forecasts, or Moody's and Fitch follow and Meta's next debt gets priced wider. Until then I see a giant that can carry the bill, though I could be early on that.
Sources:
Reuters: https://www.reuters.com/business/sp-global-revises-outlook-meta-negative-cashflow-concerns-2026-10-30/
CNBC: https://www.cnbc.com/2026/10/30/meta-outlook-to-revised-to-negative-by-sp-after-cash-flow-negative.html
Investing.com: https://www.investing.com/news/stock-market-news/sp-global-cuts-meta-outlook-to-negative-amid-capex-concerns-4988733
Not financial advice. For informational and educational purposes only.
Quote post: @Cointelegraph on Apple passing Nvidia as the most valuable company
Apple is the world's most valuable company again, about $90 billion ahead of Nvidia after Nvidia fell around 4% today. I think…
BB. Per the FT, that's the rating Blackstone now expects for Anthropic after its IPO.
BB. Per the FT, that's the rating Blackstone now expects for Anthropic after its IPO. To me it's the most honest number in this whole listing story. The FT reports that Blackstone told investors in Anthropic's chip-financing deal that a high speculative-grade rating, around BB, is…
End-of-day recap
Disappointing tech earnings drove a rotation out of AI-trade stocks, while healthcare and select consumer names posted double-digit gains on strong results.
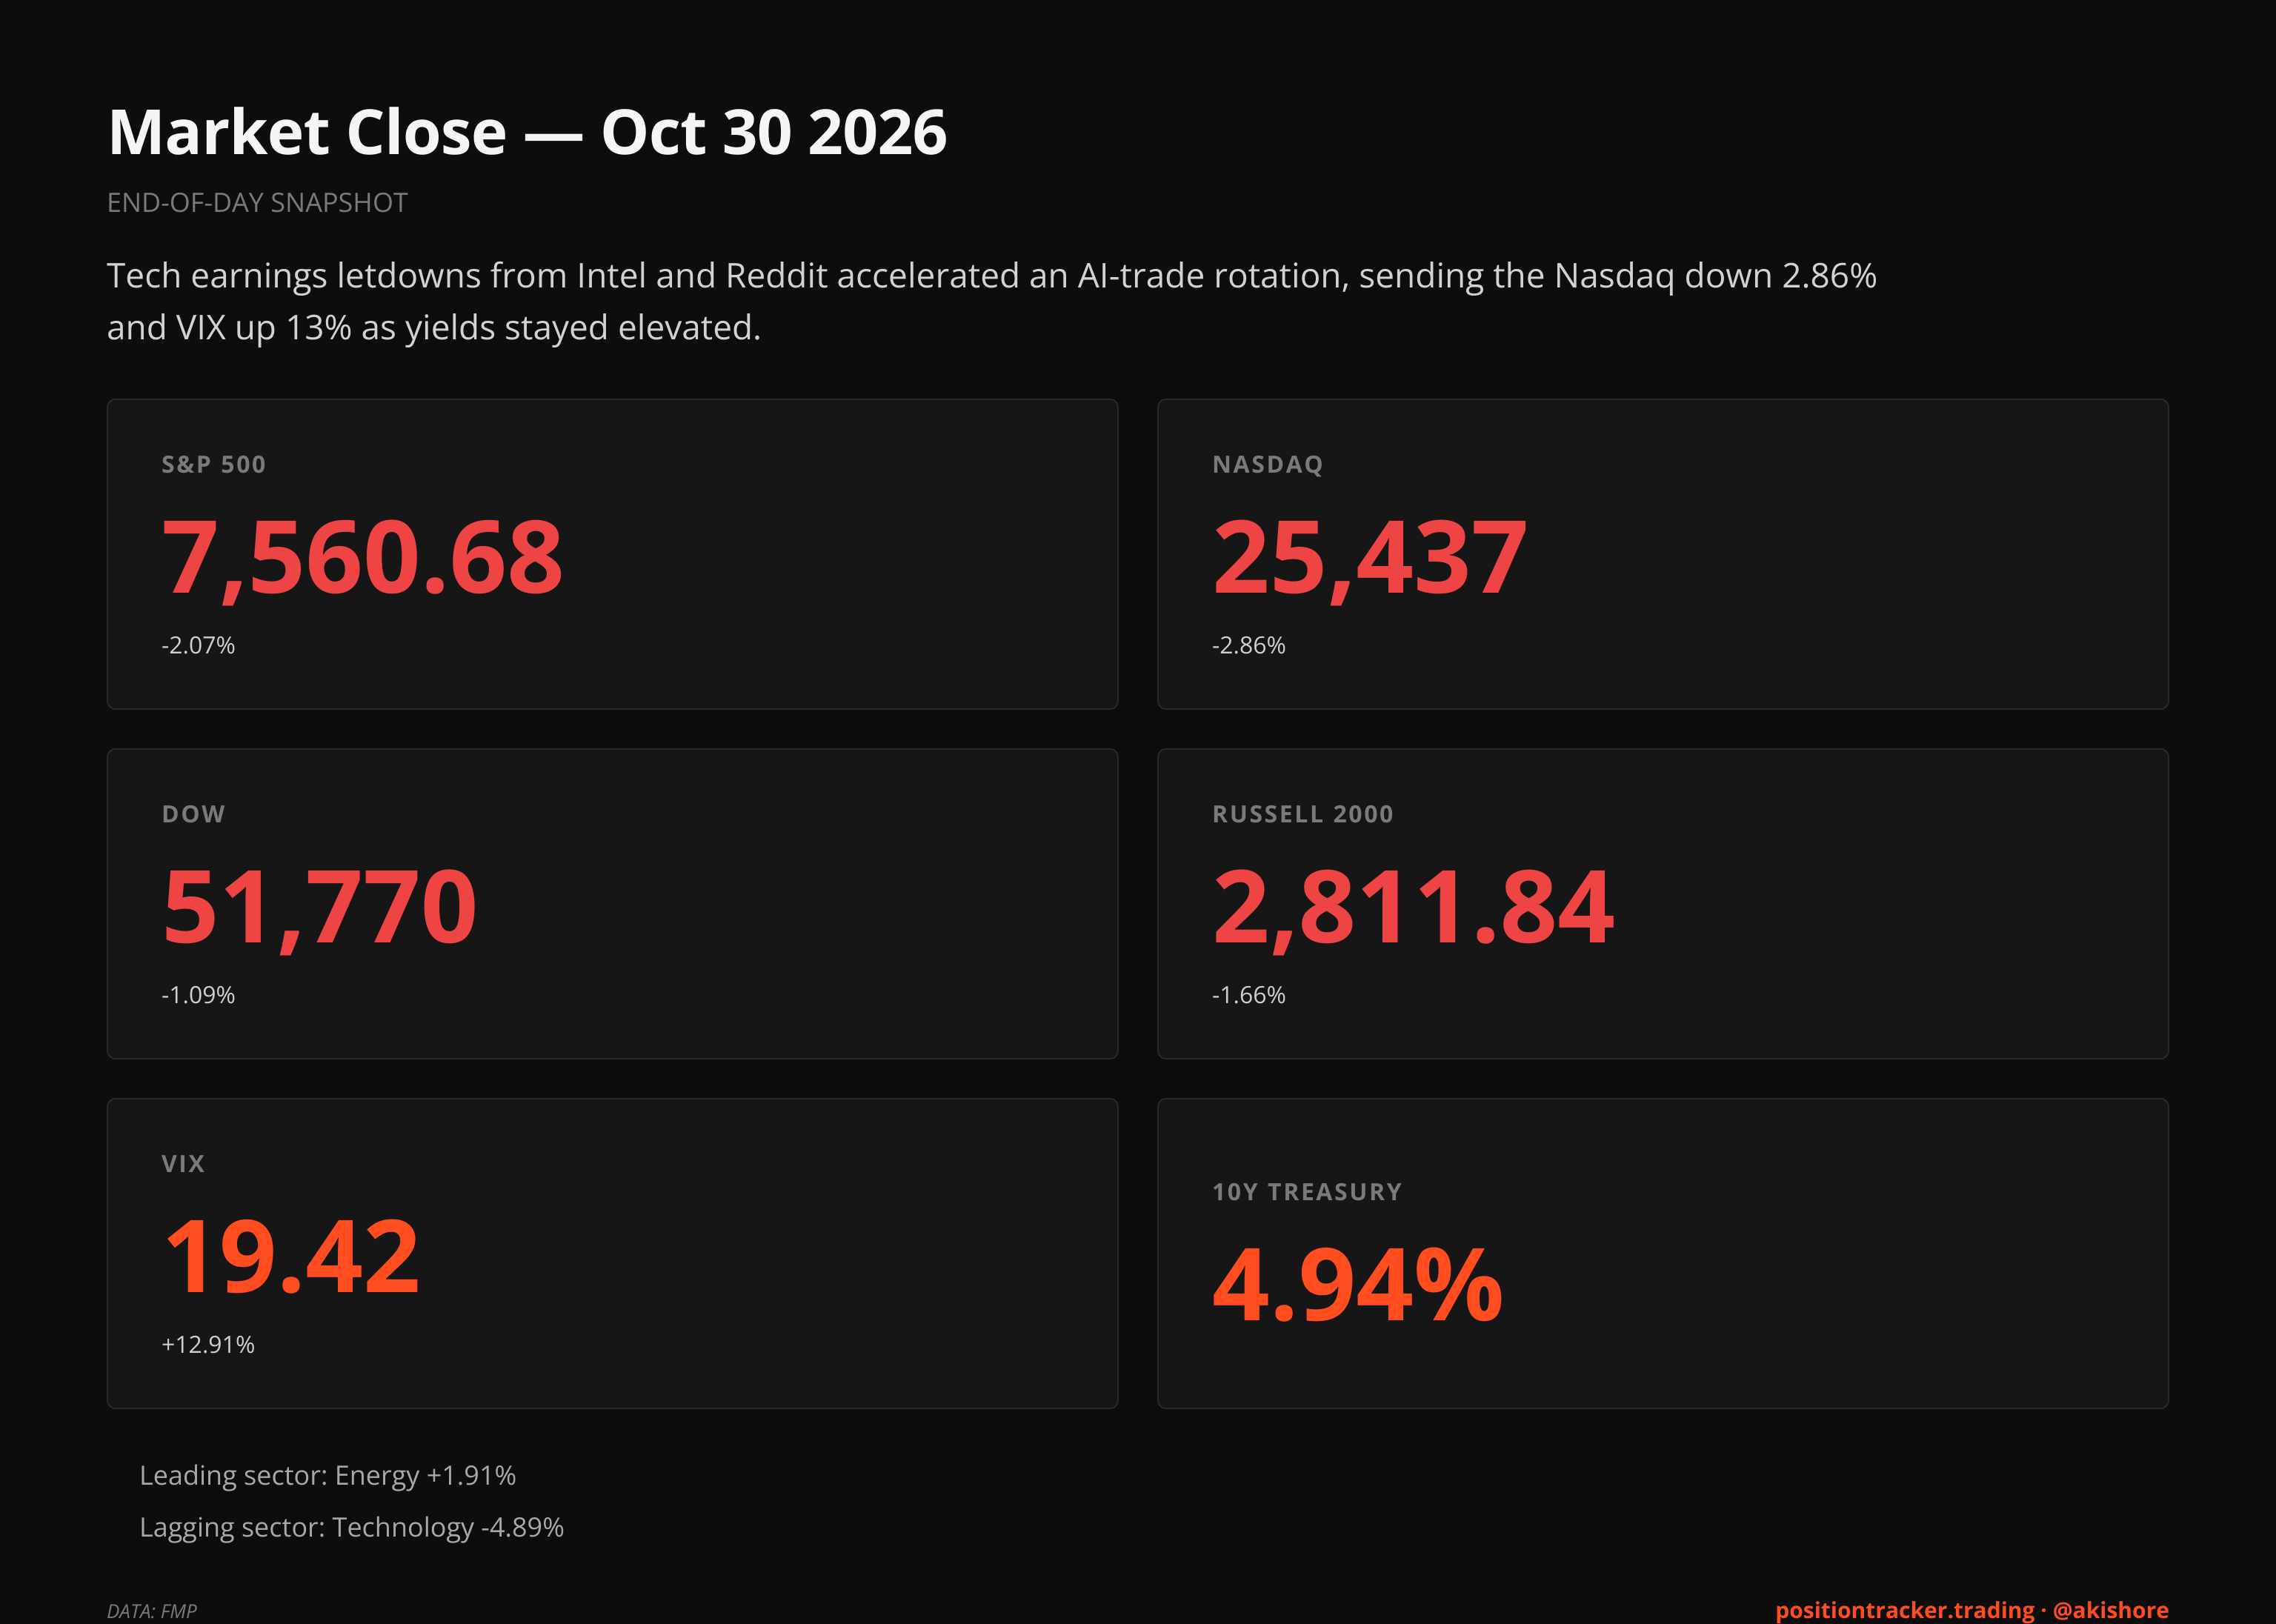
Disappointing tech earnings accelerated a rotation out of AI-trade stocks on Oct 30, 2026, while healthcare and select consumer names posted double-digit gains on strong results. The S&P 500 fell 2.07% to 7,560.68 and the Nasdaq dropped 2.86% to 25,436.99. The Dow lost 1.09%, the Russell 2000 slid 1.66%, the VIX rose 12.91% to 19.42 and the 10-year yield sat…
Japan's Lost Decades — 34 Years to Break Even, Then 63% More
On December 29, 1989, the Nikkei 225 closed at 38,916, the peak of Japan's bubble economy.
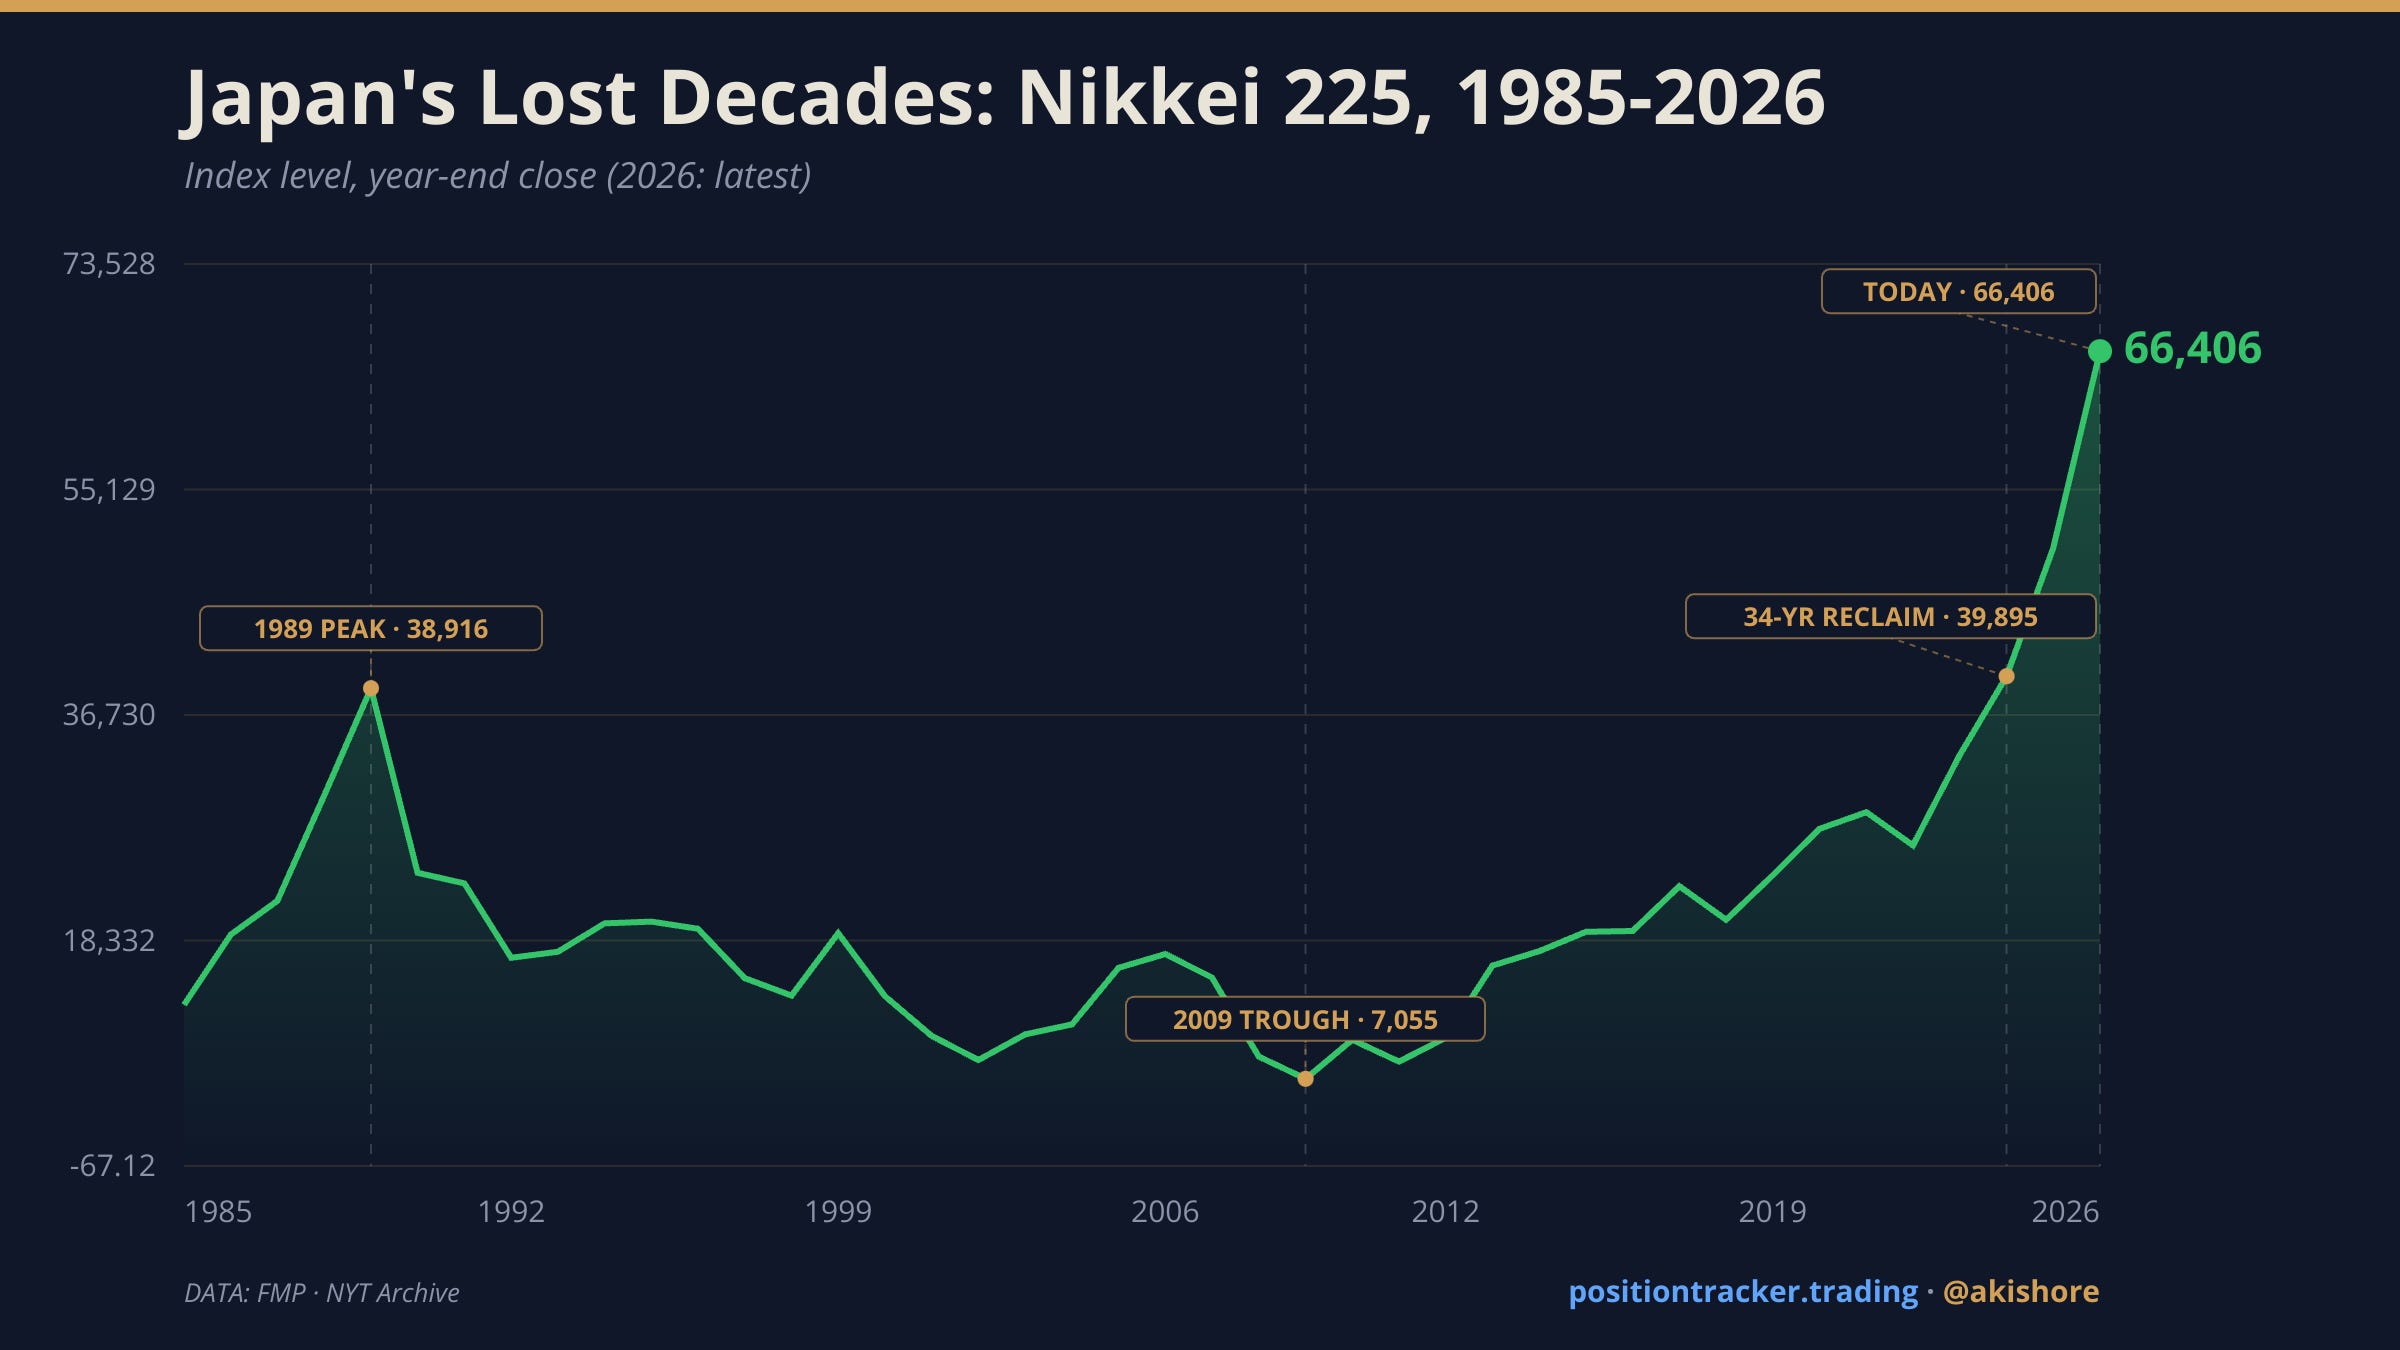
On December 29, 1989, the Nikkei 225 closed at 38,916, the peak of Japan's bubble economy. Cheap credit and a surging yen had pushed Tokyo real estate and equities to levels that made Japan alone worth roughly 45% of world equity market value that year, a level of single-country…