The number I care about in Anthropic's amended S-1 is 47%.
The number I care about in Anthropic's amended S-1 is 47%. That's quarter-over-quarter revenue growth in Q3, down from 132% in Q1 and 144% in Q2, and it's the figure the IPO valuation will get anchored to.
- Q3 revenue came in at $16.956B, up 1,127% year over year and up from $11.555B in Q2. That's still extraordinary growth, but the sequential pace fell by about two-thirds in a single quarter.
- Operating loss was $567M. The $23.29B Q3 net loss, and the $104B nine-month loss, are mostly fair-value changes on convertible notes and derivative liabilities, so I'd judge the operations on the smaller number.
- The filing lists about $895.4B in purchase commitments and leases, almost all compute and infrastructure. About $213.8B of that carries termination rights or conditions, which leaves a lot of fixed spend for revenue to grow into.
- The amendment, filed Nov. 2, adds Q3 to an S-1 that previously covered only the first half. The roadshow hasn't started, so pricing is still ahead.
I still lean toward Anthropic surviving as a front-runner. I also still expect lab valuations to run ahead of what the growth curve supports at IPO. If sequential growth holds near 47% into the roadshow, I could be wrong on that second point. If it keeps sliding, how do you price the $895B against it?
Sources:
CNBC: https://www.cnbc.com/2026/11/02/anthropic-ant-s-1-quarter-financials.html
Fortune: https://fortune.com/2026/11/02/anthropics-growth-slowed-and-costs-jumped-in-the-third-quarter-updated-ipo-filing-shows/
Axios: https://www.axios.com/2026/11/02/anthropic-spending-revenue-surge
Not financial advice. For informational and educational purposes only.
$AMZN daily pick: sell Dec 18 $220 put (buy-side) after the Q3 miss
$AMZN: I'm selling the Dec 18 $220 put on @amazon after the earnings miss and getting paid to wait. As of Friday's close ($240.35, markets closed for the weekend): Opened down 4.6% and closed down just 1.4% Credit $3.80 for about 1.7% in 47 days (~13% annualized) Breakeven $216.20, 10% below Friday About 22x 2027 EPS estimates
$ORCL daily pick: sell Dec 4 $105 put (buy-side) after the $20B raise selloff
$ORCL: I'm selling the Dec 4 $105 put on @Oracle after today's 6% drop on the $20B stock and bond sale. Live at 12:14pm ET ($122.59, down 6.2%): 22% under the 200-day Credit $2.06 for about 2% in 32 days (~22% annualized) Breakeven $102.94, 16% below today About 15x fiscal 2027 EPS estimates
Midday update
$IDXX is up 17.29% at midday after a Q3 beat and raised FY2026 guidance.
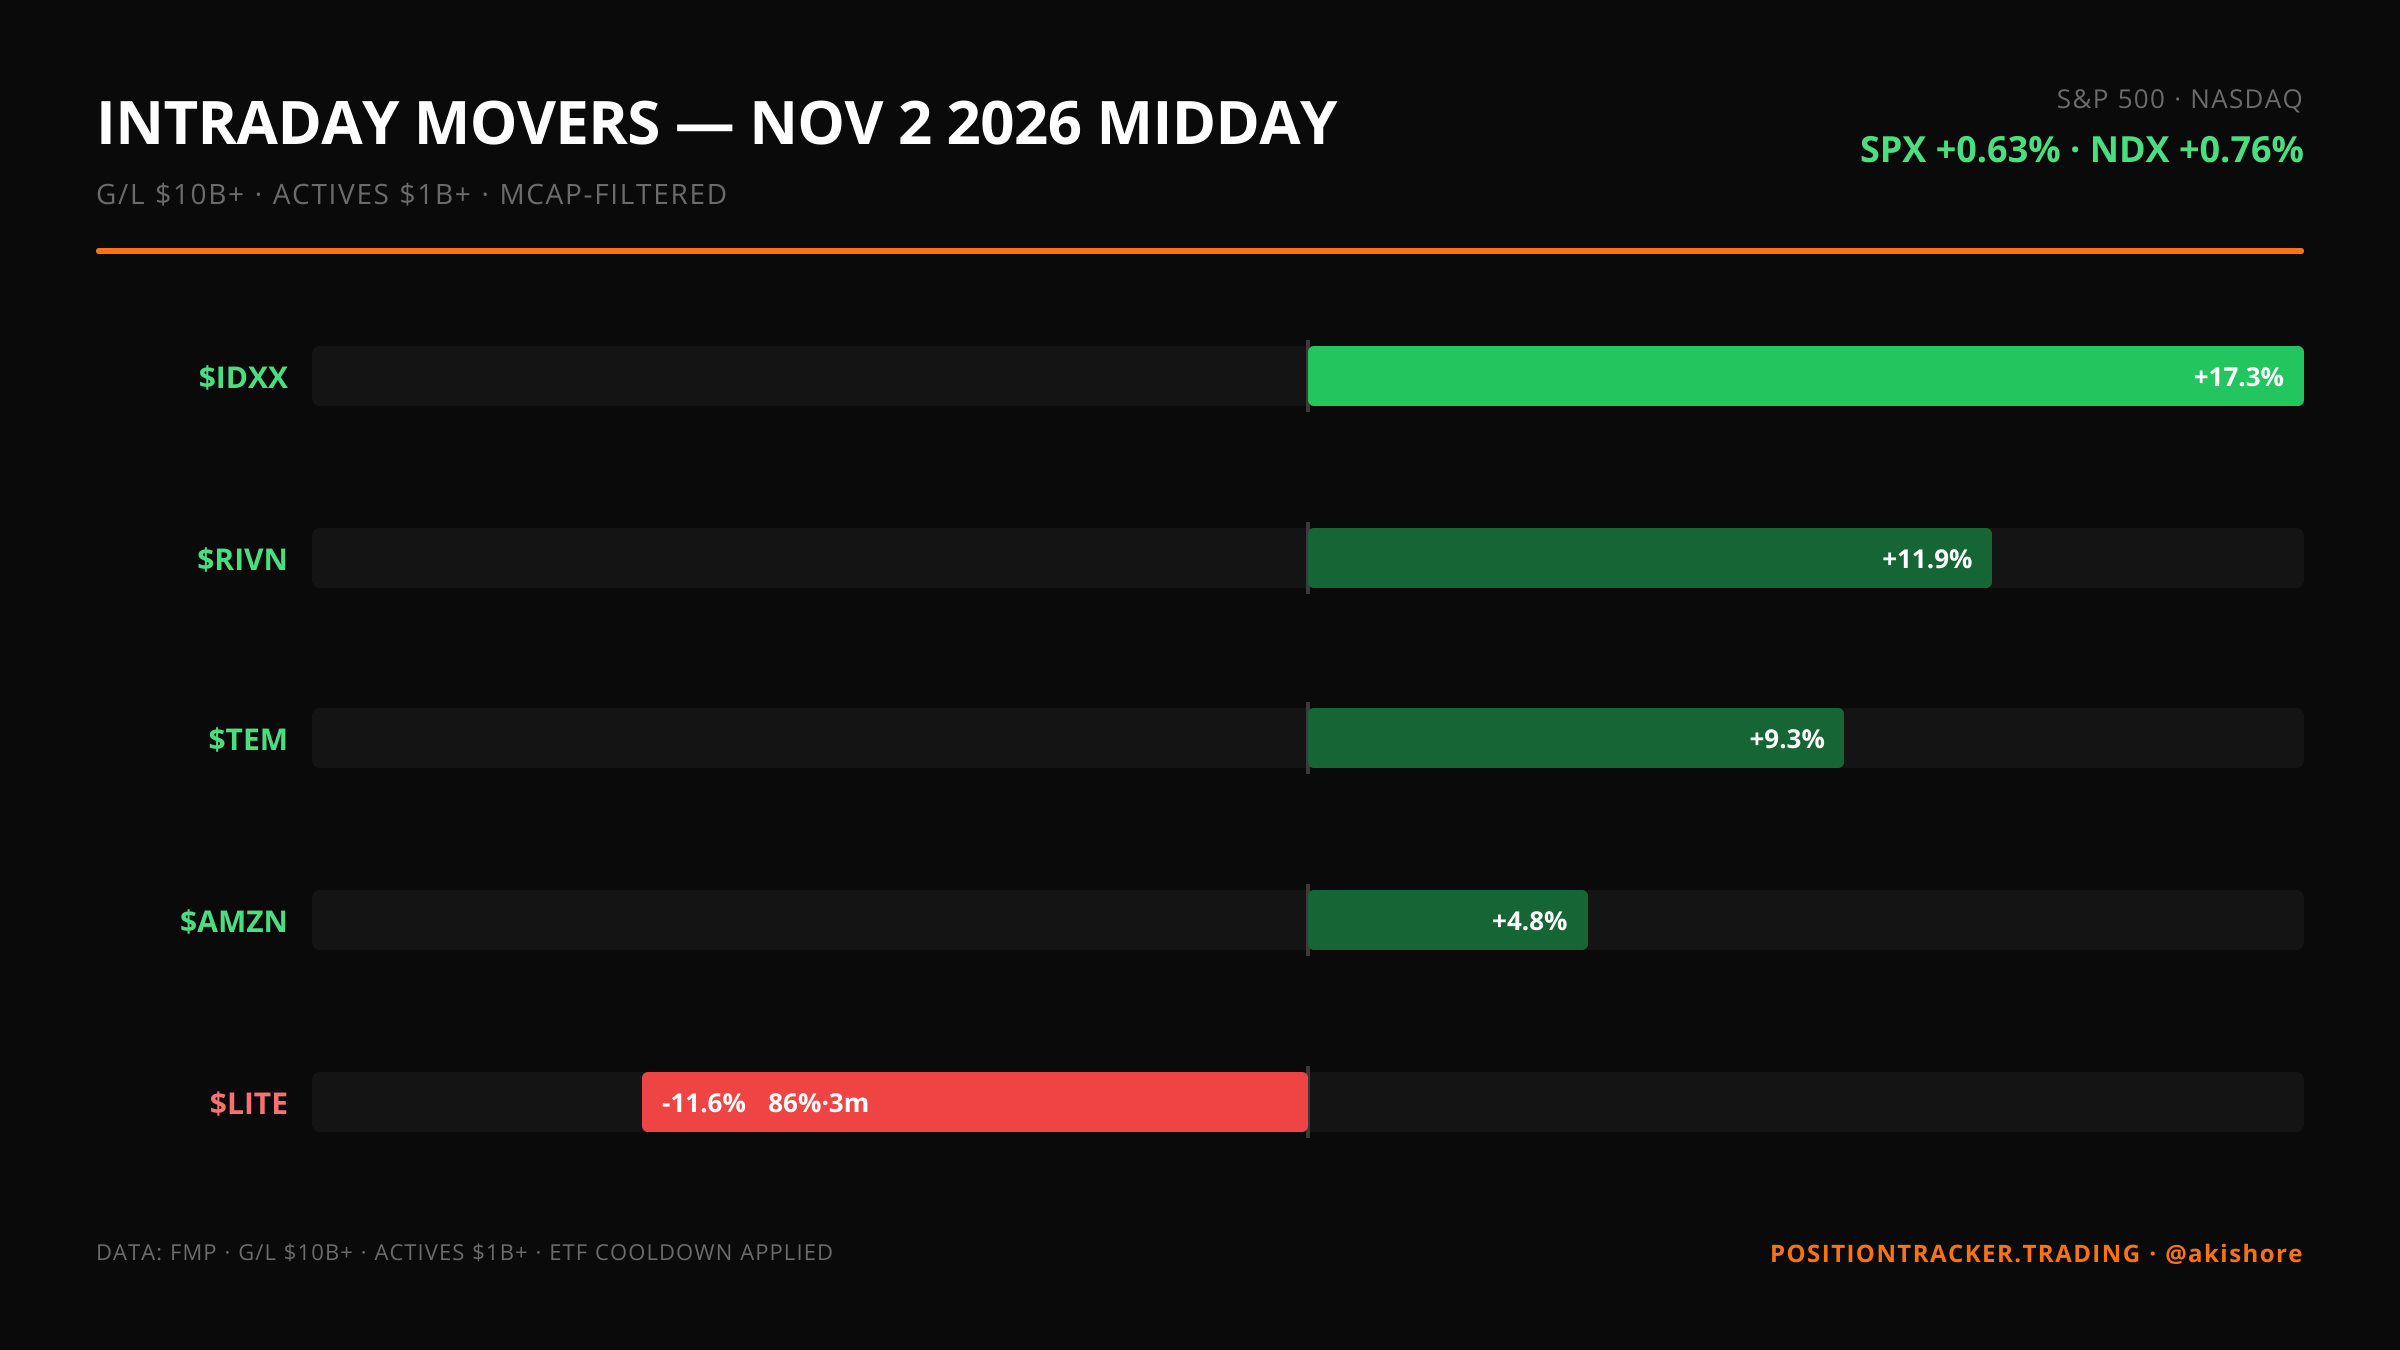
$IDXX is up 17.29% at midday after a Q3 beat and raised FY2026 guidance. The S&P 500 is up 0.63% to 7,627.90, and the Nasdaq is up 0.76% to 25,630.86. IDEXX ($51.5B) reported Q3 non-GAAP EPS of $3.96, beating estimates by $0.25, on…
AI infrastructure spending now divides mega-cap technology based on free cash flow sustainability, and the latest quarter made the split sharper.
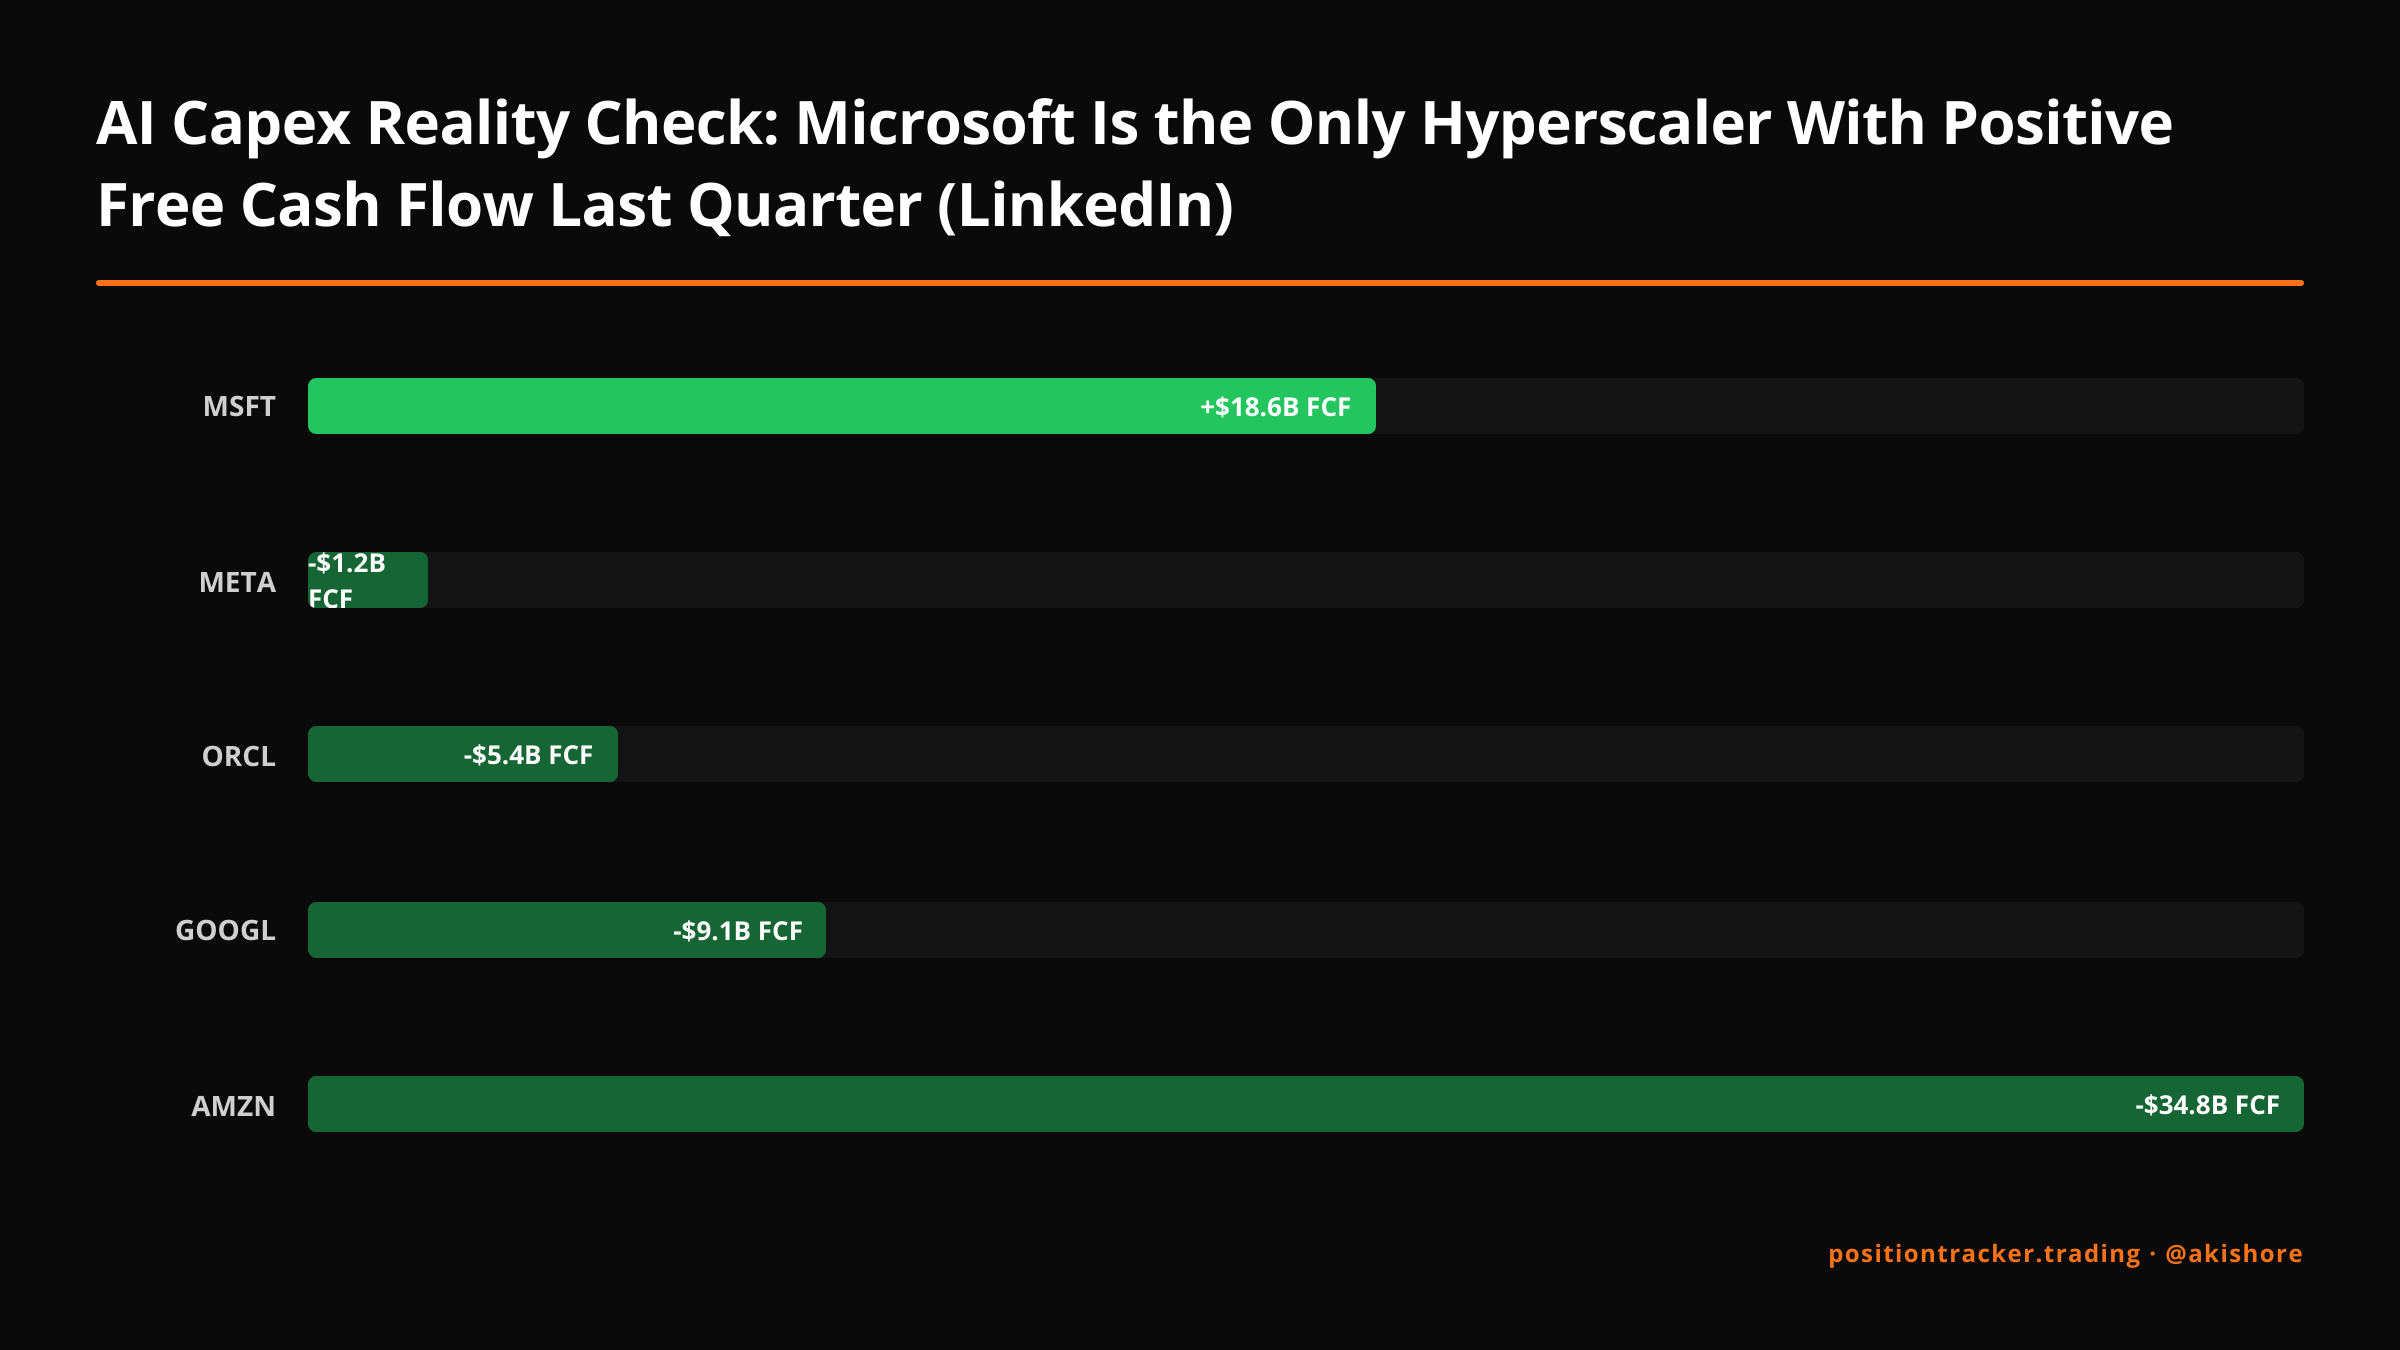
AI infrastructure spending now divides mega-cap technology based on free cash flow sustainability, and the latest quarter made the split sharper. $AMZN posted Q3 free cash flow of -$34.8B, taking its trailing-12-month figure to -$46.9B, while reaffirming roughly $220B in 2026 cash capex.…