The number that matters in CXMT's quarter is 19.3%, the sequential growth.
The number that matters in CXMT's quarter is 19.3%, the sequential growth. Everyone is quoting 613% year over year, but quarter on quarter China's memory champ grew far more modestly, which makes the cheap-Chinese-supply panic look like a convenient story for a selloff that has more than one driver.
- Reuters reports CXMT's Q3 revenue at 118.71 billion yuan, up 613.2% YoY and up 19.3% sequentially, and credits AI-driven demand and higher memory prices. That reads like a rising tide lifting every memory maker.
- MU was already down 4.98% at the October 29 close and sat 6.13% below that close in October 30 premarket at about $876.96. SNDK closed October 29 down 5.32%, then traded 8.36% below that close in October 30 premarket at $1,218.88.
- SanDisk reported results above estimates after the October 29 close, with $11.03B revenue, Q2 guidance of $12.2-12.6B and an 8-for-1 split, and the shares still traded lower. According to Reuters and other coverage, Intel's weak outlook and broad tech selling weighed on the whole group.
- The China risk cited in coverage is CXMT's reported 4F² design plans, and a design plan is a long way from high-yield mass production.
I'm still skeptical on memory long term because shortages end and the cycle turns, but I wouldn't pin this drop on one CXMT headline. What I want to hear is whether Micron addresses Chinese supply on its next call. I could be wrong, but for now that 19.3% looks more like the boom cooling than a flood of cheap supply.
Source:
Invezz: https://invezz.com/news/2026/10/30/cxmt-posts-613-jump-in-revenue-as-micron-sandisk-shares-tumble/
Not financial advice. For informational and educational purposes only.
Video explainer: Intel just posted its best data center growth in 15 years and the stock still fell about 25% before the open 📉
Intel just posted its best data center growth in 15 years and the stock still fell about 25% before the open 📉 Q3 revenue $16.5B (up 21%) and adjusted EPS 52…
If Bloomberg's report holds, Marvell would be paying for optics with its own stock.
If Bloomberg's report holds, Marvell would be paying for optics with its own stock. The market's first reaction fits my usual read on deals: they tend to favor the company being bought more than the buyer. Bloomberg reported on October 28, citing unnamed sources, that Marvell is…
Rates Hold Near 5%
The 10-year Treasury yield closed at 4.98%, up 2 basis points over the week, with long-end yields moving several times as much as bill yields.
The 10-Year Treasury yield closed at 4.98% in the latest session, up 2 basis points over the week. That small net change hides a wider swing: the 10-year sat at 5.13% in the prior week before dropping to 4.96%, then traded back up to 5.05% before settling…
End-of-day recap
Oct 29 brought sharp tech drops, a cash deal and mixed index closes.
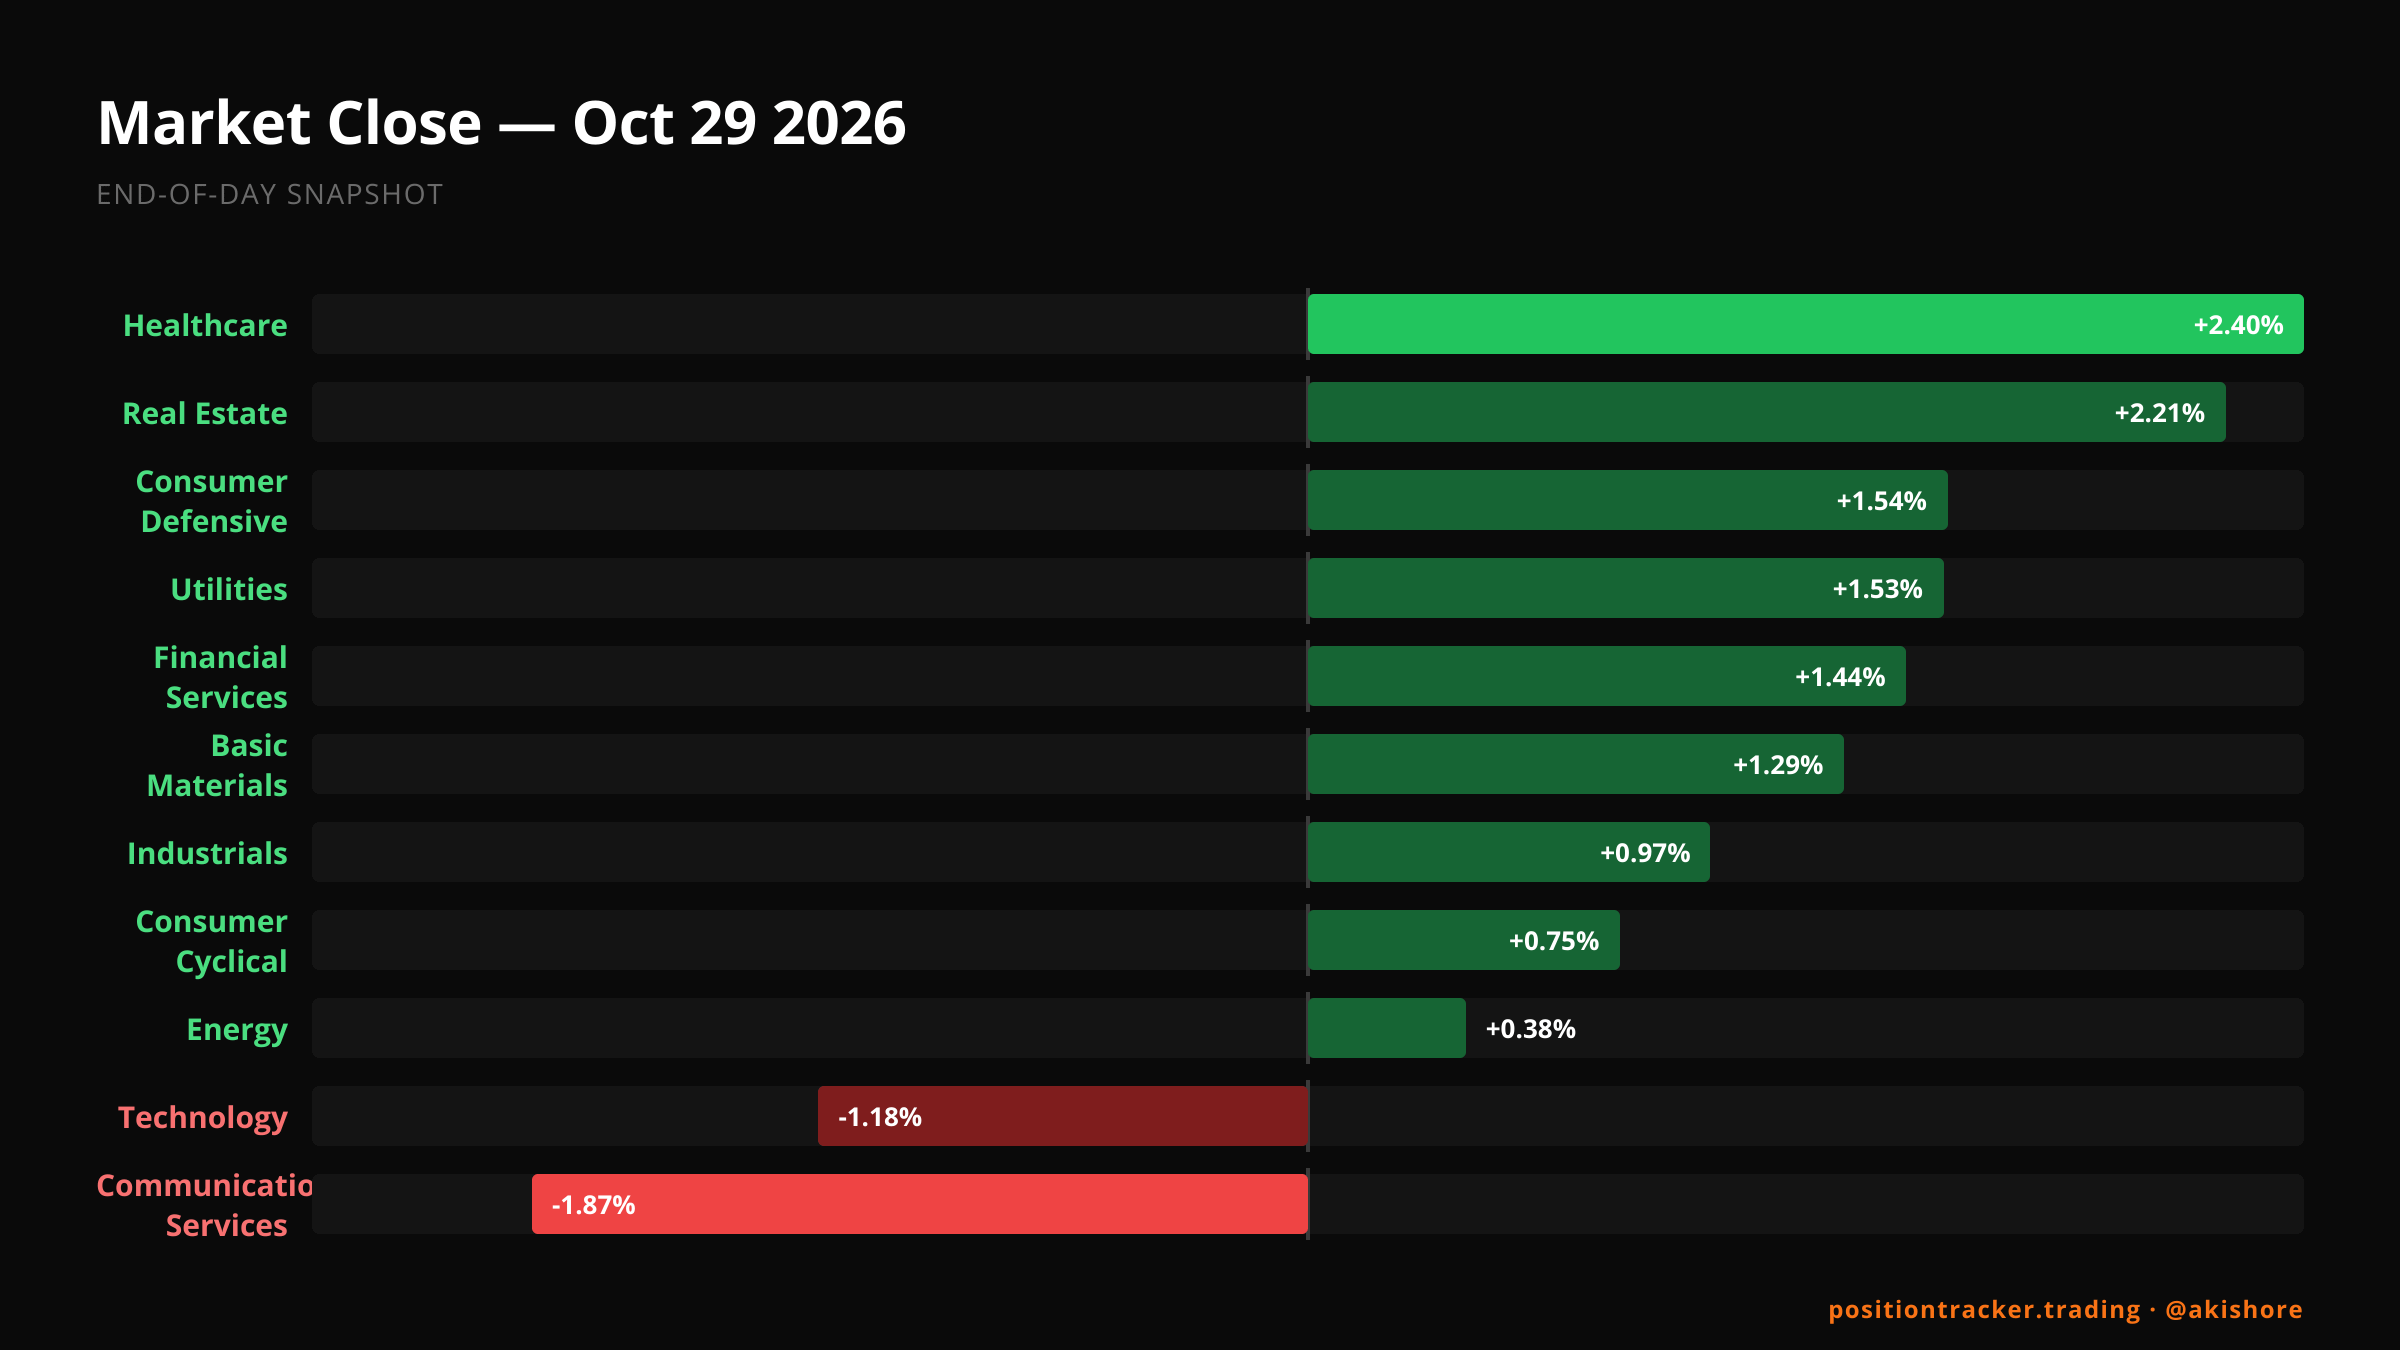
Oct 29 brought sharp tech drops, a cash deal and mixed index closes. Alphabet closed at $283.82, down 12.64%. Earnings and revenue missed expectations, and Search revenue missed forecasts for a second straight quarter. CNBC tied the drop to those results and fears AI chat and agents are taking Search volumes.