The people most exposed to the neocloud selloff are lenders and holders of CoreWeave-style credit, and Nvidia shareholders sit one step…
The people most exposed to the neocloud selloff are lenders and holders of CoreWeave-style credit, and Nvidia shareholders sit one step behind them through the company's cloud commitments and a potential guarantee. I read this as a credit question more than a demand question.
- CNBC reported on October 24 that CoreWeave, Nebius and IREN are each down at least 30% in October, and that CoreWeave's five-year credit default swaps have pushed past 11%. Buying default protection on that paper is now expensive.
- Nvidia's July filing reportedly includes $36B in AI-cloud agreements. These are commitments to buy cloud capacity, including capacity providers can't sell elsewhere. When the partner's credit weakens, that capacity starts to look like support for the partner.
- Separately, a report describes a potential Nvidia guarantee of up to $105B tied to an OpenAI-leased Ohio campus, depending on the deal's terms. It's conditional exposure, and nothing has been paid.
- $NVDA closed October 23 at $210.96 and is down 7.6% for the month per CNBC. CNBC reports Jensen Huang has called demand off the charts, and strong demand can coexist with stretched financing.
This is the fiber-and-telecom pattern I keep worrying about, and it pushes me further from flipping on AI capex. Nvidia's cash flow means it isn't in danger. Still, I'd watch CoreWeave's CDS and any sign a neocloud leans on Nvidia-linked support before calling this contained.
Not financial advice. For informational and educational purposes only.
Viral chart: global stocks down ~$10T from highs, South Korea -43%; a 43% drop needs a 75% gain to recover
A chart going around X this weekend says global stock markets have lost about $10 trillion from their yearly highs, with South…
US semiconductor producer prices +26% YoY in September; at that pace chip prices double in about 3 years
US producer prices for chips and electronic components rose 26% YoY in September, the 6th…
Apollo's Torsten Slok: AI shows zero payoff in the S&P 493, so the gains sit in 7 of 500 companies (1.4%)
Apollo's latest note: the AI story will be decided in the S&P 493, not the Mag 7. And so far…
Black Monday 1987 — 22.6% in a Day, Still the Benchmark
On October 19, 1987, the Dow fell 508 points, or 22.6%, closing at 1,738.74 versus 2,246.74 on October 16, still the Dow's worst one-day percentage…
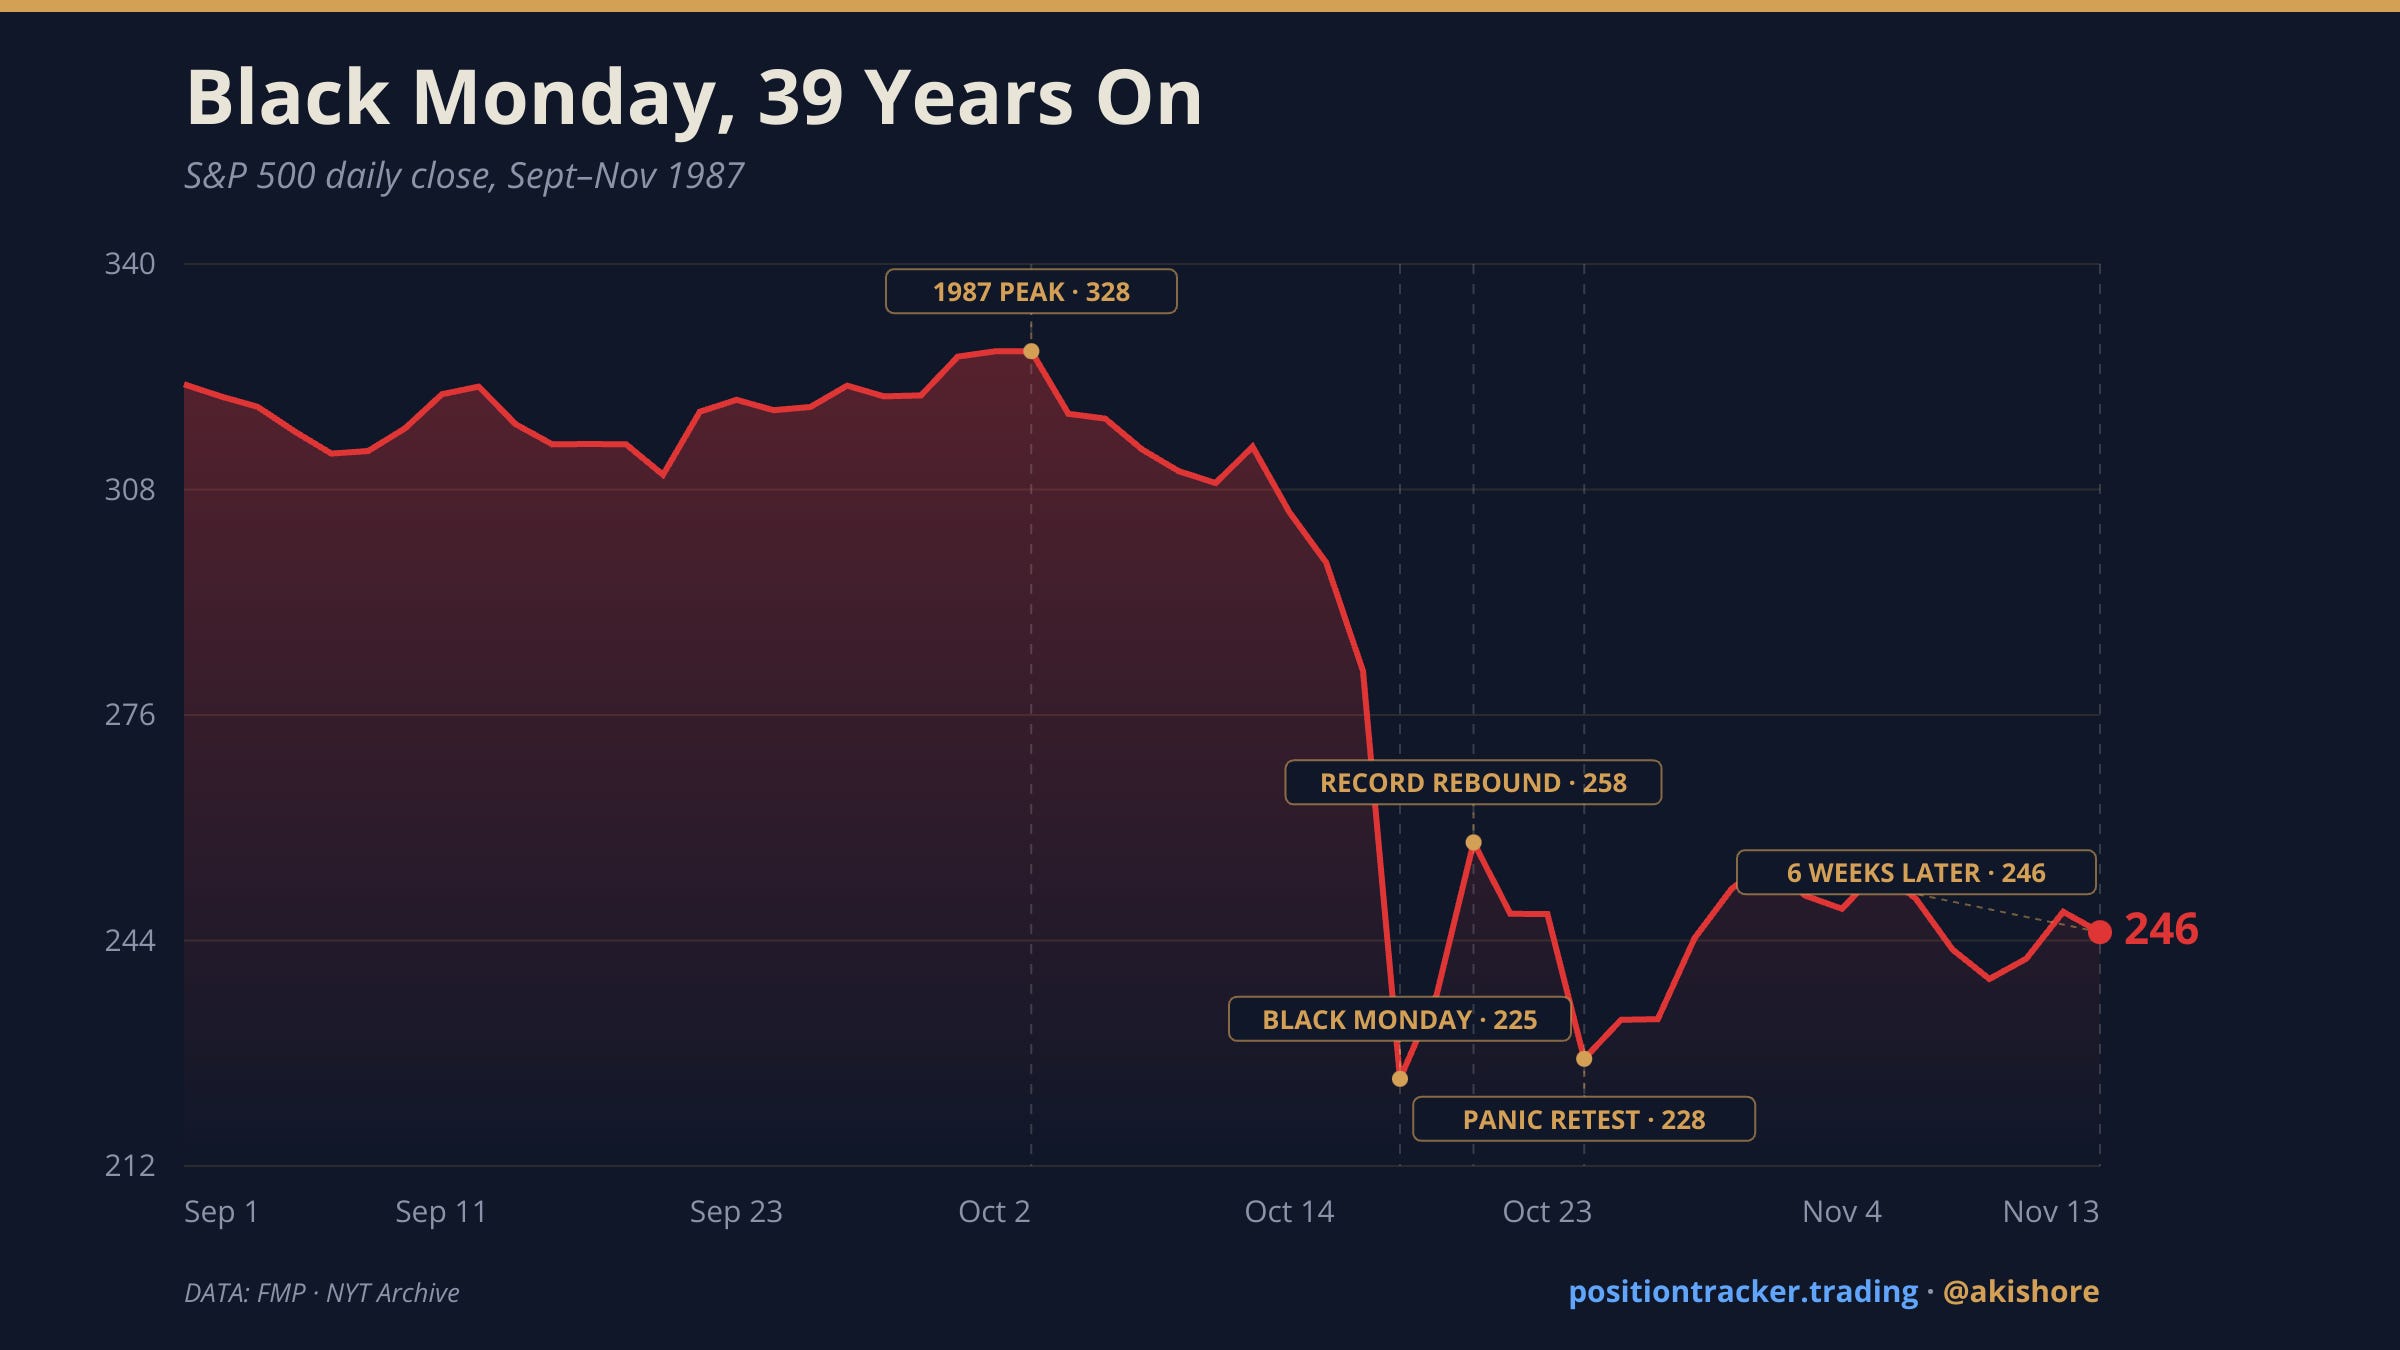
On October 19, 1987, the Dow fell 508 points, or 22.6%, closing at 1,738.74 versus 2,246.74 on October 16, still the Dow's worst one-day percentage decline on record. The S&P 500 dropped 20.47%, from 282.70 to 224.84, its own worst day. Analyses…