$AAPL deep dive: best September quarter ever but the stock fell on a margin guide. I think it's a hold
$AAPL just had the best September quarter in its history and the stock still fell. I think it's a hold because the demand is real but you are paying a premium right as margins shrink.
FQ4: revenue $114.5B (+12%) vs $113.4B expected. iPhone did $57.6B (+17%), Mac jumped 24% and Services hit a record $31.6B but grew only 10%. EPS of $2.10 beat $1.99. Greater China grew 21% and @Apple bought back $24B of stock in one quarter.
The catch is the guide. Revenue is guided up 7% to 10% but gross margin drops to 45% to 46% from 47.9% as memory costs keep climbing. Services slows to 8% to 9% vs almost 11% expected. Last quarter's margin also got about a 1 point lift from tariff refunds. At about 37x earnings Apple costs more than Microsoft (27x) or Amazon (19x).
Chart: off the $351.73 high from Oct 23 and below the 20 and 50 day on heavy volume with RSI near 41. My Elliott read is wave 4 of an impulse from $246. The 38.2% retrace is $322 right under the Oct 1 low at $326. If that holds wave 5 points to the mid $390s. A close below $317 breaks the count.
My plan: buy between $318 and $322. A close above $352 with margins steadying makes it a buy. A close below $317 makes it a sell.
Not financial advice.
Record September quarter and the stock went down. That is what 37x earnings buys you.
Two frames from the deep dive: the record quarter that still sold off and my Elliott Wave levels ($322 to $333 wave 4 zone, $326 Oct 1 low, $317 invalidation, ~$394 wave 5 target). Not financial advice. I'd rather buy $318 to $322 than chase it here.
Sources: Apple Newsroom release. Revenue $114.5B +12% , September quarter record; EPS $2.10; Services record; installed base all · CNBC live coverage. Revenue $114.48B vs $113.39B LSEG; EPS $2.10 vs $1.99; iPhone $57.58B vs $56.54B; Services $31.57B; · Reuters via CNA. Services guide 8% to 9% vs 10.7% Visible Alpha; rising memory costs; shares slip · Motley Fool call transcript. "Unprecedented" memory pricing, rising beyond the December quarter; Duo supply constrained; · Investing.com call transcript same call, confirms the above · CNBC analyst roundup, Nov 3 margin outlook; targets trimmed; stock up about 24% YTD before the report
Not financial advice. For informational and educational purposes only.
Hershey ($HSY): buy in pieces $156 to $170, long term
$HSY: I think Hershey is a buy because the margin recovery is already here and the stock has not priced it in. 11% below its 200-day About 19x the 2026 earnings guide 3.5% dividend yield I'm buying in pieces between $156 and $170 to hold for years.
Quote post: @zerohedge on stock pickers and quants both losing 3%+ in October
Goldman says stock pickers lost 3.5% and quants lost 3.6% in October. That's the first month in its data since…
Chip stocks bouncing into AMD's Q3 print looks like a relief rally that is mostly about one name, and I'm still skeptical on semis.
Chip stocks bouncing into AMD's Q3 print looks like a relief rally that is mostly about one name, and I'm still skeptical on semis. AMD is doing the lifting, and the rest of the group is fading. $AMD is at $493.10, up 5.63% from a $466.84…
Volcker Shock & the 1980s Bull — 20% Rates to 3.75%-4.00%
In June 1981, the Federal Reserve pushed the Fed Funds rate to 20% to break inflation running at 14.8%, the most aggressive tightening cycle in Fed…
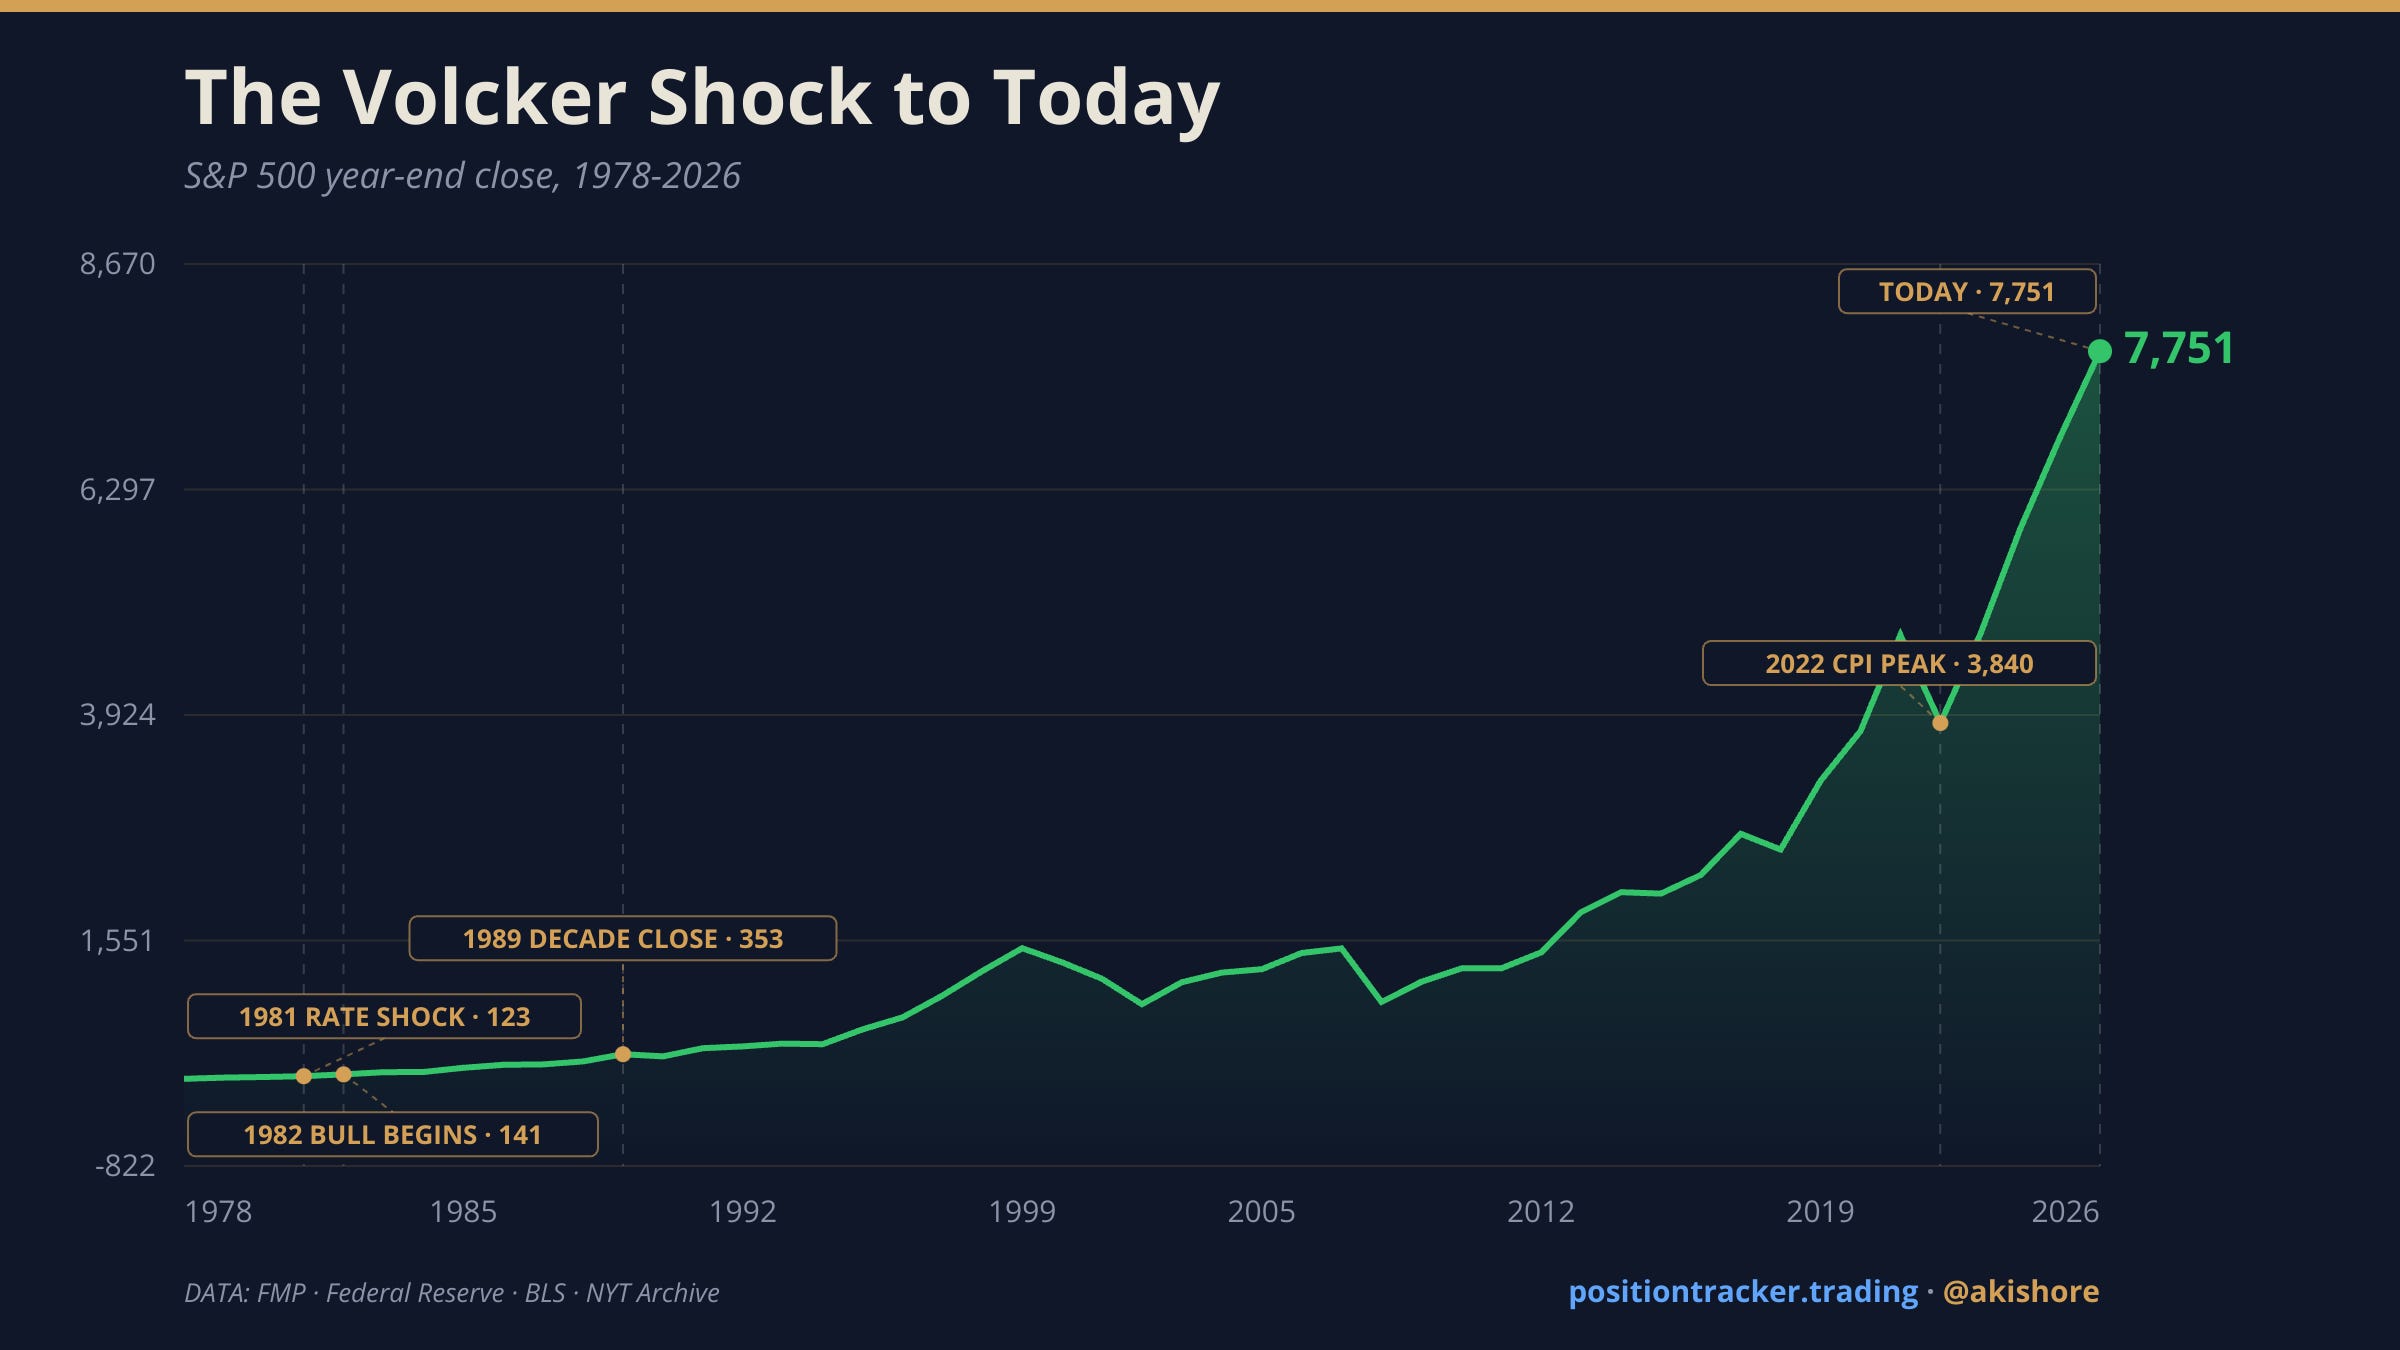
In June 1981, the Federal Reserve pushed the Fed Funds rate to 20% to break inflation running at 14.8%, the most aggressive tightening cycle in Fed history. The market absorbed the full cost of it. The S&P 500 bottomed at 102.42 on August…