Hershey ($HSY): buy in pieces $156 to $170, long term
$HSY: I think Hershey is a buy because the margin recovery is already here and the stock has not priced it in.
11% below its 200-day
About 19x the 2026 earnings guide
3.5% dividend yield
I'm buying in pieces between $156 and $170 to hold for years.
Not financial advice
The bear case: Q3 volume fell about 10 points while prices rose about 11 points. Management trimmed the organic sales guide to about 3% and cited a more cautious consumer and weaker convenience stores. If people keep buying less candy at these prices the recovery takes longer.
The chart: I read the fall from the $239 top on March 2 as an A-B-C correction. A ended at $168 in June, B bounced to $190 in August and C bottomed at $156 on Oct 1. The Oct 29 low of $160 held above it. The C low sits just under the 78.6% retrace of the 2025 to 2026 run.
The business: Q3 adjusted EPS was $2.64 against a consensus near $2.12. Adjusted gross margin rose 1,090 basis points to 42.7%. Management raised the 2026 adjusted EPS guide to $8.58 to $8.74 and still expects low double-digit EPS growth in 2027.
My plan: I'm adding between $156 and $170 and holding for years. A weekly close below $140, the February 2025 low, means I'm wrong. The $1.452 quarterly dividend pays me about 3.5% a year while volumes recover. This is a multi-year hold, not a trade.
Sources: Hershey Q3 2026 results (SEC exhibit 99.1) · Hershey Q3 2026 results press release · Zacks via Yahoo Finance: HSY Q3 earnings top estimates · Investing.com: Hershey Q3 2026 earnings call transcript · MarketBeat: Hershey Q3 2026 prepared remarks · RTTNews: Hershey lifts FY26 earnings view, cuts organic sales forecast
Not financial advice. For informational and educational purposes only.
Ubisoft, others bid to buy Arkane Studios from Microsoft
Microsoft's gaming unit is exploring a sale of Arkane Studios, the French developer behind Dishonored…
Analog Devices completes acquisition of Alif Semiconductor
Analog Devices (NASDAQ: ADI) announced it has completed its acquisition of Alif Semiconductor, per PRNewswire.…
Palantir posted a quarter most companies would frame and hang on the wall.
Palantir posted a quarter most companies would frame and hang on the wall. Q3 revenue came in at $2.313 billion, up 96% year-over-year, ahead of the roughly $2.17-2.18 billion consensus. Adjusted EPS of $0.44 beat too, its 10th straight EPS beat. US commercial revenue hit $984 million, up 148%, and passed US…
Volcker Shock & the 1980s Bull — 20% Rates to 3.75%-4.00%
In June 1981, the Federal Reserve pushed the Fed Funds rate to 20% to break inflation running at 14.8%, the most aggressive tightening cycle in Fed…
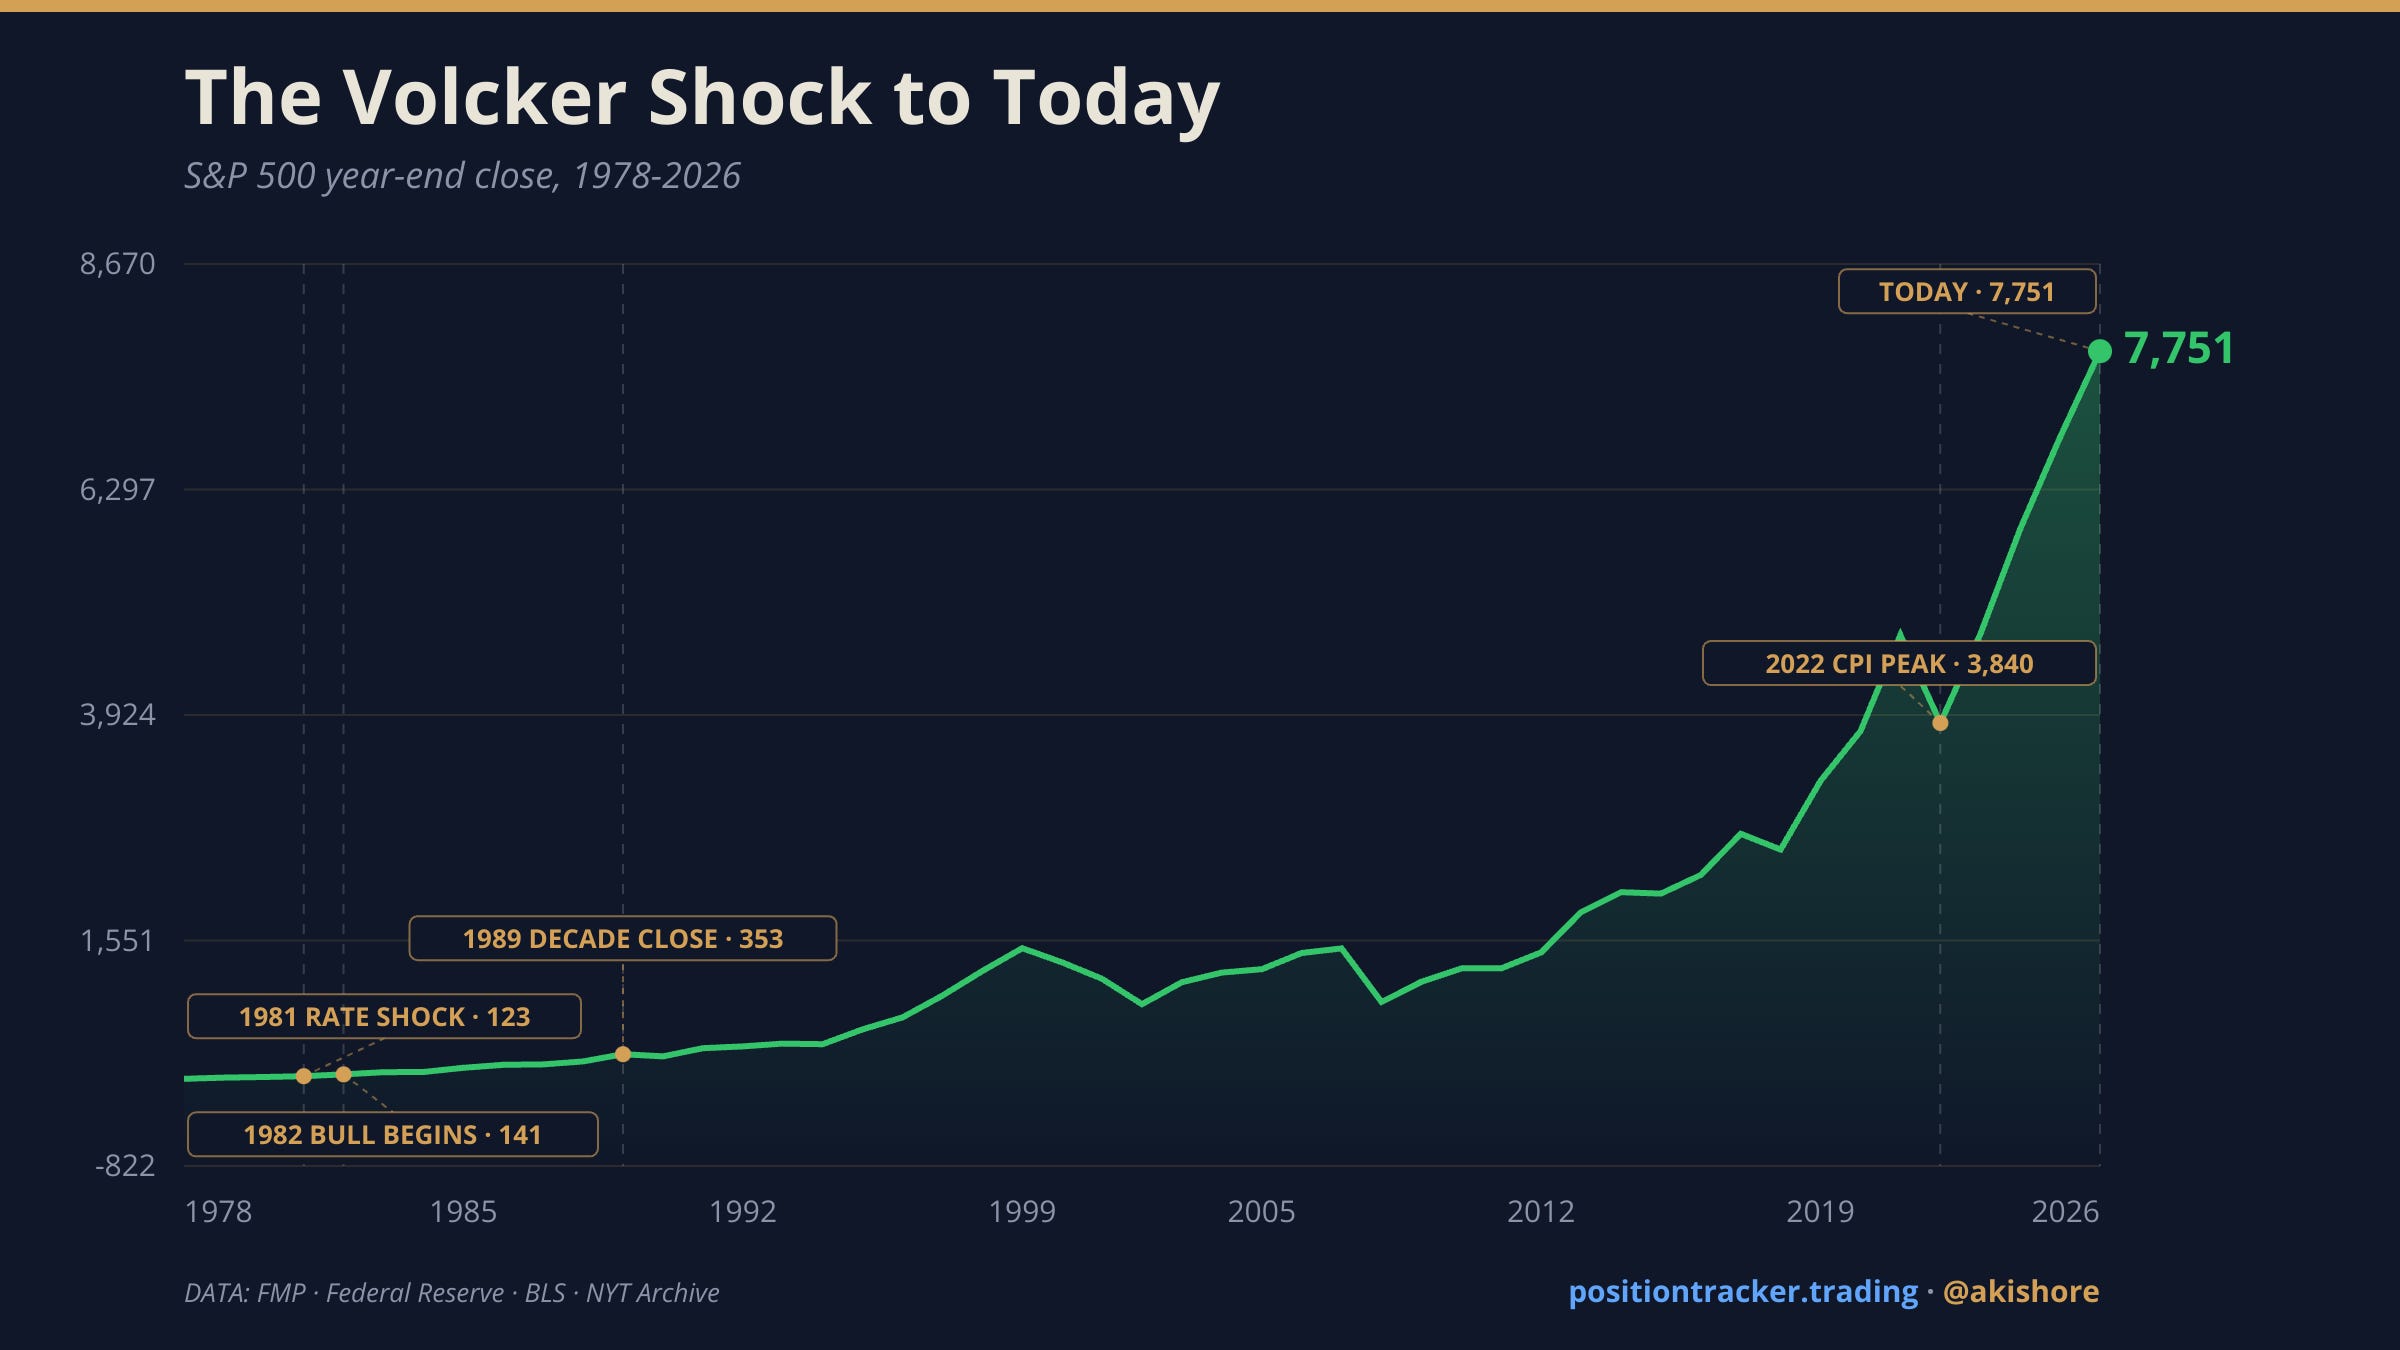
In June 1981, the Federal Reserve pushed the Fed Funds rate to 20% to break inflation running at 14.8%, the most aggressive tightening cycle in Fed history. The market absorbed the full cost of it. The S&P 500 bottomed at 102.42 on August…