Palantir posted a quarter most companies would frame and hang on the wall.
Palantir posted a quarter most companies would frame and hang on the wall. Q3 revenue came in at $2.313 billion, up 96% year-over-year, ahead of the roughly $2.17-2.18 billion consensus. Adjusted EPS of $0.44 beat too, its 10th straight EPS beat. US commercial revenue hit $984 million, up 148%, and passed US government revenue for the first time. Full-year guidance went up to $8.530-8.534 billion.
The stock still got hit. It opened at $167.90 against Monday's $178.34 close and bottomed at $165.25, down 7.34%. Then it clawed back to close at $175.34, down just 1.68%. Q4 guidance of $2.649-2.653 billion was above consensus, but it implies about 15% sequential growth after roughly 20% in Q3.
The number I keep looking at is total contract value: $2.918 billion, up just 6%. US commercial TCV grew 11%, after 153% in Q2. The CFO said several eight-figure deals were shorter in duration than usual, which shrinks TCV for the same annual value. Stock-based compensation also rose to $318.9 million from $172.3 million a year ago.
At this valuation, beating estimates is the baseline. What investors are really pricing is durability, and 165% net dollar retention plus 55% growth in remaining deal value argue for it. But 96% revenue growth sitting on 6% contract value growth is the question the market tried to price this morning, then mostly shrugged off by the close. Datadog and Snowflake finished higher, so this was a Palantir bookings question, not an AI software selloff.
Sources:
Yahoo Finance: https://finance.yahoo.com/markets/stocks/articles/palantir-falls-6-despite-earnings-134425731.html
Investing.com: https://uk.investing.com/news/stock-market-news/why-is-palantir-technologies-stock-sliding-today-93CH-4951548
Not financial advice. For informational and educational purposes only.
Priceline customers and BKNG shareholders are the ones paying for this FTC fight, and Booking just put a number on it: a $900 million…
Priceline customers and BKNG shareholders are the ones paying for this FTC fight, and Booking just put a number on it: a $900 million revenue reduction in Q3, plus a separate $100 million accrued loss. Per Reuters, the matter ties to the FTC's inquiry…
AMD's Q3 is the kind of print that puts pressure on my skeptical lean on semis.
AMD's Q3 is the kind of print that puts pressure on my skeptical lean on semis. Data Center did $8.546 billion, up 97% year over year, and management is guiding for Q4 growth to accelerate from there. Total Q3 revenue was $13.377 billion, up 45%,…
Negative $434 million.
Negative $434 million. That's Supermicro's operating cash flow in a quarter where it booked $1.594B of net income, and it's the number I'd watch over the headline revenue. Q1 FY2027 net sales came in at $19.946B versus $5.018B a year earlier,…
Volcker Shock & the 1980s Bull — 20% Rates to 3.75%-4.00%
In June 1981, the Federal Reserve pushed the Fed Funds rate to 20% to break inflation running at 14.8%, the most aggressive tightening cycle in Fed…
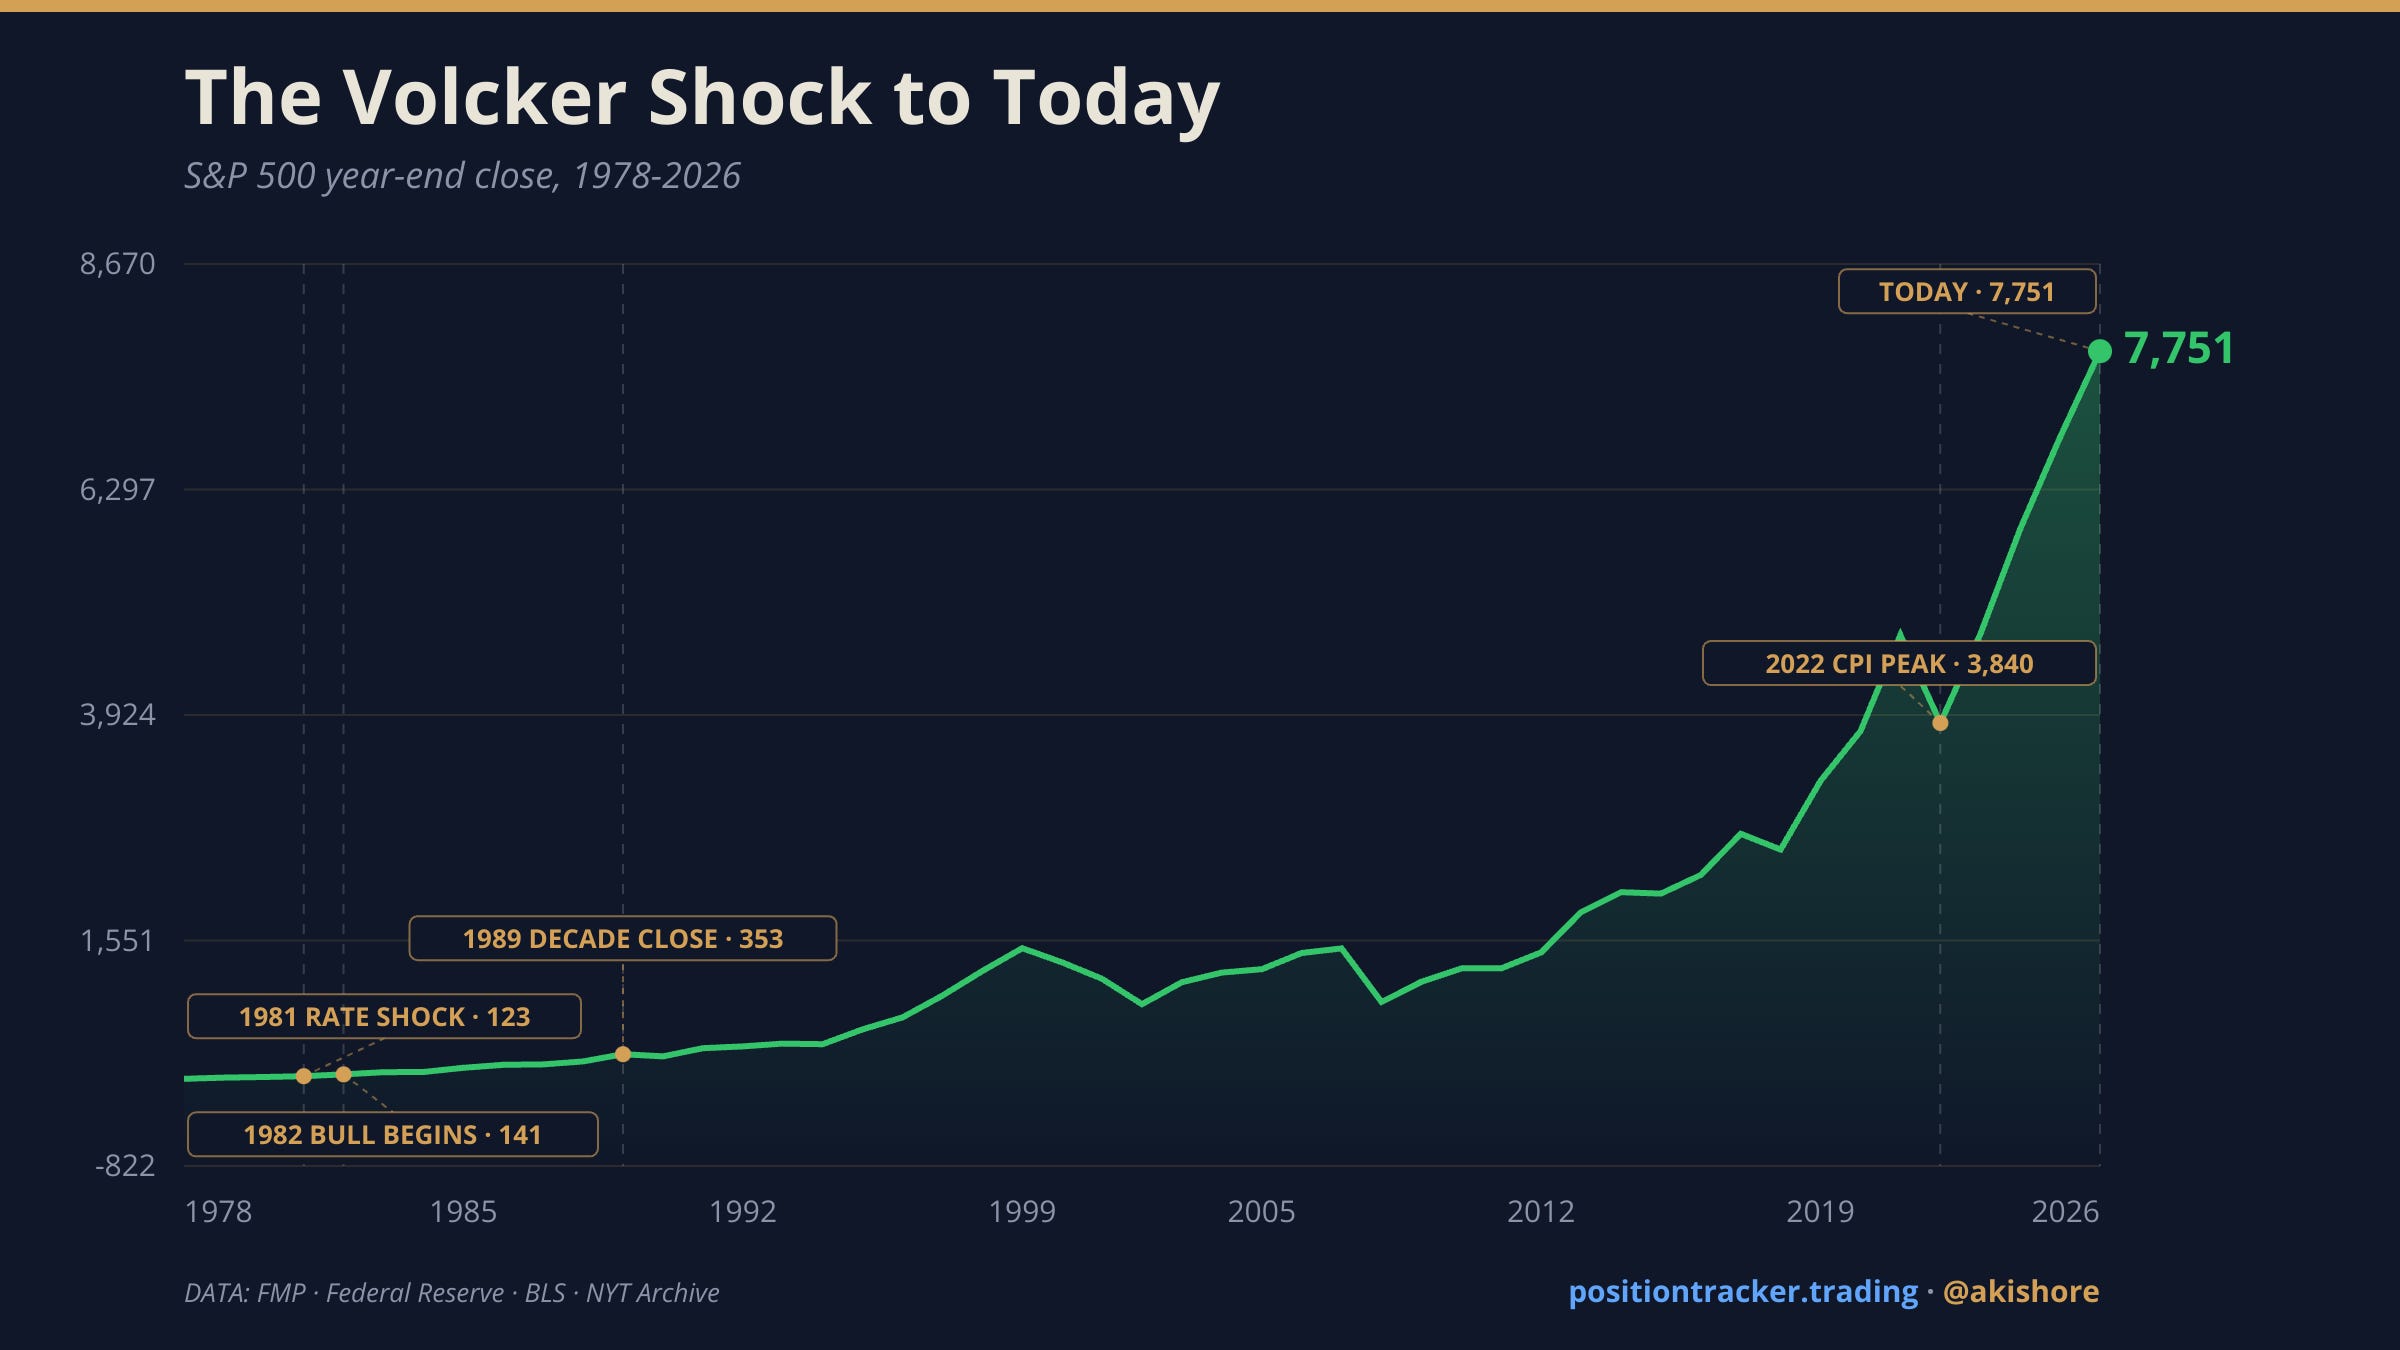
In June 1981, the Federal Reserve pushed the Fed Funds rate to 20% to break inflation running at 14.8%, the most aggressive tightening cycle in Fed history. The market absorbed the full cost of it. The S&P 500 bottomed at 102.42 on August…