CoreWeave: ~$129B backlog vs ~$50B debt is ~2.6x coverage, while CDS still prices ~64% 5yr default
CoreWeave's stock fell about 25% this week and some of its bonds now yield near 15%, after June paper priced at 9.675%. CEO Mike Intrator told staff the $104.2B backlog plus $25B+ in new commitments more than covers roughly $50B of debt.
Do the math: that backlog is about 2.6x the debt book. Credit markets still price a roughly 64% five-year default chance via CDS. Contract coverage and default odds are telling different stories.
Sources: Reuters: Intrator memo cites $104.2B backlog plus $25B+ Q3 commitments vs ~$50B debt; bonds near 16% · Reuters: June CoreWeave bonds issued at 9.675% yield; yield near 15% this week · @realMeetKevin: CoreWeave down 23% in 5 days; CDS suggest a 64% chance of default
Not financial advice. For informational and educational purposes only.
In July, Treasury fined a US company $200,000 because a subsidiary failed to report a $92,478 investment in a Chinese AI and robotics…
In July, Treasury fined a US company $200,000 because a subsidiary failed to report a $92,478 investment in a Chinese AI and robotics company. Treasury announced that first-ever penalty on Oct 7. It's the enforcement backdrop for the proposed rule Treasury put out on Thursday, Oct 22, and I think it tells you how seriously this program is going to…
Viral chart: global stocks down ~$10T from highs, South Korea -43%; a 43% drop needs a 75% gain to recover
A chart going around X this weekend says global stock markets have lost about $10 trillion from their yearly highs, with South…
US semiconductor producer prices +26% YoY in September; at that pace chip prices double in about 3 years
US producer prices for chips and electronic components rose 26% YoY in September, the 6th…
Black Monday 1987 — 22.6% in a Day, Still the Benchmark
On October 19, 1987, the Dow fell 508 points, or 22.6%, closing at 1,738.74 versus 2,246.74 on October 16, still the Dow's worst one-day percentage…
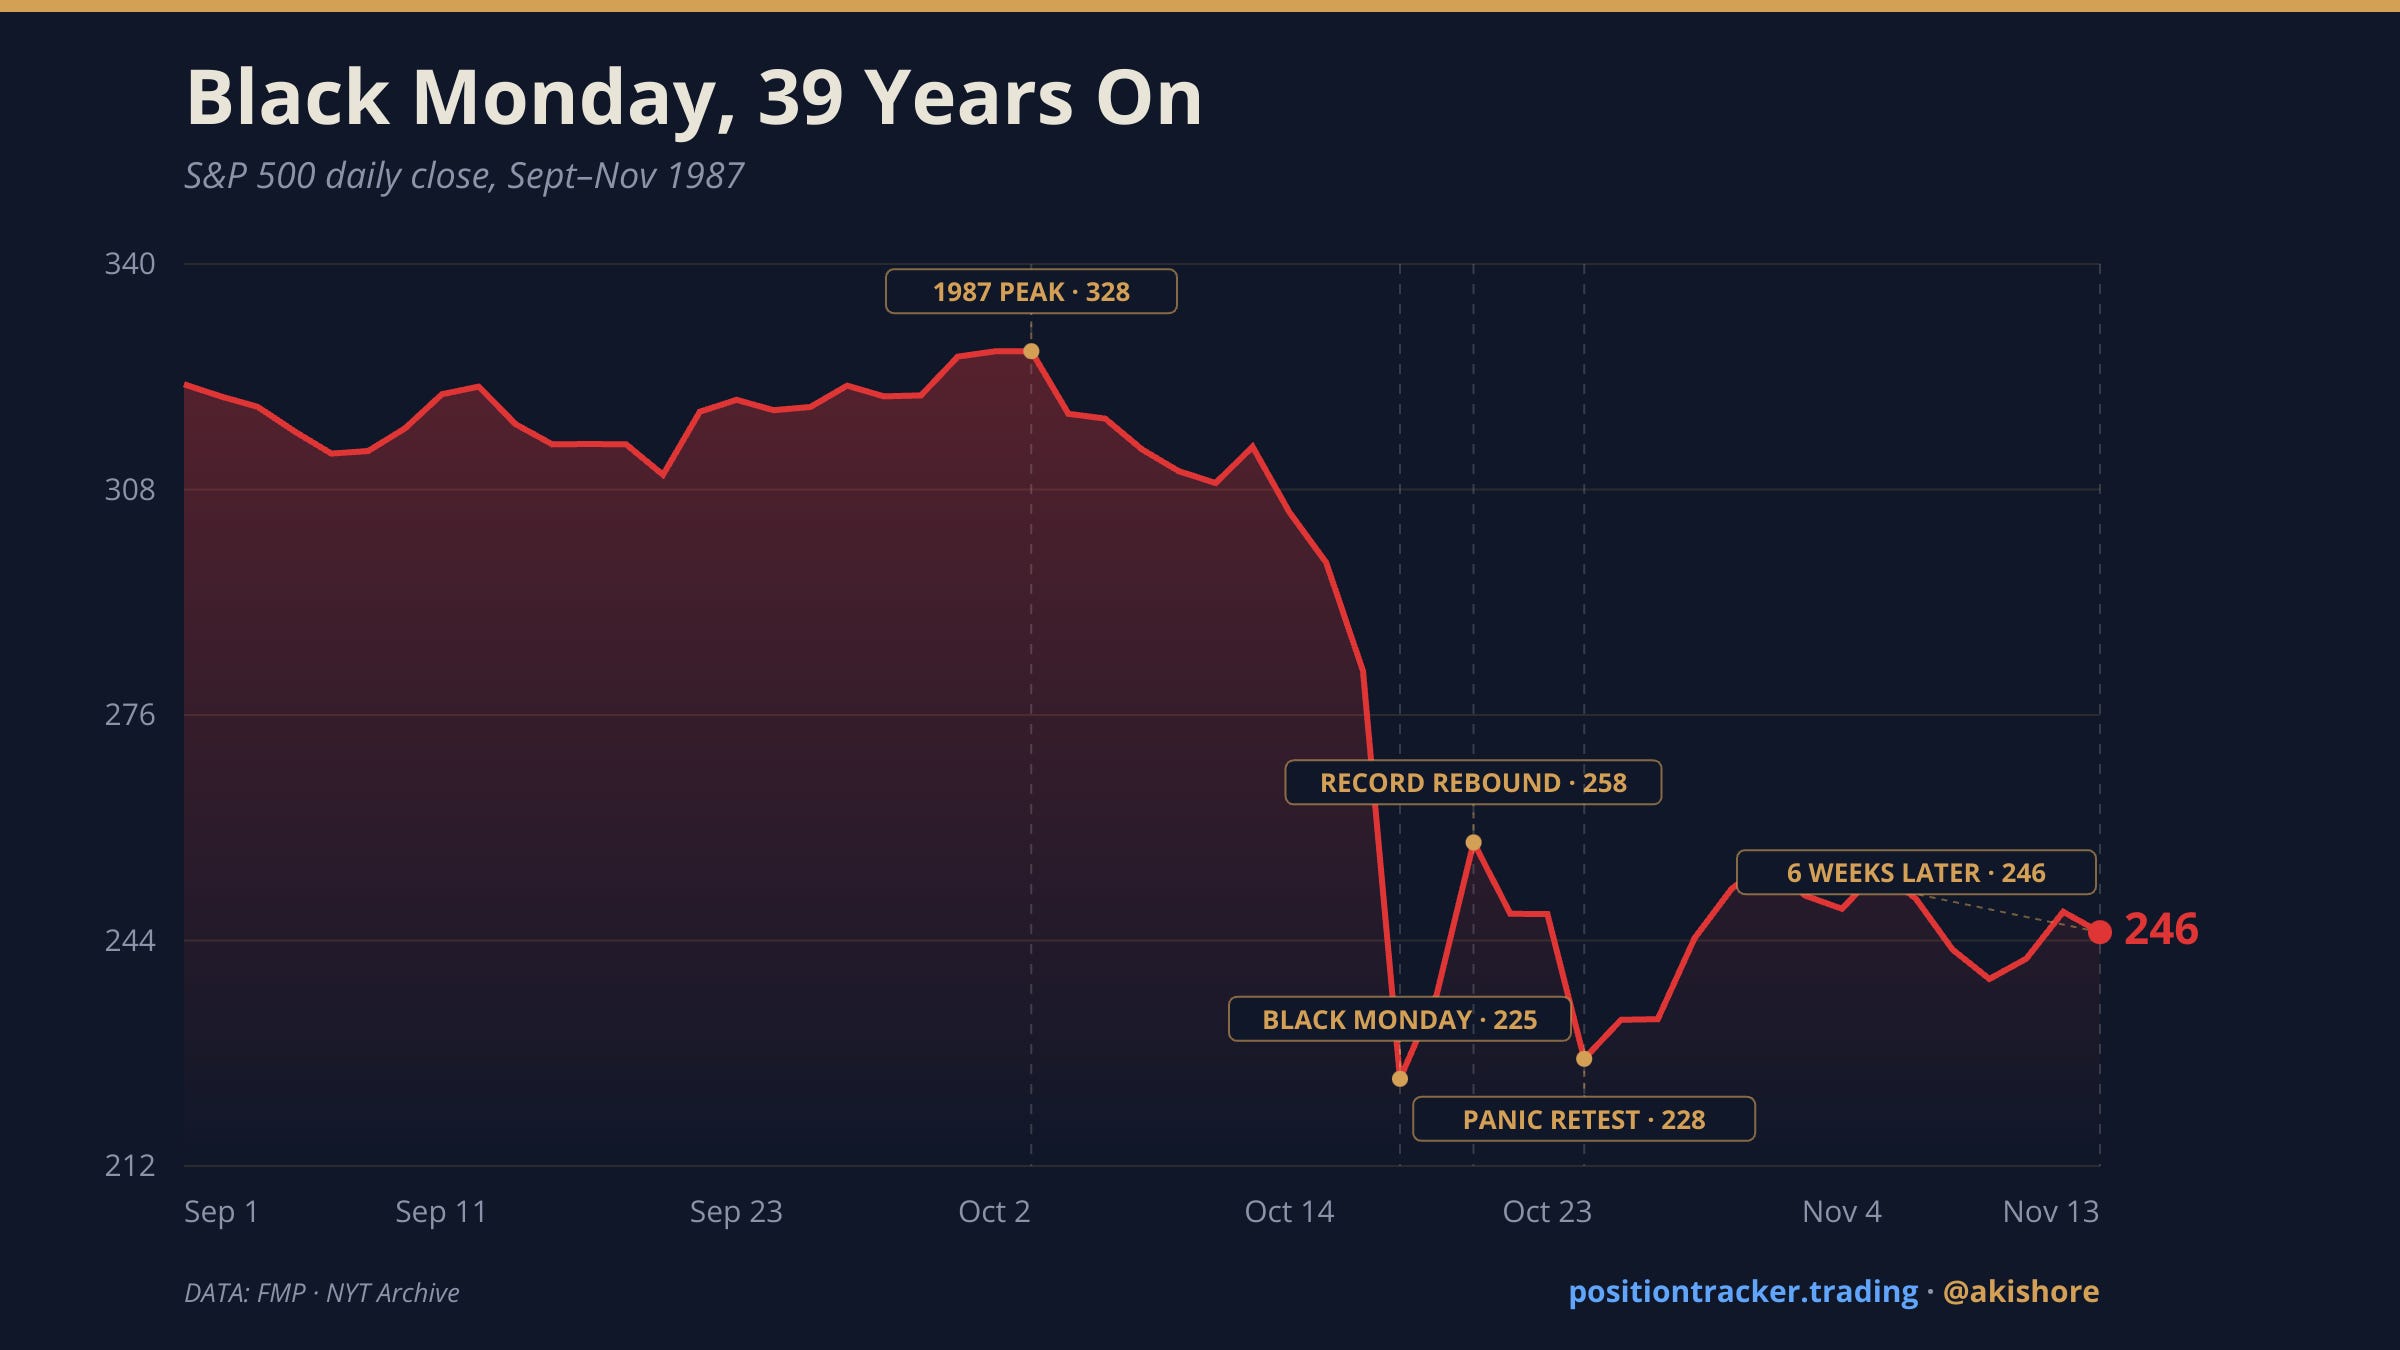
On October 19, 1987, the Dow fell 508 points, or 22.6%, closing at 1,738.74 versus 2,246.74 on October 16, still the Dow's worst one-day percentage decline on record. The S&P 500 dropped 20.47%, from 282.70 to 224.84, its own worst day. Analyses…