$FICO stock call: Buy the dip, accumulate $680 to $740
$FICO: I'm a buyer, but on a pullback to $680 to $740.
Down 66% from its 2024 top
24x earnings vs a 52x 5-yr avg
Still a 52% operating margin
I think VantageScore dents the pricing, not the franchise.
Would you buy FICO here?
Not financial advice
Bear case: it fell 26.5% on Sep 29 after the FHFA said Fannie and Freddie will use one pricing grid for FICO and VantageScore. Rocket made VantageScore its preferred score and TransUnion holds it at $0.99 through 2028. Debt is $5.6B vs $0.25B cash.
Chart + wave read: I read the drop from the $2,382 top as an A-B-C. A hit $1,311 in Aug 2025, B bounced to $1,880 and C hit $592 on Sep 30. That held the Jan 2023 floor near $586, close to the 78.6% retrace of the 2020-24 run ($676). The 38% bounce looks like wave 1.
The business: its scores are used by virtually all U.S. lenders. Fiscal Q3 revenue rose 26% to $674M and scores revenue rose 41%. The margin is 52% and it's cutting about 15% of jobs to push costs lower. Earnings are due in early November.
My plan: no chase after a 38% bounce in three weeks. I'd start at $740 and add down to $680, where the bounce's 50% to 61.8% retrace meets the long-term fib. First target is the 200-day near $1,150. A weekly close below $580 means I'm wrong. Multi-year hold.
Sources: FMP: quote, daily closes, financials, estimates, segments (data) · Fair Isaac 8-K: ~15% workforce reduction, ~$27M pre-tax charges · WSJ: Fair Isaac to cut about 15% of workforce · National Mortgage Professional: job cuts, Q3 revenue +26%, scores +41% · WSJ: Fair Isaac stock sinks on Pulte comment (Sep 29) · Yahoo Finance: one pricing grid, Rocket picks VantageScore
Not financial advice. For informational and educational purposes only.
In July, Treasury fined a US company $200,000 because a subsidiary failed to report a $92,478 investment in a Chinese AI and robotics…
In July, Treasury fined a US company $200,000 because a subsidiary failed to report a $92,478 investment in a Chinese AI and robotics company. Treasury announced that first-ever penalty on Oct 7. It's the enforcement backdrop for the proposed rule Treasury put out on Thursday, Oct 22, and I think it tells you how seriously this program is going to…
Viral chart: global stocks down ~$10T from highs, South Korea -43%; a 43% drop needs a 75% gain to recover
A chart going around X this weekend says global stock markets have lost about $10 trillion from their yearly highs, with South…
US semiconductor producer prices +26% YoY in September; at that pace chip prices double in about 3 years
US producer prices for chips and electronic components rose 26% YoY in September, the 6th…
Black Monday 1987 — 22.6% in a Day, Still the Benchmark
On October 19, 1987, the Dow fell 508 points, or 22.6%, closing at 1,738.74 versus 2,246.74 on October 16, still the Dow's worst one-day percentage…
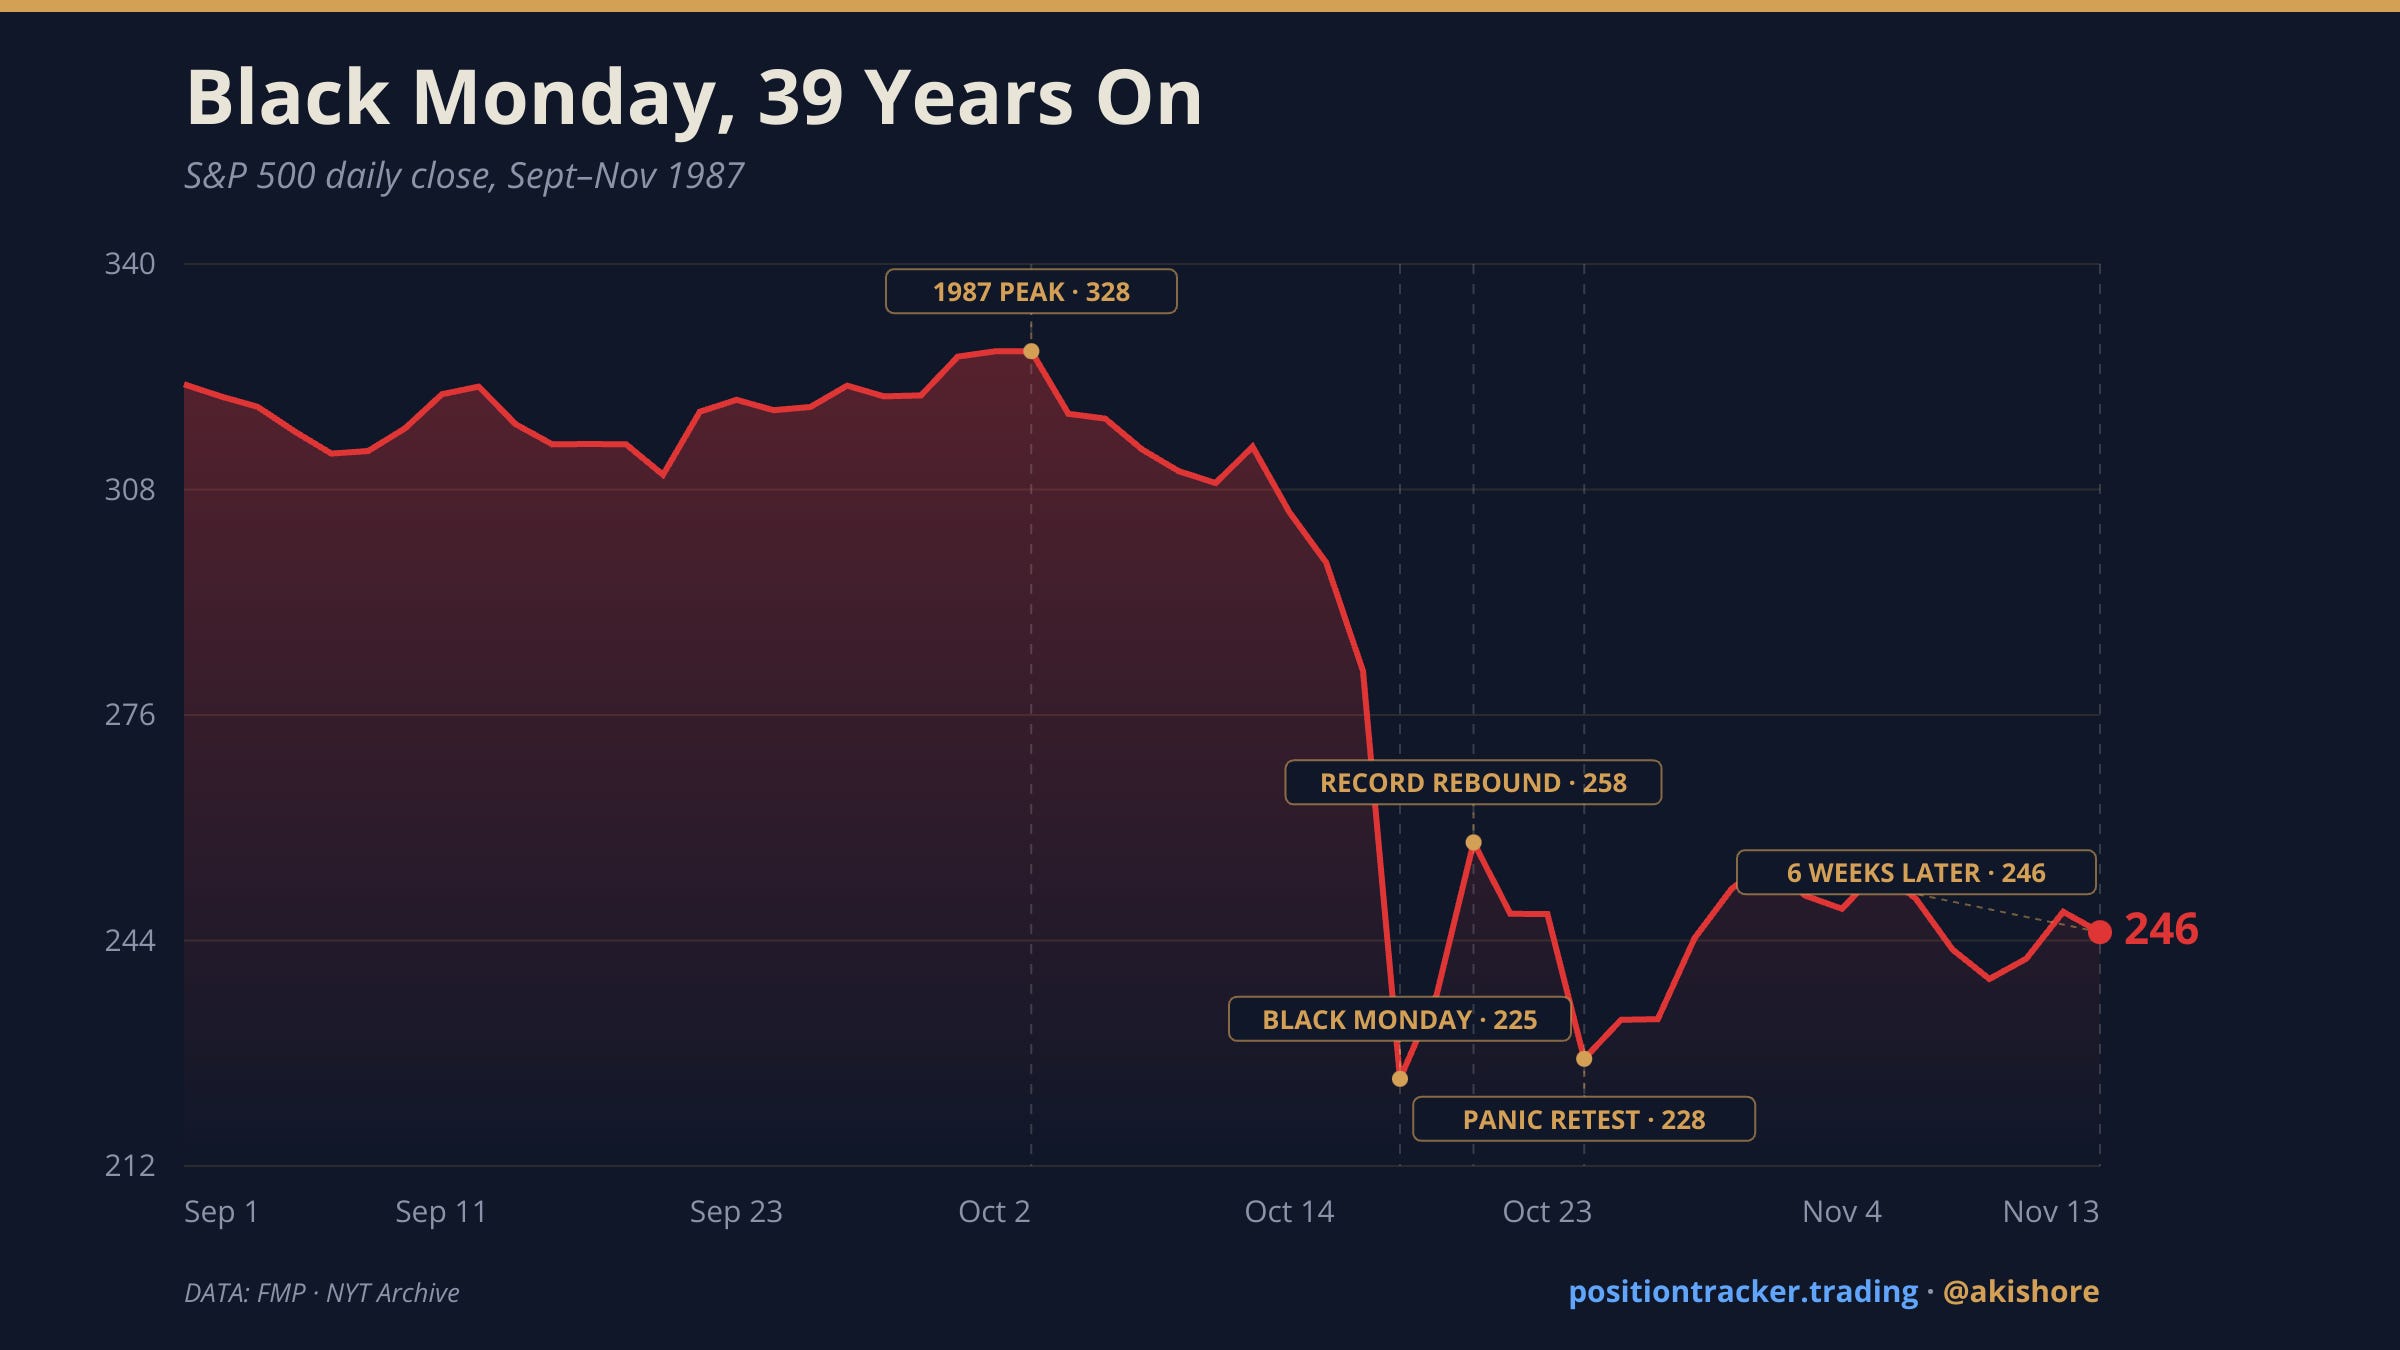
On October 19, 1987, the Dow fell 508 points, or 22.6%, closing at 1,738.74 versus 2,246.74 on October 16, still the Dow's worst one-day percentage decline on record. The S&P 500 dropped 20.47%, from 282.70 to 224.84, its own worst day. Analyses…