$INTC stock call: Not yet, buy zone $41 to $45
$INTC: Not yet. I think it gets cheaper and I'd buy around $45.
30% below its 200-day after its worst day since the 1970s
Q4 guide of $15B to $16B vs $17.1B expected
Still about 33x 2027 earnings
Not financial advice
The bear case is the guide. Q4 revenue of $15B to $16B vs $17.1B expected and adjusted EPS of $0.25 vs $0.43. Gross margin drops to 38% from 44.1%. The CFO sees PCs weak through at least the first half of 2027 and the Israel fab blast costs about $600M of revenue.
The chart: I count 5 waves up from the $17.67 Apr 2025 low to the $142.35 June top. The drop since is an A-B-C. A ended at $81.79, B bounced to $127.44 and C just sliced through the 61.8% retrace at $65. The 78.6% retrace is $44.35 and the wave 4 low is $40.63. That's my zone.
The business is better than the stock says. Q3 revenue grew 21% to $16.5B. Data center revenue jumped 78% to $7.3B, the best growth in 15 years. Foundry revenue rose 58%. Intel holds $54.0B of cash and investments vs $50.1B of debt.
My plan: no buy at $60. I'd start near $45, add near $41 and hold for years. A weekly close below $35 means my wave count is wrong and I step back. If it reclaims the 200-day near $87 first I'll miss it and that's fine.
Sources: Intel Q3 2026 financial results (Intel IR) · CNBC: Intel Q3 2026 earnings report · CNBC: Intel falls 29%, worst day since the 1970s · Ctech (Reuters): Intel plunges as Israel factory blast compounds weak outlook · Investing.com: Why is Intel stock sliding today (Nov 2) · Investing.com via Yahoo: Intel plunges on weak Q4 forecast
Not financial advice. For informational and educational purposes only.
$114.5B in revenue, up 12%, in John Ternus's first earnings report as Apple CEO.
$114.5B in revenue, up 12%, in John Ternus's first earnings report as Apple CEO. The beat is real, but the misses tell me more about where Apple's growth is coming from than the headline does. Apple says tariff refunds added about 1 point to its 47.9% gross margin and…
$984M in U.S.
$984M in U.S. commercial revenue, up 148% and bigger than U.S. government for the first time. That's who this quarter is about: Palantir is turning into a commercial software company, and the old SaaS names selling to those same…
Marvell just agreed to buy Lumentum in an all-stock deal with an enterprise value of $115 billion including debt.
Marvell just agreed to buy Lumentum in an all-stock deal with an enterprise value of $115 billion including debt. Bloomberg puts the equity value at roughly $102.6 billion. Lumentum shareholders get a fixed 4.5 Marvell shares for each Lumentum share, and Marvell shareholders will own about 67% of the combined company. It's a signed agreement, not a done deal: the…
Volcker Shock & the 1980s Bull — 20% Rates to 3.75%-4.00%
In June 1981, the Federal Reserve pushed the Fed Funds rate to 20% to break inflation running at 14.8%, the most aggressive tightening cycle in Fed…
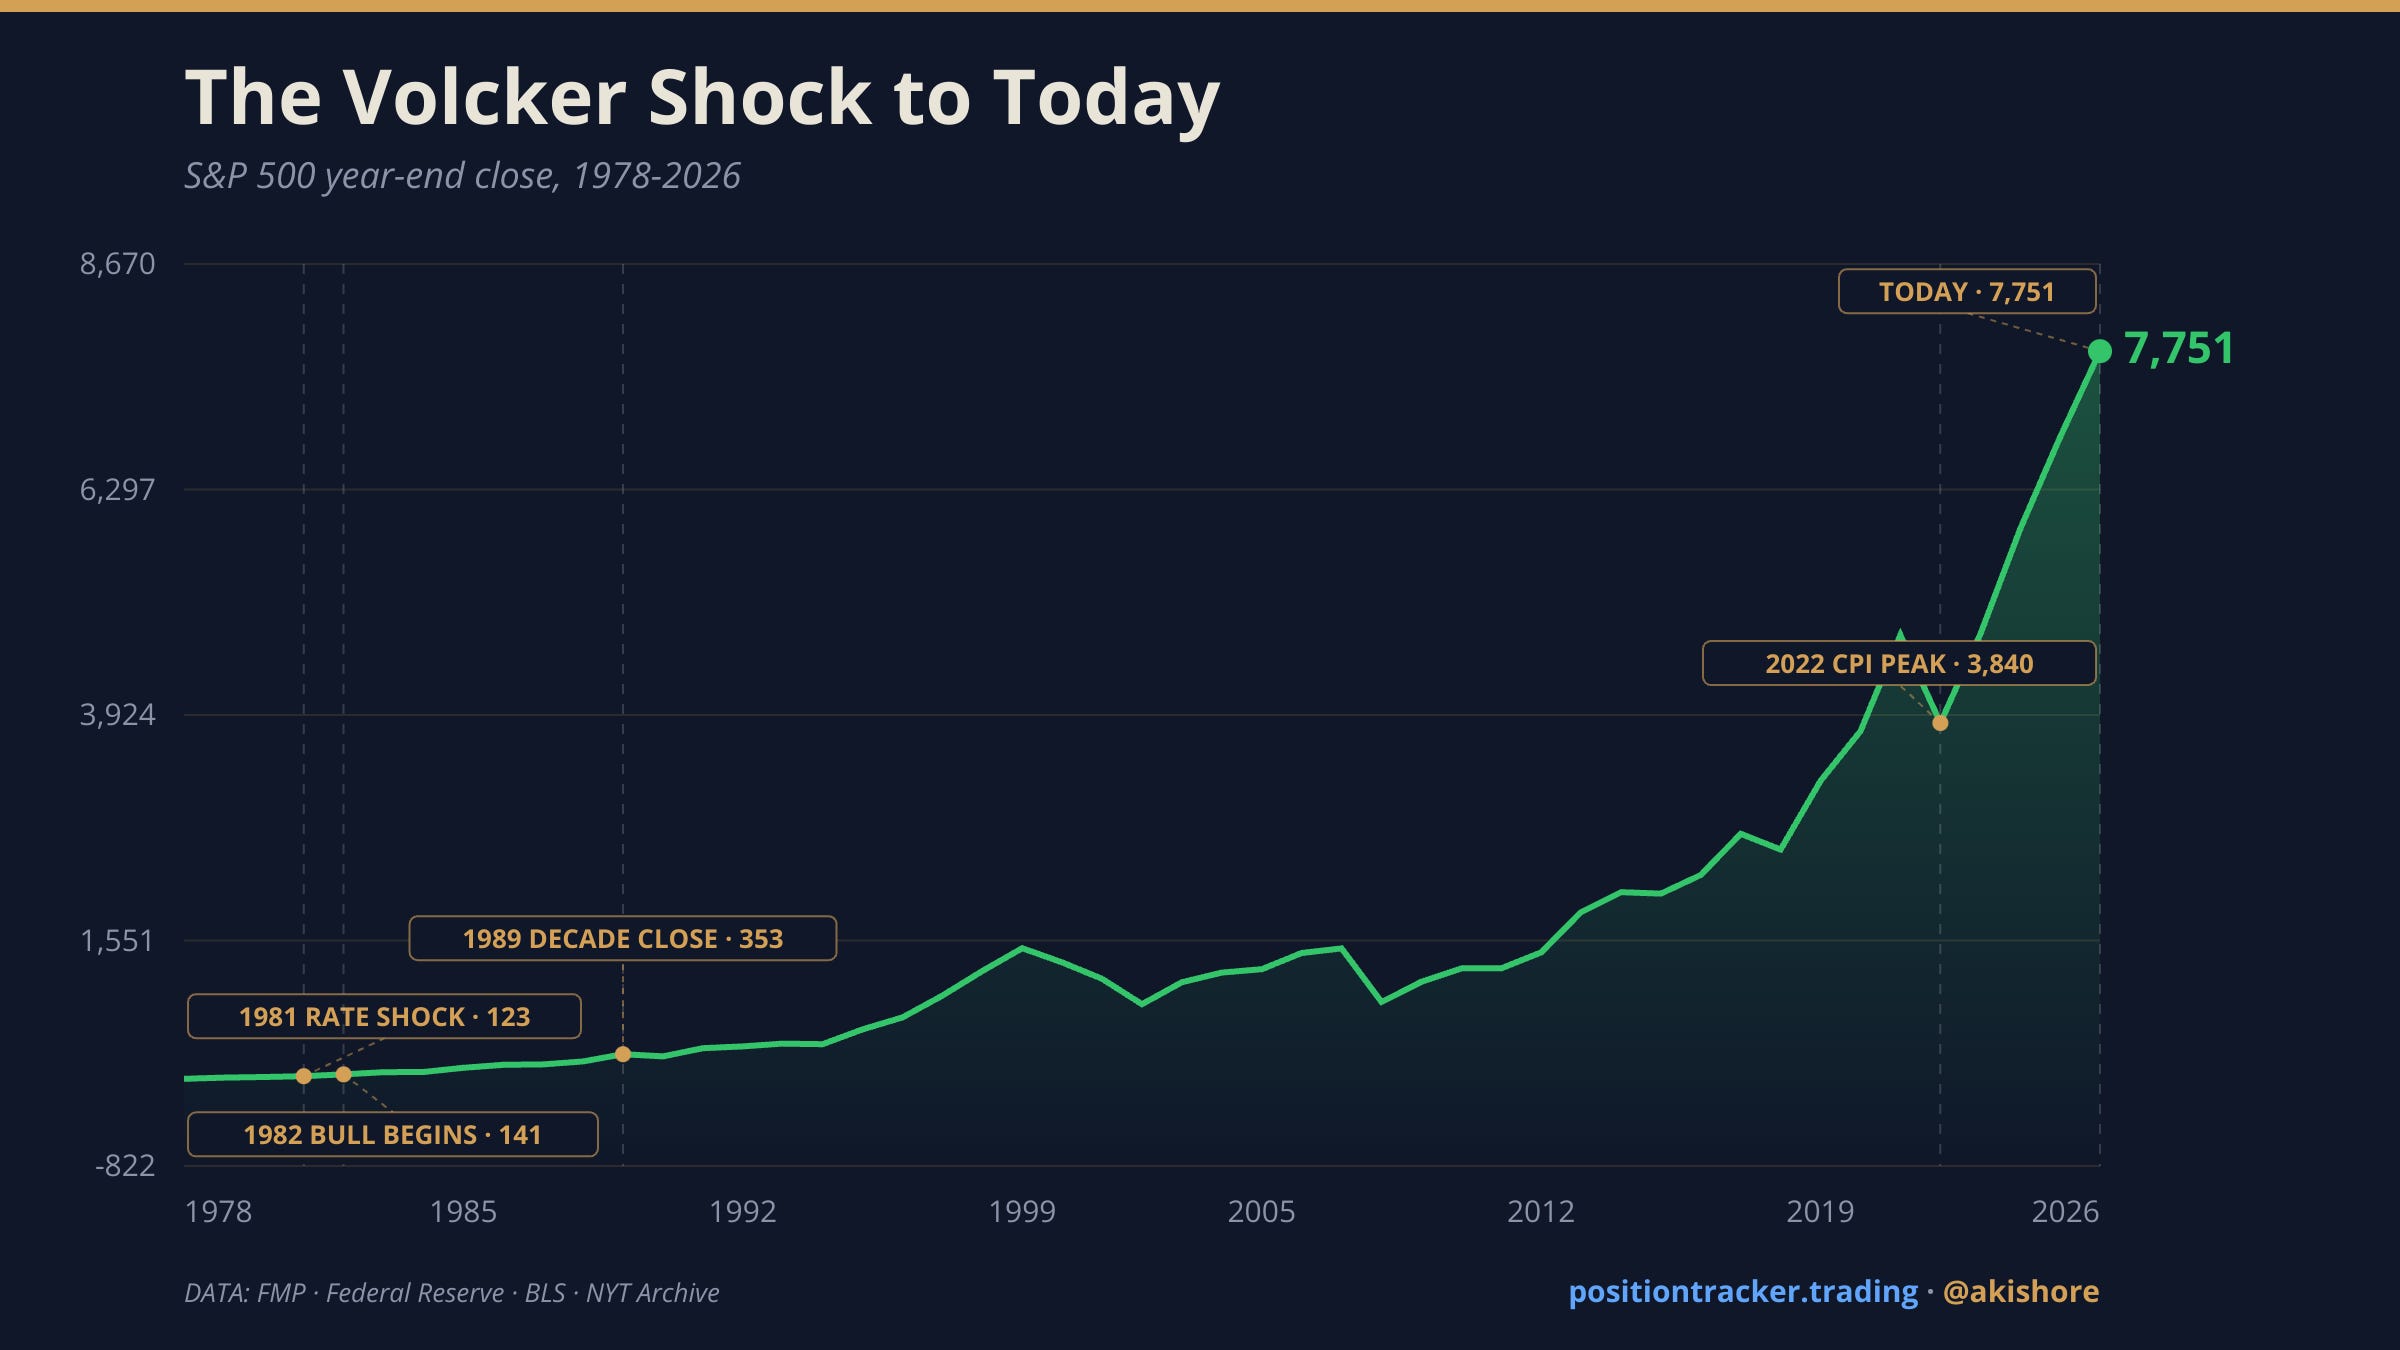
In June 1981, the Federal Reserve pushed the Fed Funds rate to 20% to break inflation running at 14.8%, the most aggressive tightening cycle in Fed history. The market absorbed the full cost of it. The S&P 500 bottomed at 102.42 on August…