$IREN stock call: Not yet, buy zone $25 to $29
$IREN: not yet. I'd buy at $25 to $29, not $34.
55% off the $76.87 high
24% below the 200-day
$702.6M net loss in FY26
I think it retests the July low first because the Sep bounce failed at $49 and the cash burn means more dilution.
Not financial advice
Bear case: SemiAnalysis called IREN's Prince George and Mackenzie sites in B.C. the worst in the industry last week, citing multi-day outages and storage failures. The report naming Anthropic as its mystery AI customer is unconfirmed by both companies. Debt was $7.84B at June 30.
Chart + wave read: I count $5.13 in Apr 2025 to $76.87 in Nov 2025 as 5 waves up. Since then it's a W-X-Y correction: W to $30.76, X to $70.71, a to $28.93 in July and b stalled at $49.37. c is now underway. If c is 0.618 of a it lands near $23.55, so $25 to $29 is my zone.
The bull case is real. FY26 revenue was $707M (up 41%) and IREN has $4B of contracted ARR for 2026 capacity. Microsoft signed a 5-year $9.7B deal for 200 MW at Childress, Texas and the first of 4 halls is delivered. Consensus still sees a loss in FY27 though.
My plan: no buying at $34. I'd start small near $29 and add near $25 if Horizons 2 to 4 deliver in Q4 and the B.C. complaints get answered. A close below $23.50 means I wait. A close back above the 200-day near $46 would also change my mind.
Sources: FMP: $IREN quote, 50/200-day, price history, income, balance sheet, cash flow and estimates (Oct 13, 2026) · IREN FY26 results (SEC exhibit): $4B contracted ARR, Horizon 1 delivered to Microsoft, Horizons 2-4 Q4 2026 · GlobeNewswire: IREN Reports FY26 Results (Aug 27, 2026) · IREN: $9.7B five-year Microsoft agreement, 200MW at Childress, Texas · Investing.com: SemiAnalysis flags B.C. site outages, FY26 net loss $702.6M, $7.84B debt · Startup Fortune: SemiAnalysis report, FY26 revenue $707M up 41%, Microsoft deal
Not financial advice. For informational and educational purposes only.
In July, Treasury fined a US company $200,000 because a subsidiary failed to report a $92,478 investment in a Chinese AI and robotics…
In July, Treasury fined a US company $200,000 because a subsidiary failed to report a $92,478 investment in a Chinese AI and robotics company. Treasury announced that first-ever penalty on Oct 7. It's the enforcement backdrop for the proposed rule Treasury put out on Thursday, Oct 22, and I think it tells you how seriously this program is going to…
Viral chart: global stocks down ~$10T from highs, South Korea -43%; a 43% drop needs a 75% gain to recover
A chart going around X this weekend says global stock markets have lost about $10 trillion from their yearly highs, with South…
US semiconductor producer prices +26% YoY in September; at that pace chip prices double in about 3 years
US producer prices for chips and electronic components rose 26% YoY in September, the 6th…
Black Monday 1987 — 22.6% in a Day, Still the Benchmark
On October 19, 1987, the Dow fell 508 points, or 22.6%, closing at 1,738.74 versus 2,246.74 on October 16, still the Dow's worst one-day percentage…
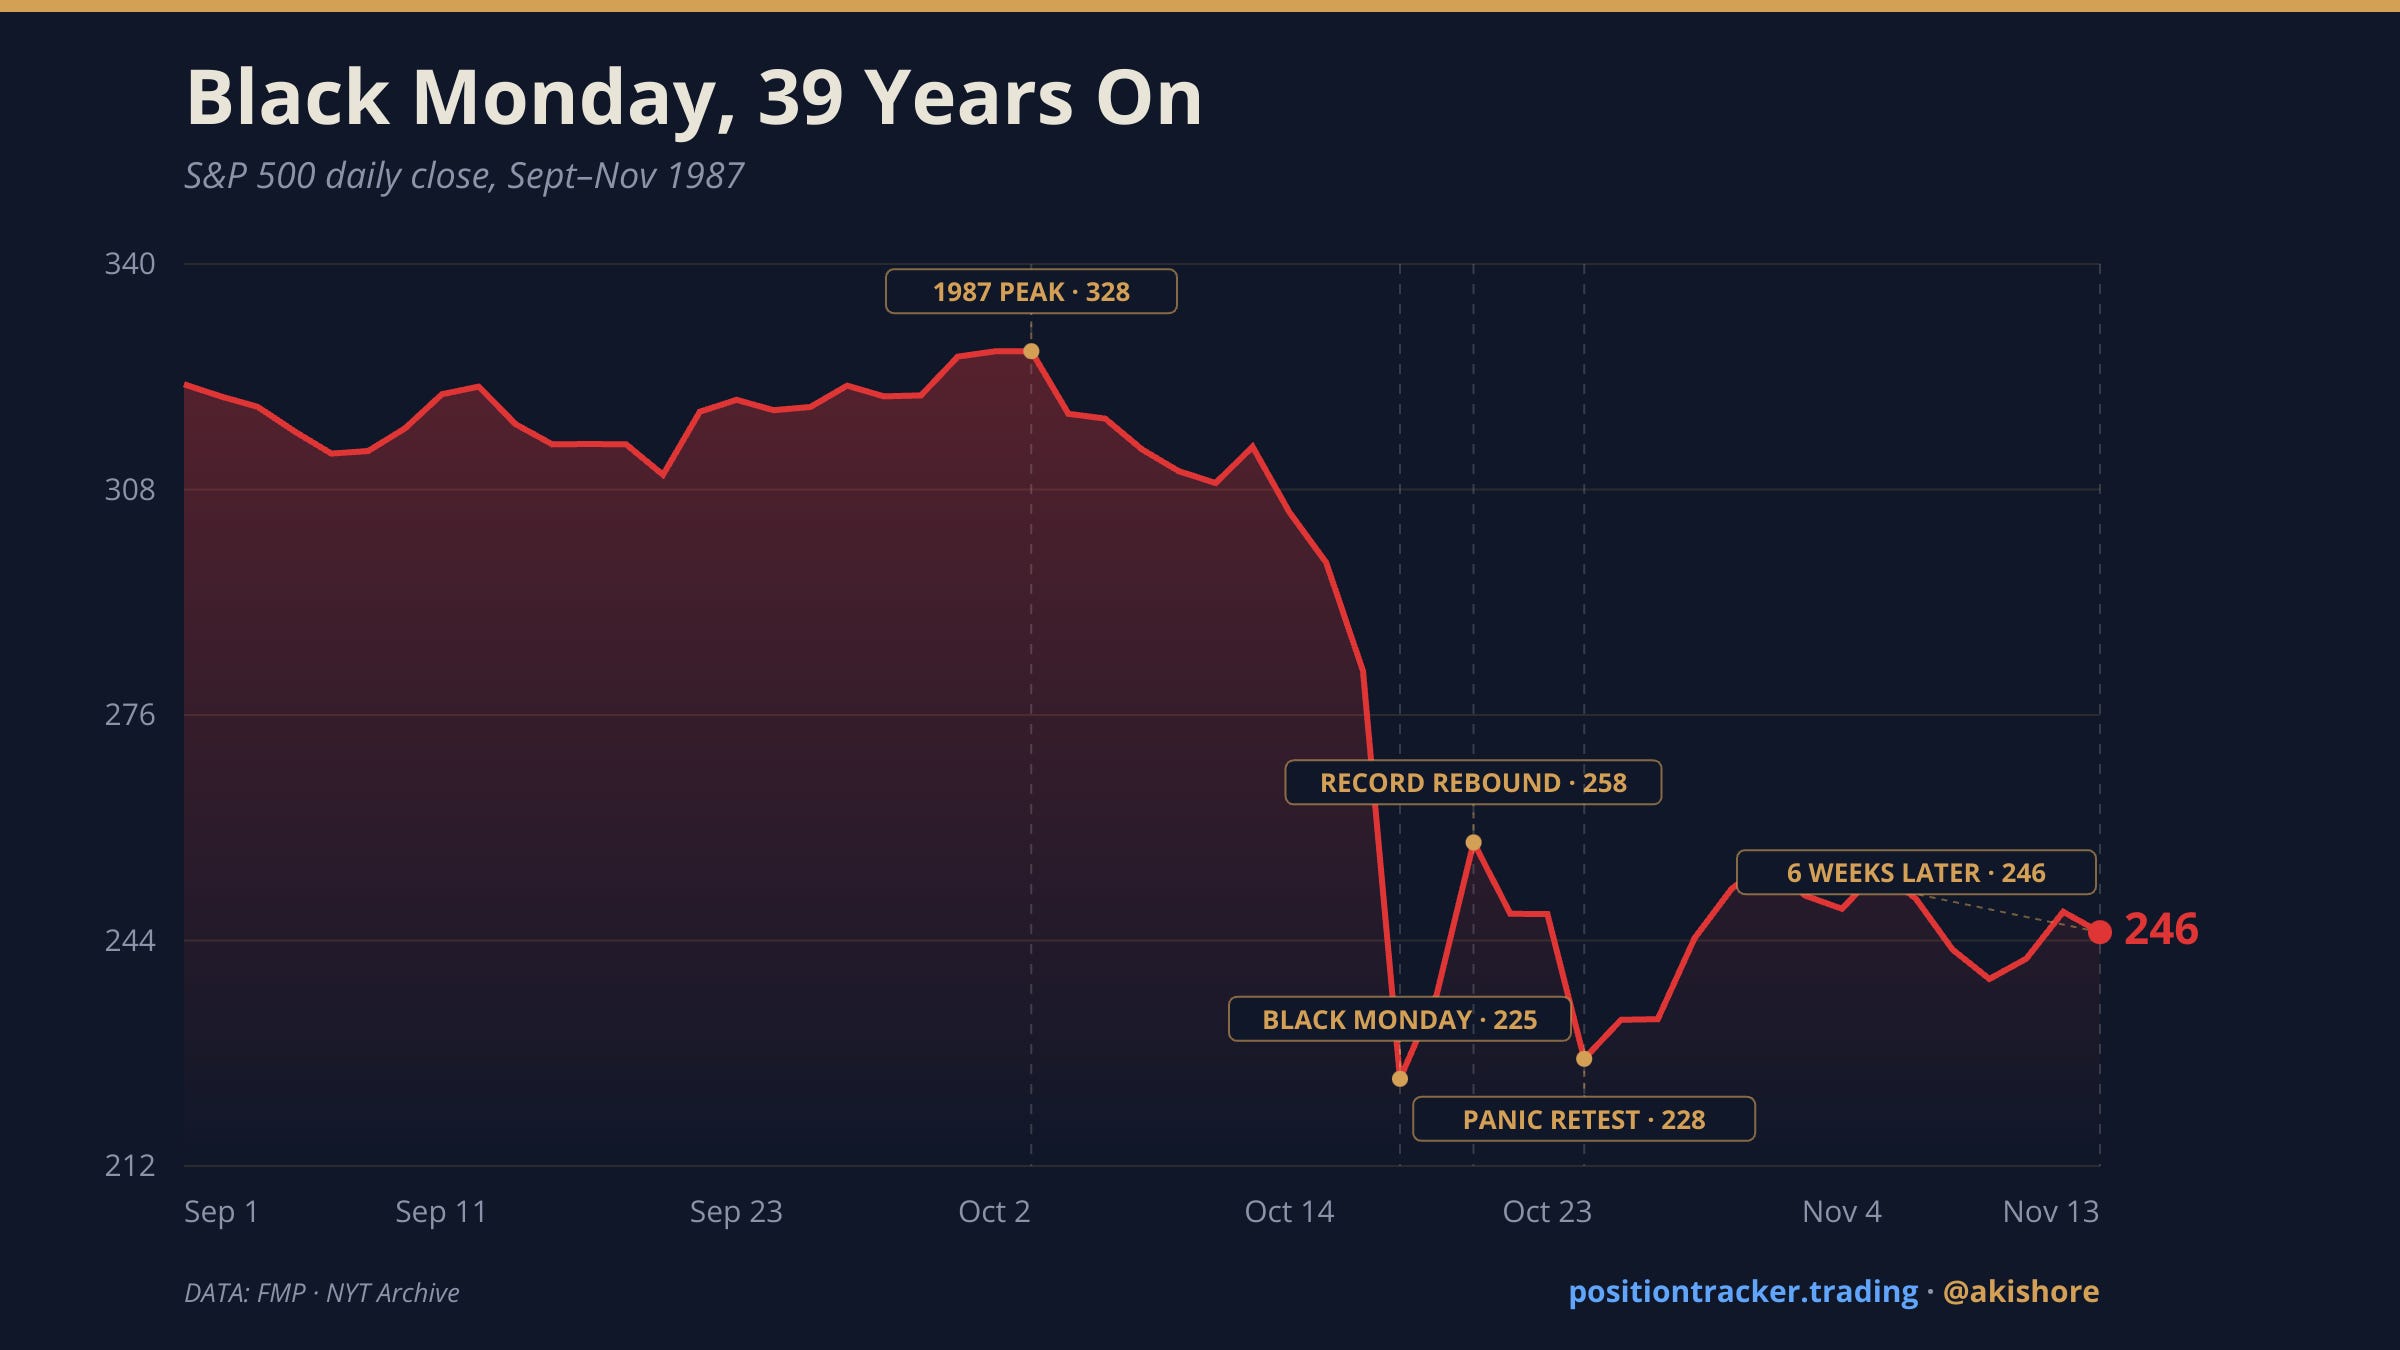
On October 19, 1987, the Dow fell 508 points, or 22.6%, closing at 1,738.74 versus 2,246.74 on October 16, still the Dow's worst one-day percentage decline on record. The S&P 500 dropped 20.47%, from 282.70 to 224.84, its own worst day. Analyses…