$META deep dive: beat, guided higher, still down. I think it's a buy
$META beat on revenue, guided Q4 above the Street and the stock is still down over 6% this morning.
Q3: revenue $64.6B (up 26%). EPS $7.40 excluding a $9.9B legal charge. Ad prices up 14% and impressions up 10%. Q4 guide $73B to $76B.
Why it's down: new nonvoting Class C shares, free cash flow went negative (-$2.1B) on $34.9B of quarterly capex and a $25B New Mexico penalty landed the same day.
I think Meta is a buy on this drop. AI is already lifting the ad business and you're paying ~22x trailing earnings for 26% growth. I'm starting here and adding near the 200-day (~$633). A close below $600 or 2027 capex outrunning revenue flips me to hold.
Not financial advice. Are you buying $META here or waiting for $622?
The chart: $META is sitting right on the 50% retrace of the Jul to Sep run ($652). The 61.8% level is $622 with the 200-day at $633 in between. Below $524 my wave count is wrong. Where would you start buying?
Sources: Meta Reports Third Quarter 2026 Results Meta IR, Oct 21 2026 · Same release on PR Newswire · 8 K summary smart goblin, filed Oct 21 4:03 PM ET · Q3 2026 earnings call transcript Muse 10M+ in US and Canada in ~6 weeks, ~25% daily use, shopping 25% of users, avg purc · Fortune, Oct 21: revenue vs $63.3B Visible Alpha est, Q4 guide vs $73.75B est, capex $34.9B vs $31B Q2 and $19.4B a year · Investing.com, Oct 21: rev est $63.33B, GAAP EPS est $3.57
Not financial advice. For informational and educational purposes only.
In July, Treasury fined a US company $200,000 because a subsidiary failed to report a $92,478 investment in a Chinese AI and robotics…
In July, Treasury fined a US company $200,000 because a subsidiary failed to report a $92,478 investment in a Chinese AI and robotics company. Treasury announced that first-ever penalty on Oct 7. It's the enforcement backdrop for the proposed rule Treasury put out on Thursday, Oct 22, and I think it tells you how seriously this program is going to…
Viral chart: global stocks down ~$10T from highs, South Korea -43%; a 43% drop needs a 75% gain to recover
A chart going around X this weekend says global stock markets have lost about $10 trillion from their yearly highs, with South…
US semiconductor producer prices +26% YoY in September; at that pace chip prices double in about 3 years
US producer prices for chips and electronic components rose 26% YoY in September, the 6th…
Black Monday 1987 — 22.6% in a Day, Still the Benchmark
On October 19, 1987, the Dow fell 508 points, or 22.6%, closing at 1,738.74 versus 2,246.74 on October 16, still the Dow's worst one-day percentage…
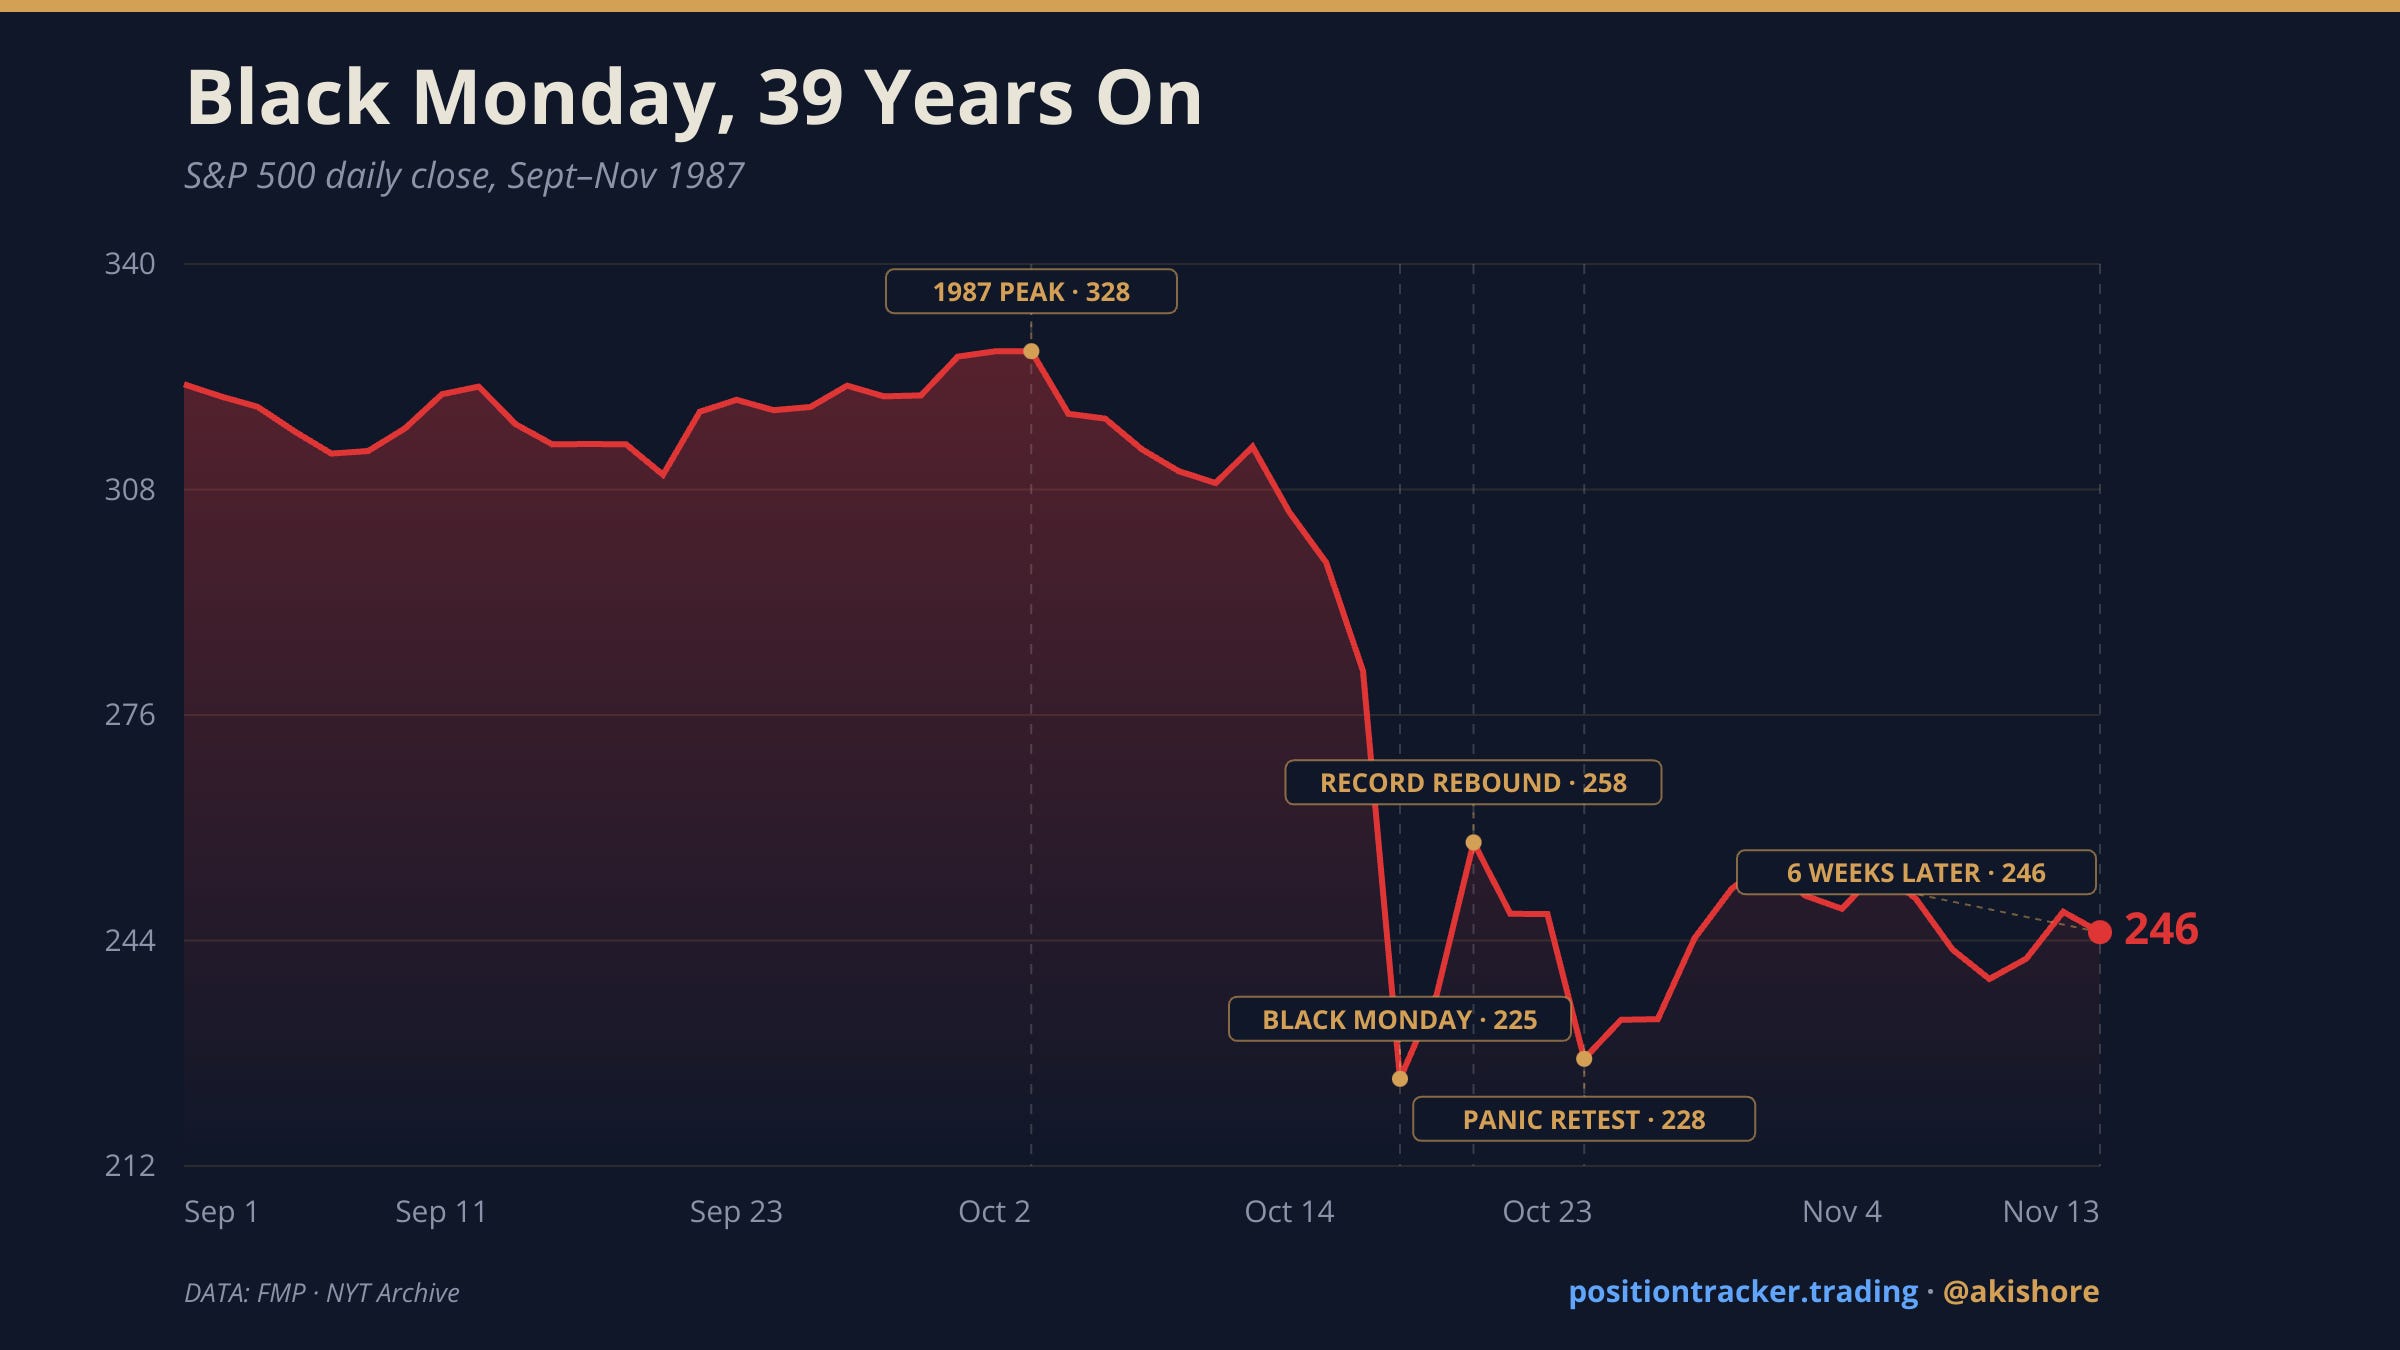
On October 19, 1987, the Dow fell 508 points, or 22.6%, closing at 1,738.74 versus 2,246.74 on October 16, still the Dow's worst one-day percentage decline on record. The S&P 500 dropped 20.47%, from 282.70 to 224.84, its own worst day. Analyses…