Nearly two-thirds of AMD's revenue now comes from data center.
Nearly two-thirds of AMD's revenue now comes from data center. That share was 64% in Q3, up from 47% a year ago, and it's the number I keep coming back to from last night's report.
The headline beat was clean. Revenue came in at $13.38B against a $13.10B consensus, up 45% year over year, and adjusted (non-GAAP) EPS was $2.09 versus $1.95 expected. Data center hit a record $8.5B, up 97%, driven by EPYC server CPUs and the launch of the Instinct MI450 GPUs. Gaming went the other way, falling 40% to $773M. Embedded grew 29% to $1.1B.
The guide is what got my attention. AMD is calling for roughly $17B in Q4, above the $16.2B analyst average, which works out to about 66% growth at the midpoint, with gross margin around 55%. Lisa Su says she expects data center processor growth to accelerate further. Shares rose more than 7% after hours from a $483.90 close, on top of a stock that has already more than doubled this year.
My read is that the customer list matters as much as the revenue line. AMD says Anthropic, Meta, Microsoft, OpenAI and Oracle Cloud Infrastructure are all running workloads on its first Helios rackscale systems. At some point the market has to stop treating AMD as the Nvidia backup and start pricing it as a core AI supplier. Is this the quarter that happens?
$AMD
Sources:
SiliconReport: https://www.siliconreport.com/amd-reports-third-quarter-earnings-beat-as-revenue-jumps-45
The Star (Reuters): https://www.thestar.com.my/tech/tech-news/2026/11/04/amd-forecasts-quarterly-revenue-above-estimates-as-data-center-growth-accelerates
Not financial advice. For informational and educational purposes only.
South Carolina just elected a Democrat to the Senate for the first time since 1998.
South Carolina just elected a Democrat to the Senate for the first time since 1998. Annie Andrews, a pediatrician, is projected to flip a Republican-held seat. Roy Cooper is projected to flip North Carolina, and Jon Ossoff is projected to win reelection in Georgia. ABC News now projects Democrats will control both…
Quote post: @BenBajarin on AMD guiding 2027 revenue growth above 80%
AMD guided Q4 revenue to about $17B, with data center up about 50% from Q3's $8.55B. That's roughly $12.8B from one segment in…
Volcker Shock & the 1980s Bull — 20% Rates to 3.75%-4.00%
In June 1981, the Federal Reserve pushed the Fed Funds rate to 20% to break inflation running at 14.8%, the most aggressive tightening cycle in Fed…
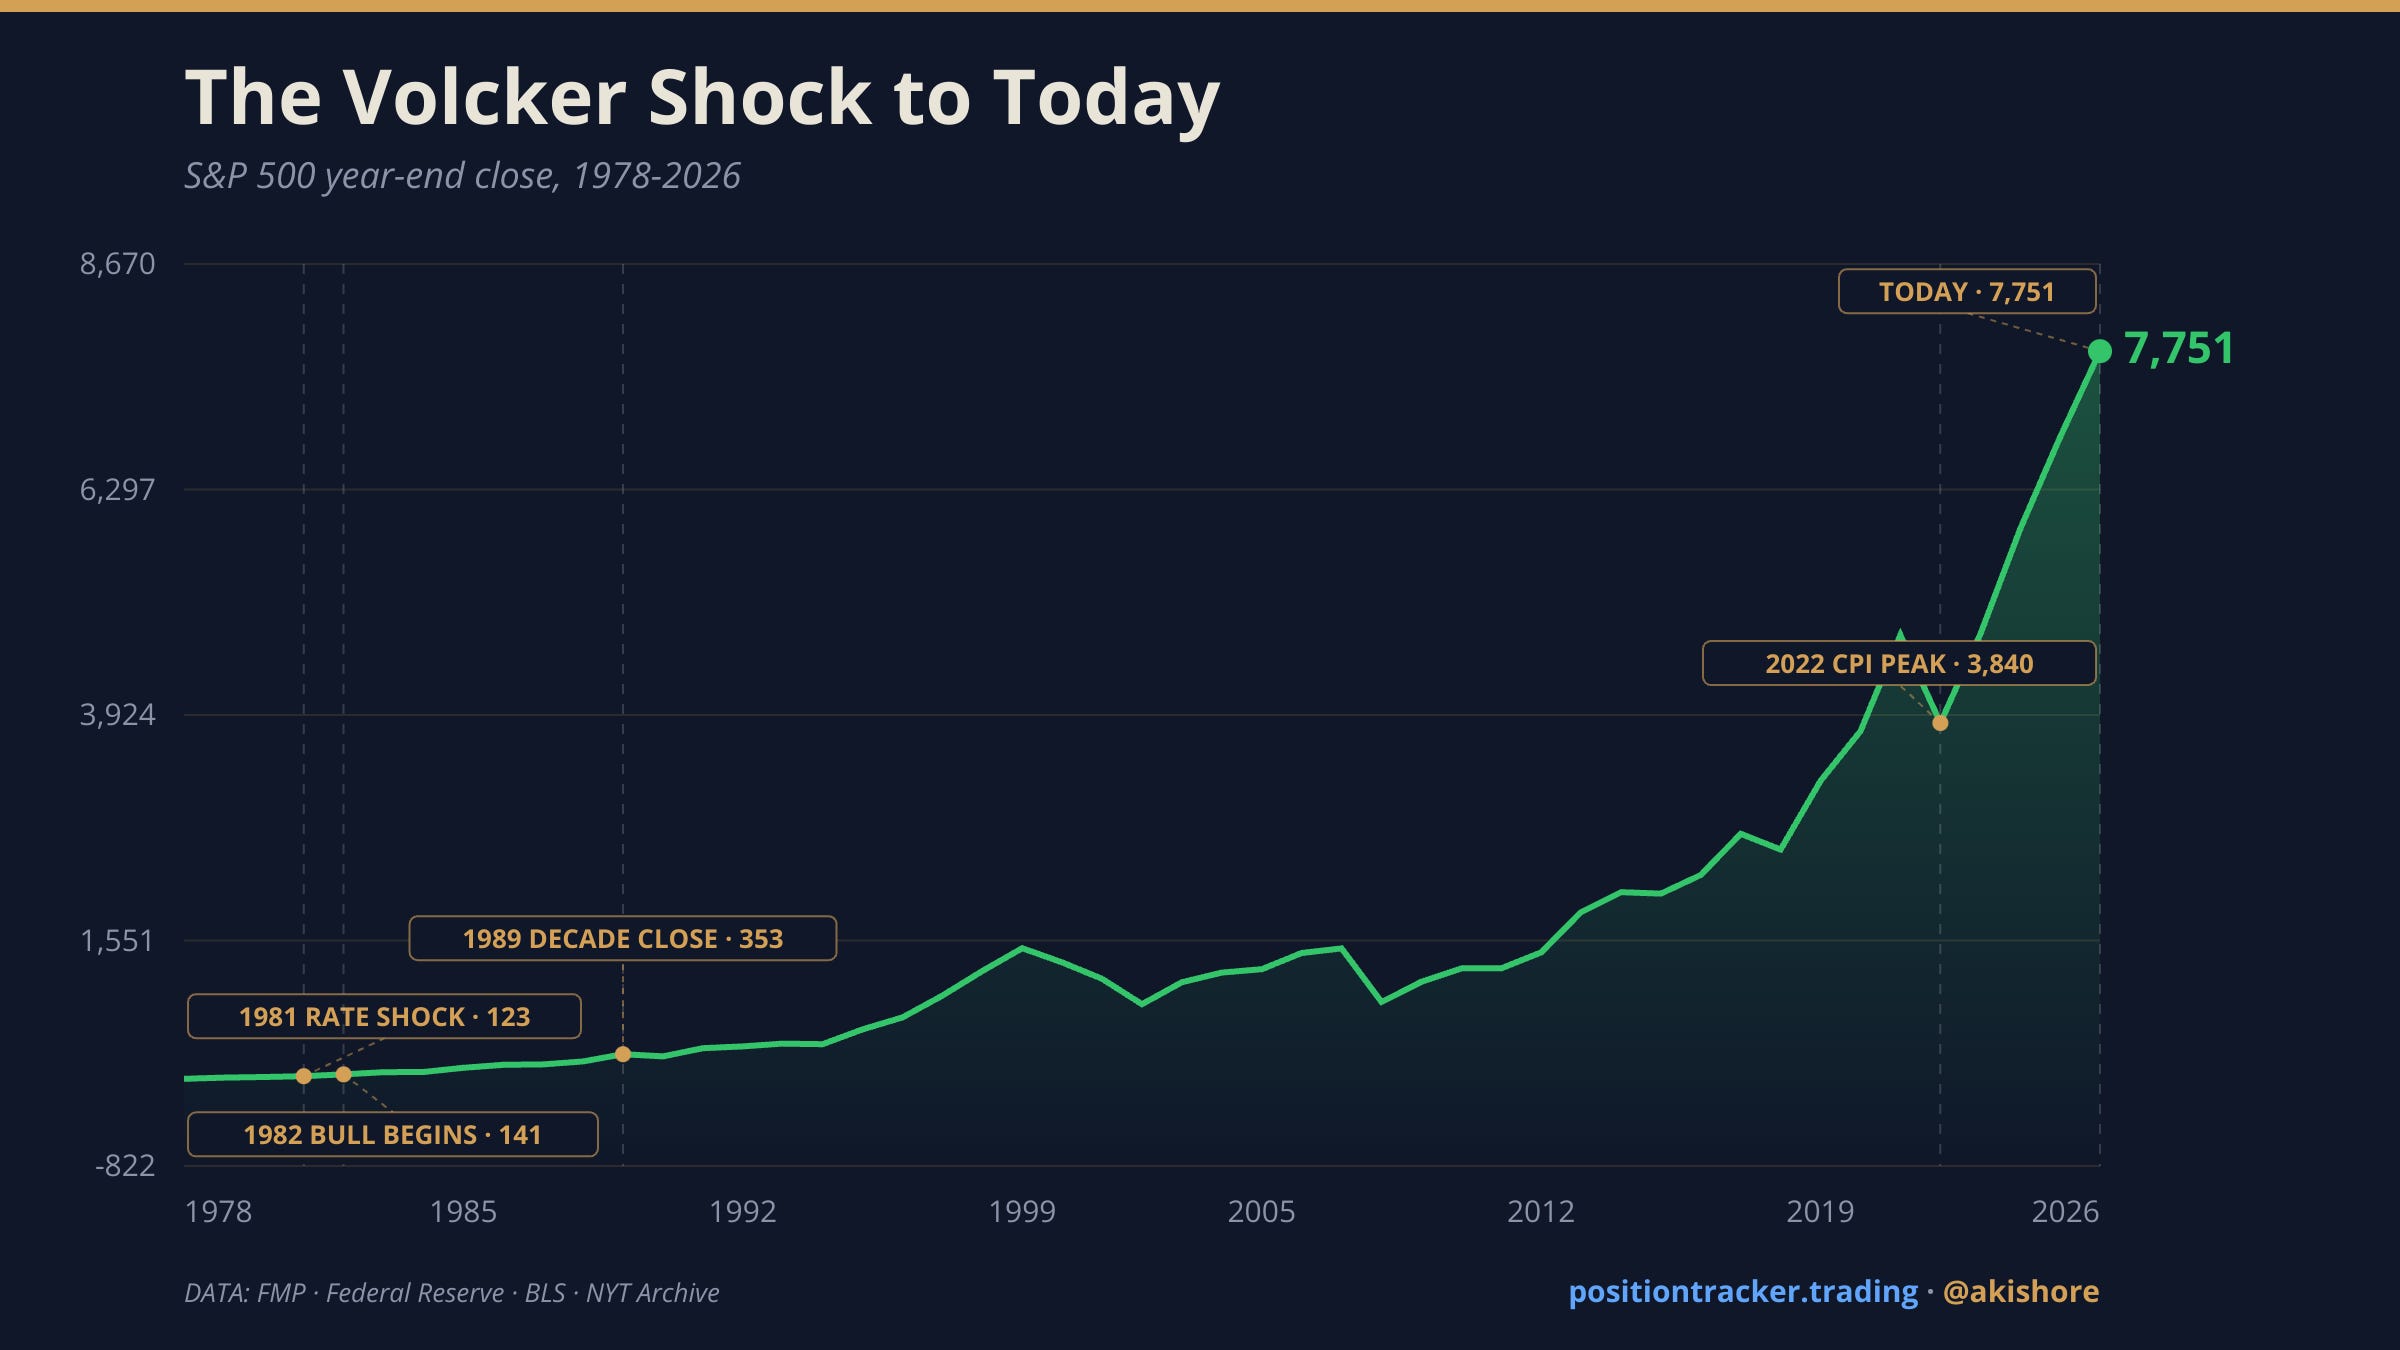
In June 1981, the Federal Reserve pushed the Fed Funds rate to 20% to break inflation running at 14.8%, the most aggressive tightening cycle in Fed history. The market absorbed the full cost of it. The S&P 500 bottomed at 102.42 on August…
Afternoon update
$LITE fell 16.57% and Marvell 10.68% this afternoon as investor skepticism grew over Marvell's $115B all-stock acquisition of Lumentum. • Lumentum…
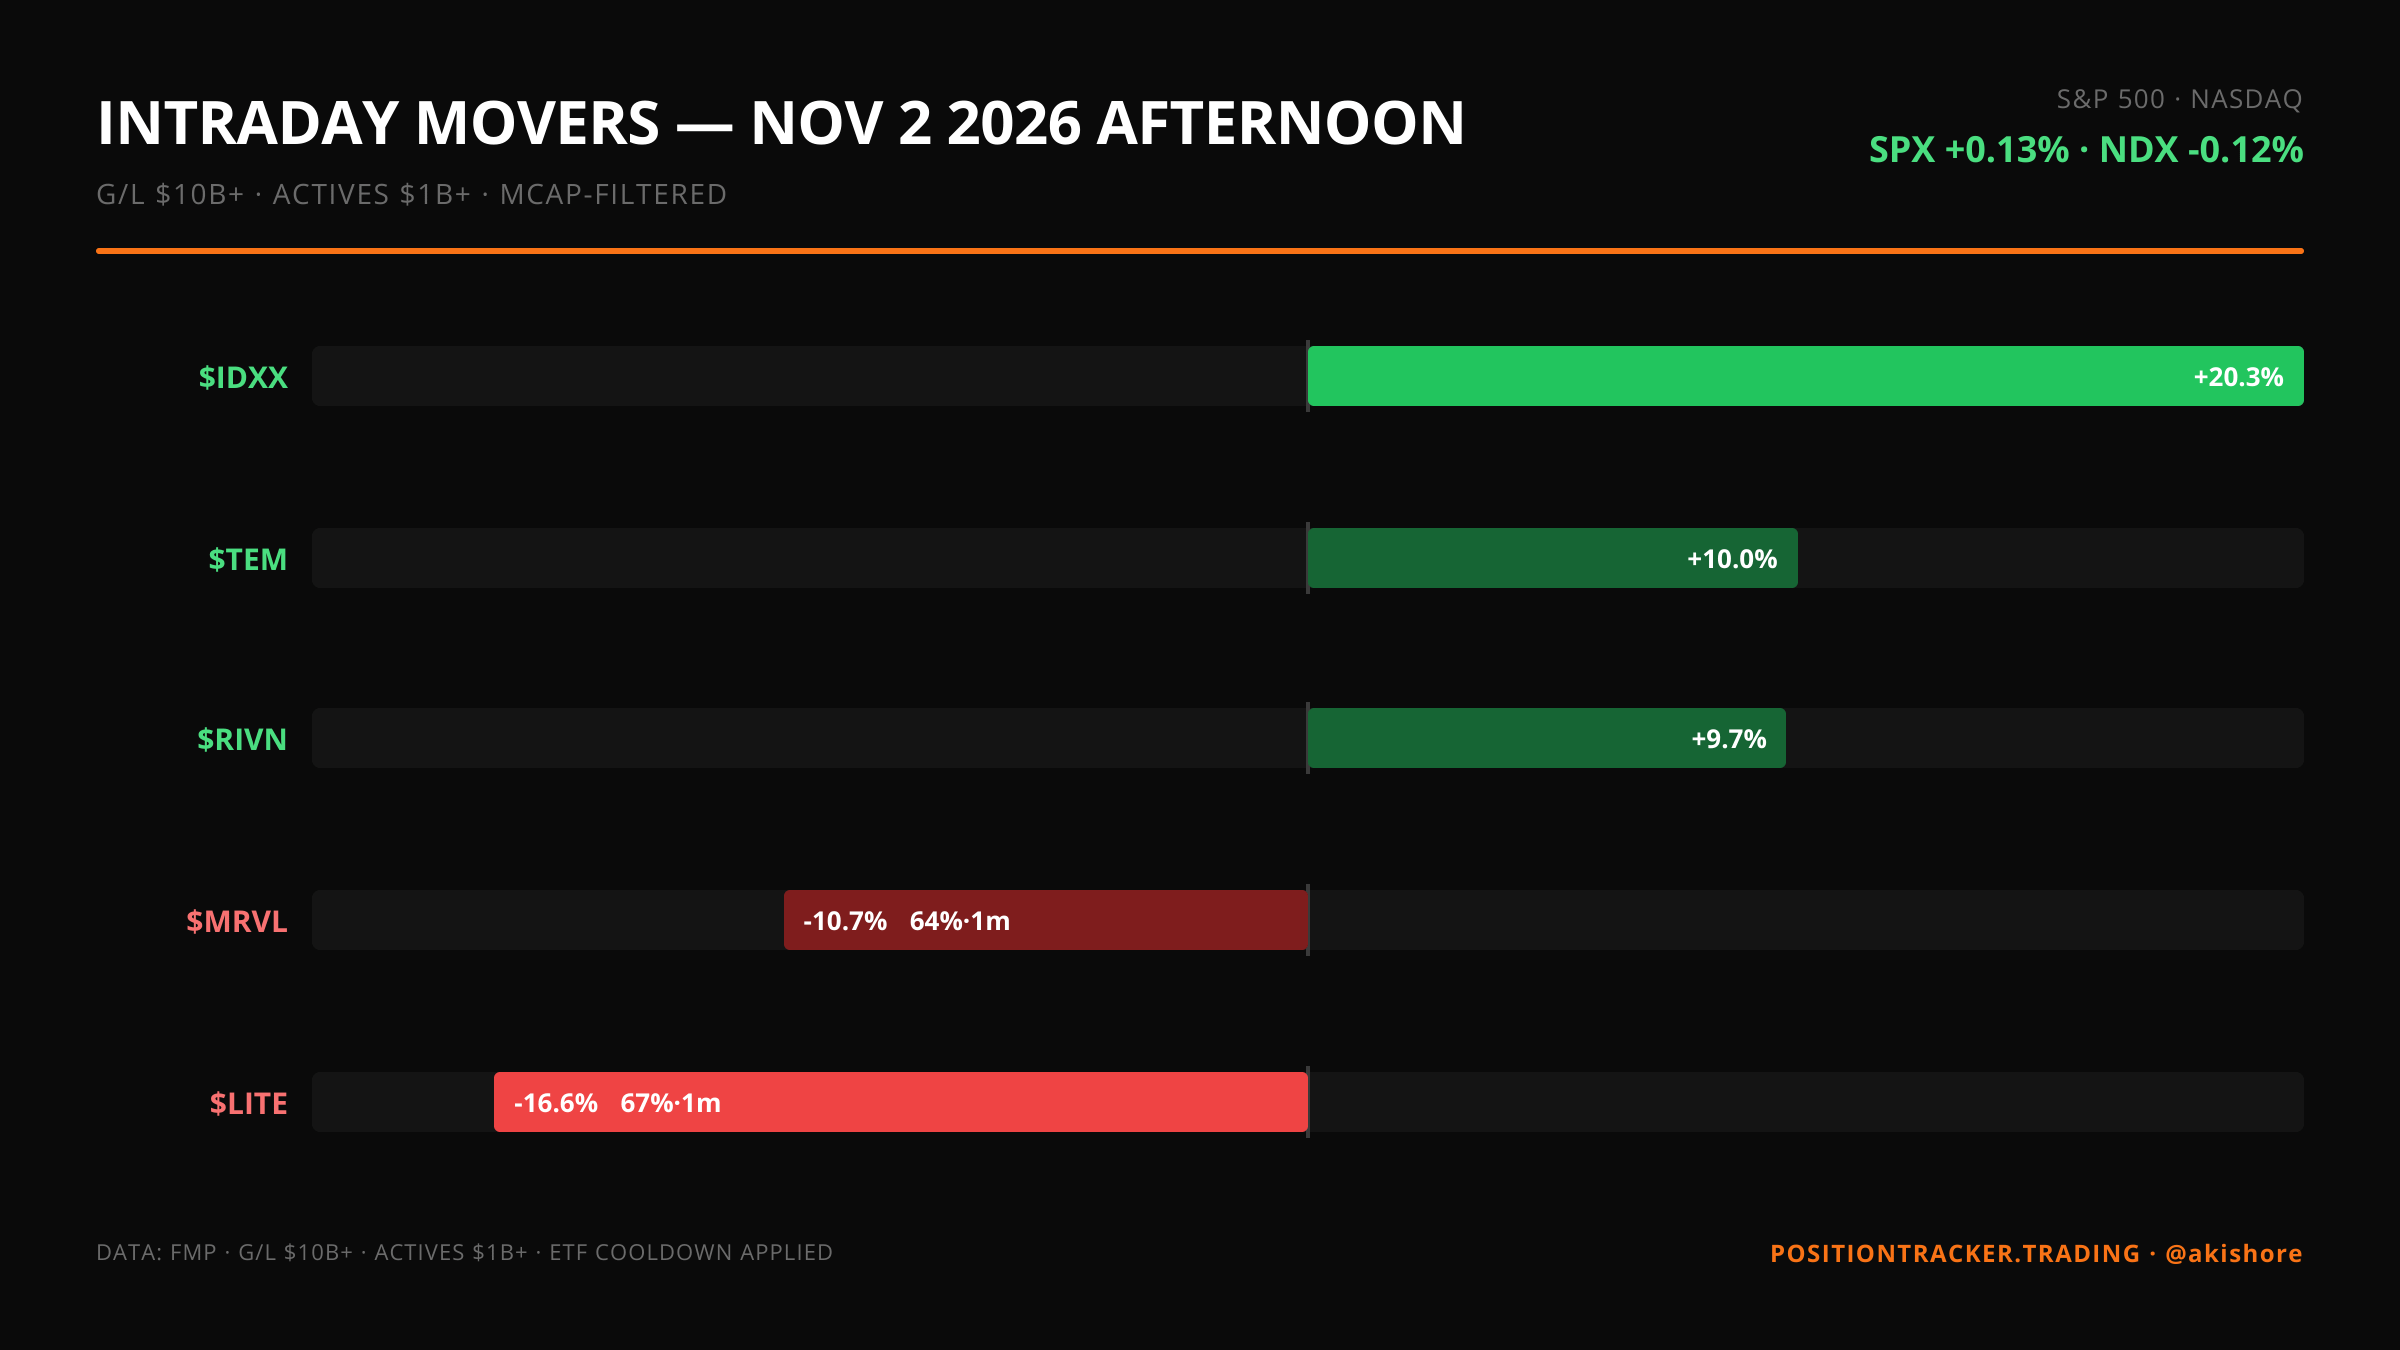
$LITE fell 16.57% and Marvell 10.68% this afternoon as investor skepticism grew over Marvell's $115B all-stock acquisition of Lumentum. Lumentum closed at $701.43 ($62.9B market cap). The deal, valued at $115B by enterprise value, gives Marvell shareholders 67% of the combined…