$NFLX stock call: Buy, accumulate $61 to $71
$NFLX: I'm a buyer at $70 and I'd add down to $61.
15% below the 200-day
Under 20x this year's EPS, half its 5-yr avg
$11B free cash flow in 12 months
I think the gloom is priced in because margins keep rising.
Buying before Tuesday's print or waiting?
Not financial advice
Bear case: viewing hours grew just 2% in the first half. This week @netflix cut about 1,000 jobs (6%) and replaced its content chief with ex-Disney exec Peter Rice. Q3 revenue is guided up 11.7% vs 17.2% a year ago. A weak print Tuesday could easily retest $61 to $65.
Chart + wave read: I count the drop from $134.12 in Jun 2025 as an ABC. A hit $75.01 in Feb, B bounced to $108.95 in Apr and C bottomed at $65.08 in Jul. The Oct 5 low at $66.54 held above it. The 61.8% retrace of the whole 2022 to 2025 run is $61.29. That's the floor of my zone.
The business: Q2 revenue was $12.6B, up 13%, with a 33.4% operating margin. 2026 guidance is $51.0B to $51.4B of revenue and a 31.5% margin, up from 29.5%. Ads are on track to roughly double to ~$3B. It bought back $9.9B of stock in the last 12 months.
My plan: a starter here and most of my cash saved for after Tuesday's report. I'd add between $61 and $65. First target is the 200-day near $83, then $91 (38.2% retrace). A weekly close below the Aug 2024 low at $58.70 means I'm wrong and I step aside.
Sources: FMP: $NFLX quote, 50/200-day, price history, P/E history, estimates, buybacks (Oct 16, 2026) · Netflix Q2 2026 shareholder letter: $12.6B revenue (+13%), 33.4% margin, 2026 guide $51.0B to $51.4B and 31.5% margin, a · CNBC: Netflix Q2 2026 earnings, revenue $12.56B, 2026 guide narrowed, ads to ~$3B · Netflix: Peter Rice named Chief Content Officer, replaces Bela Bajaria (Oct 15, 2026) · CNBC: Netflix hires Peter Rice, ~1,000 layoffs (6%), viewing up 2% in 1H, earnings Tuesday · Deadline: Bajaria exits, engagement up only 2% in 1H 2026 to 97B hours
Not financial advice. For informational and educational purposes only.
In July, Treasury fined a US company $200,000 because a subsidiary failed to report a $92,478 investment in a Chinese AI and robotics…
In July, Treasury fined a US company $200,000 because a subsidiary failed to report a $92,478 investment in a Chinese AI and robotics company. Treasury announced that first-ever penalty on Oct 7. It's the enforcement backdrop for the proposed rule Treasury put out on Thursday, Oct 22, and I think it tells you how seriously this program is going to…
Viral chart: global stocks down ~$10T from highs, South Korea -43%; a 43% drop needs a 75% gain to recover
A chart going around X this weekend says global stock markets have lost about $10 trillion from their yearly highs, with South…
US semiconductor producer prices +26% YoY in September; at that pace chip prices double in about 3 years
US producer prices for chips and electronic components rose 26% YoY in September, the 6th…
Black Monday 1987 — 22.6% in a Day, Still the Benchmark
On October 19, 1987, the Dow fell 508 points, or 22.6%, closing at 1,738.74 versus 2,246.74 on October 16, still the Dow's worst one-day percentage…
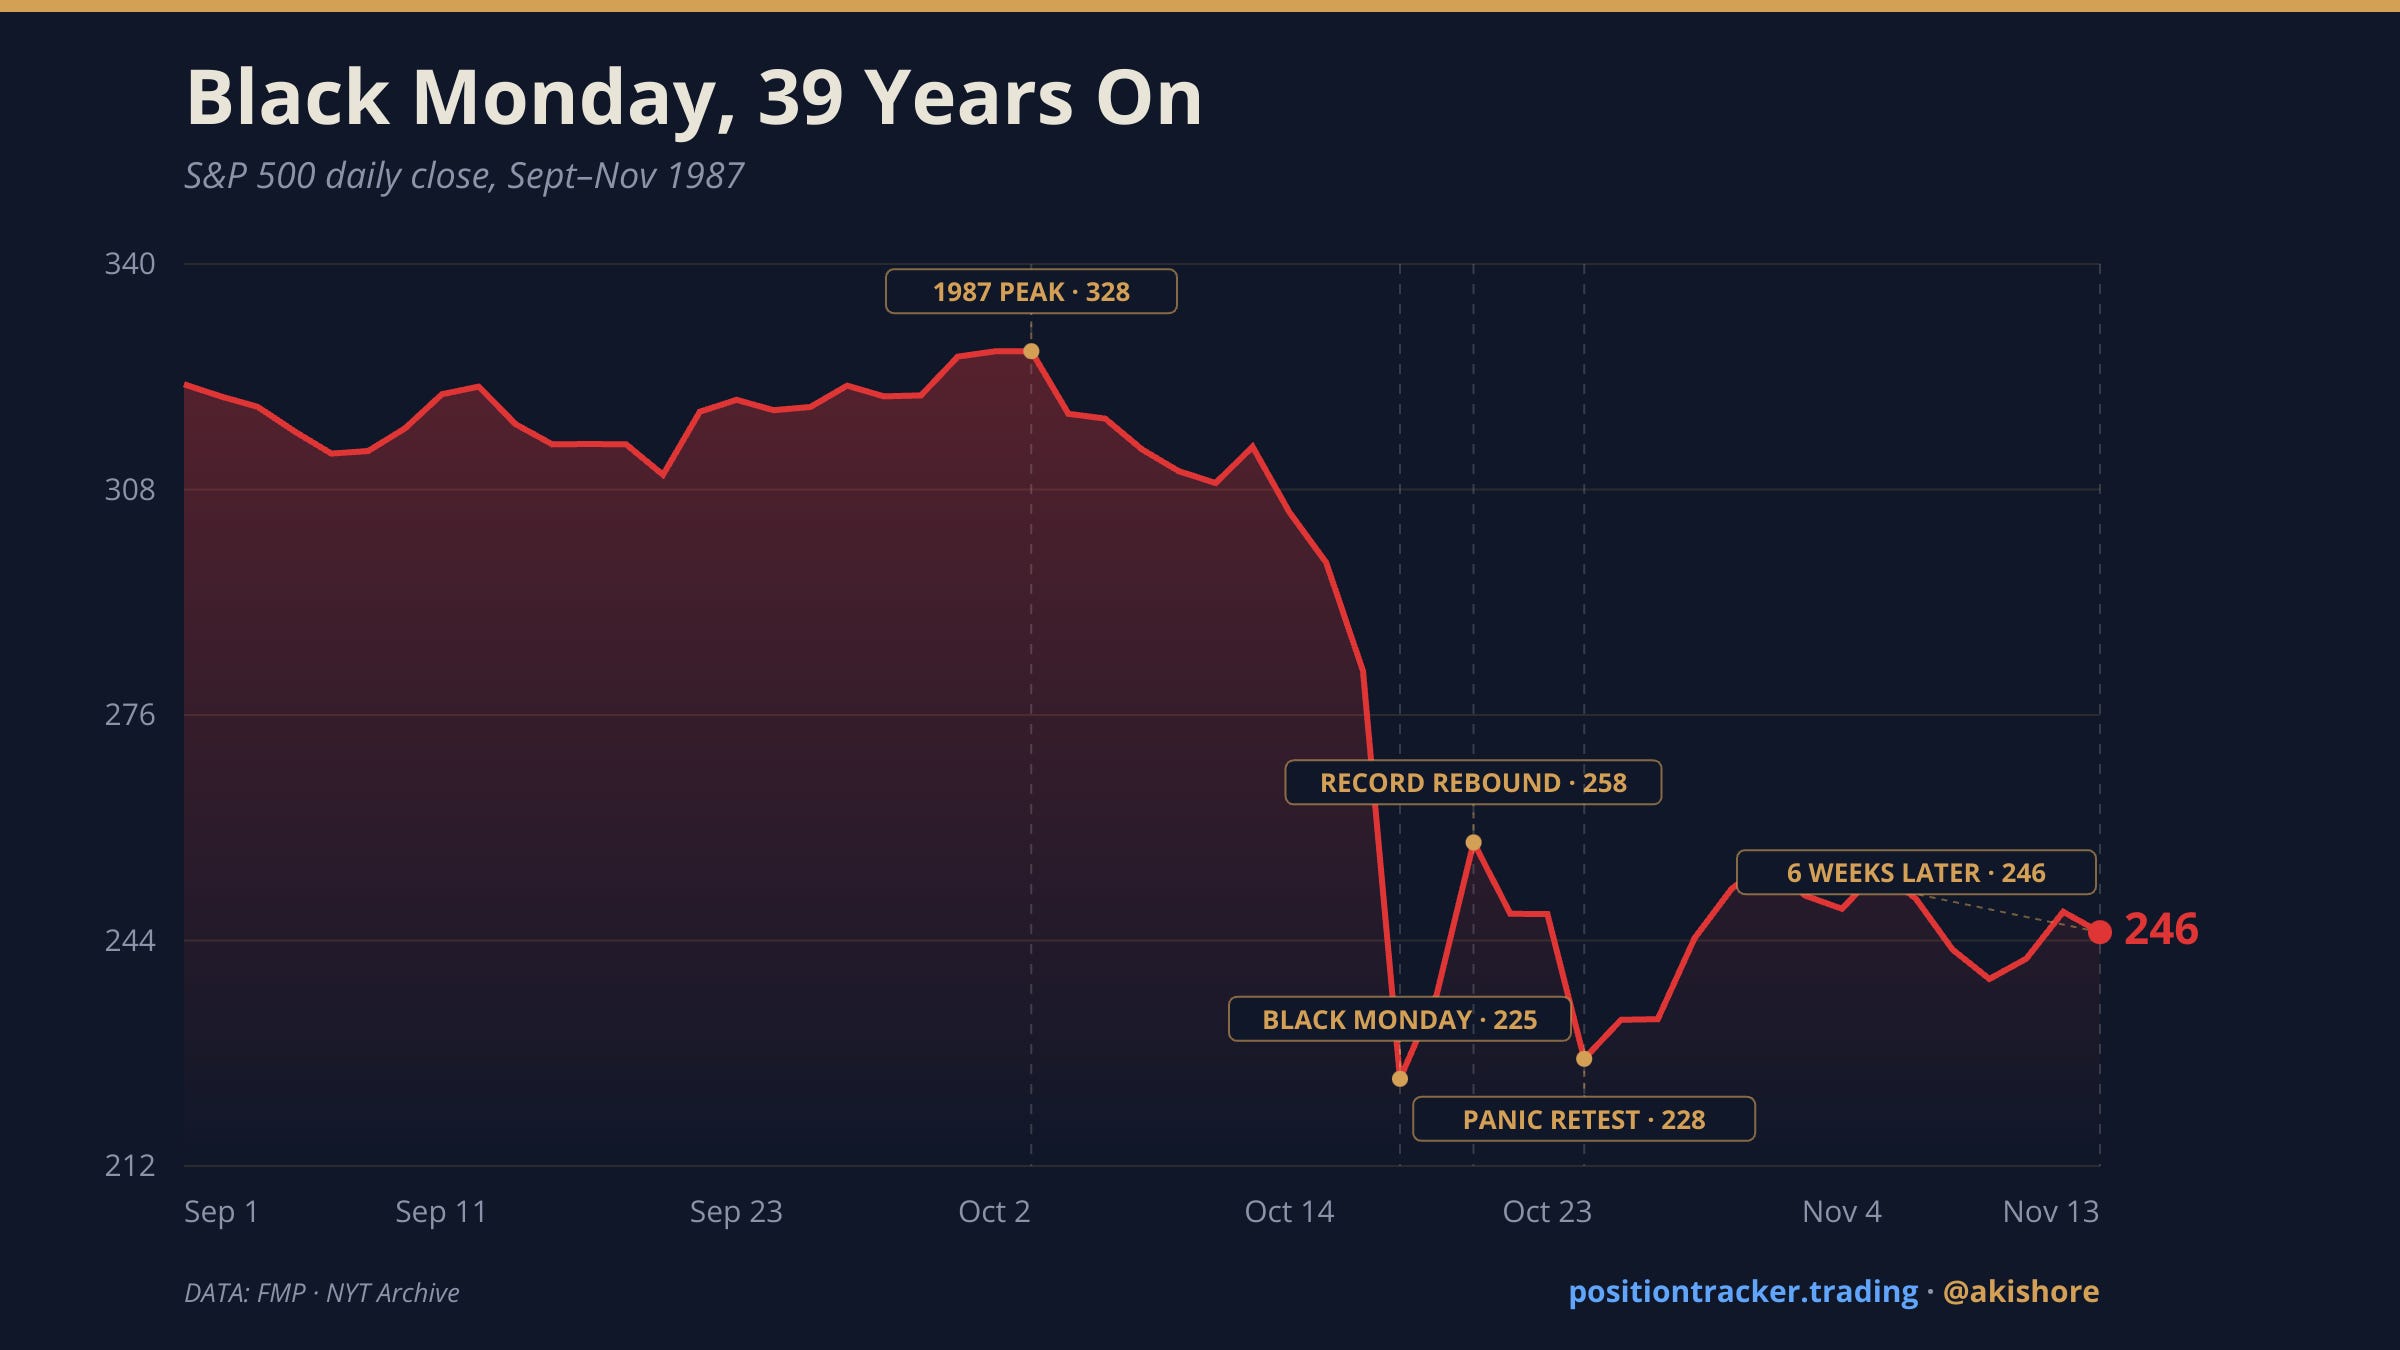
On October 19, 1987, the Dow fell 508 points, or 22.6%, closing at 1,738.74 versus 2,246.74 on October 16, still the Dow's worst one-day percentage decline on record. The S&P 500 dropped 20.47%, from 282.70 to 224.84, its own worst day. Analyses…