Roughly 87x forward earnings after losing more than half its value.
Roughly 87x forward earnings after losing more than half its value. Arm holders are the ones most exposed on November 4, because at this multiple a merely good quarter may not be enough.
- $ARM was at $212.78 in pre-market on October 26, up 1.16% from its October 23 regular-session close of $210.33. That October 23 close is 53.5% below the $452.70 52-week high, yet the stock is still up 92.4% YTD per 24/7 Wall St.
- The fiscal Q1 2027 operating numbers hold up. Revenue was $1.289B, royalties rose 22% to $715M, and data center royalties more than doubled year over year.
- Arm says AGI CPU silicon demand has topped $2B, with Meta as lead partner. That is a company figure for demand, and I want to see how much of it turns into revenue.
- Management guided fiscal Q2 to $1.38B in revenue and $0.47 non-GAAP EPS, with results scheduled for November 4. GAAP EPS last quarter was $0.25 against $0.45 non-GAAP, so I'm watching the cash flow more than the adjusted line.
A stock that is still up 92% for the year looks to me like a pullback in a richly priced growth name. I would size anything around the guidance print, and I could be wrong if data center royalties keep compounding like this.
Source:
24/7 Wall St: https://247wallst.com/investing/2026/10/26/bulls-insist-arms-trio-of-multipliers-justify-its-sky-high-valuation/
Not financial advice. For informational and educational purposes only.
Anthropic targets November 16 IPO week, could raise ~$100B at up to $2T valuation
Anthropic is aiming to go public the week of November 16 and could raise roughly…
Video explainer: @AnthropicAI just made its IPO filing public. $16.3B in revenue next to an $80.7B loss in just six months.
@AnthropicAI just made its IPO filing public. $16.3B in revenue next to an $80.7B loss in just six months. It plans to list on the @Nasdaq as $ANT with @GoldmanSachs and @MorganStanley leading. Per @CNBC marketing could start the week of Nov 9.
Energy Leads Alone as Defensives Lag
Energy led all sectors at +2.60%, more than five times the next-best gain in Information Technology (+0.49%), while eight of eleven sectors finished negative.
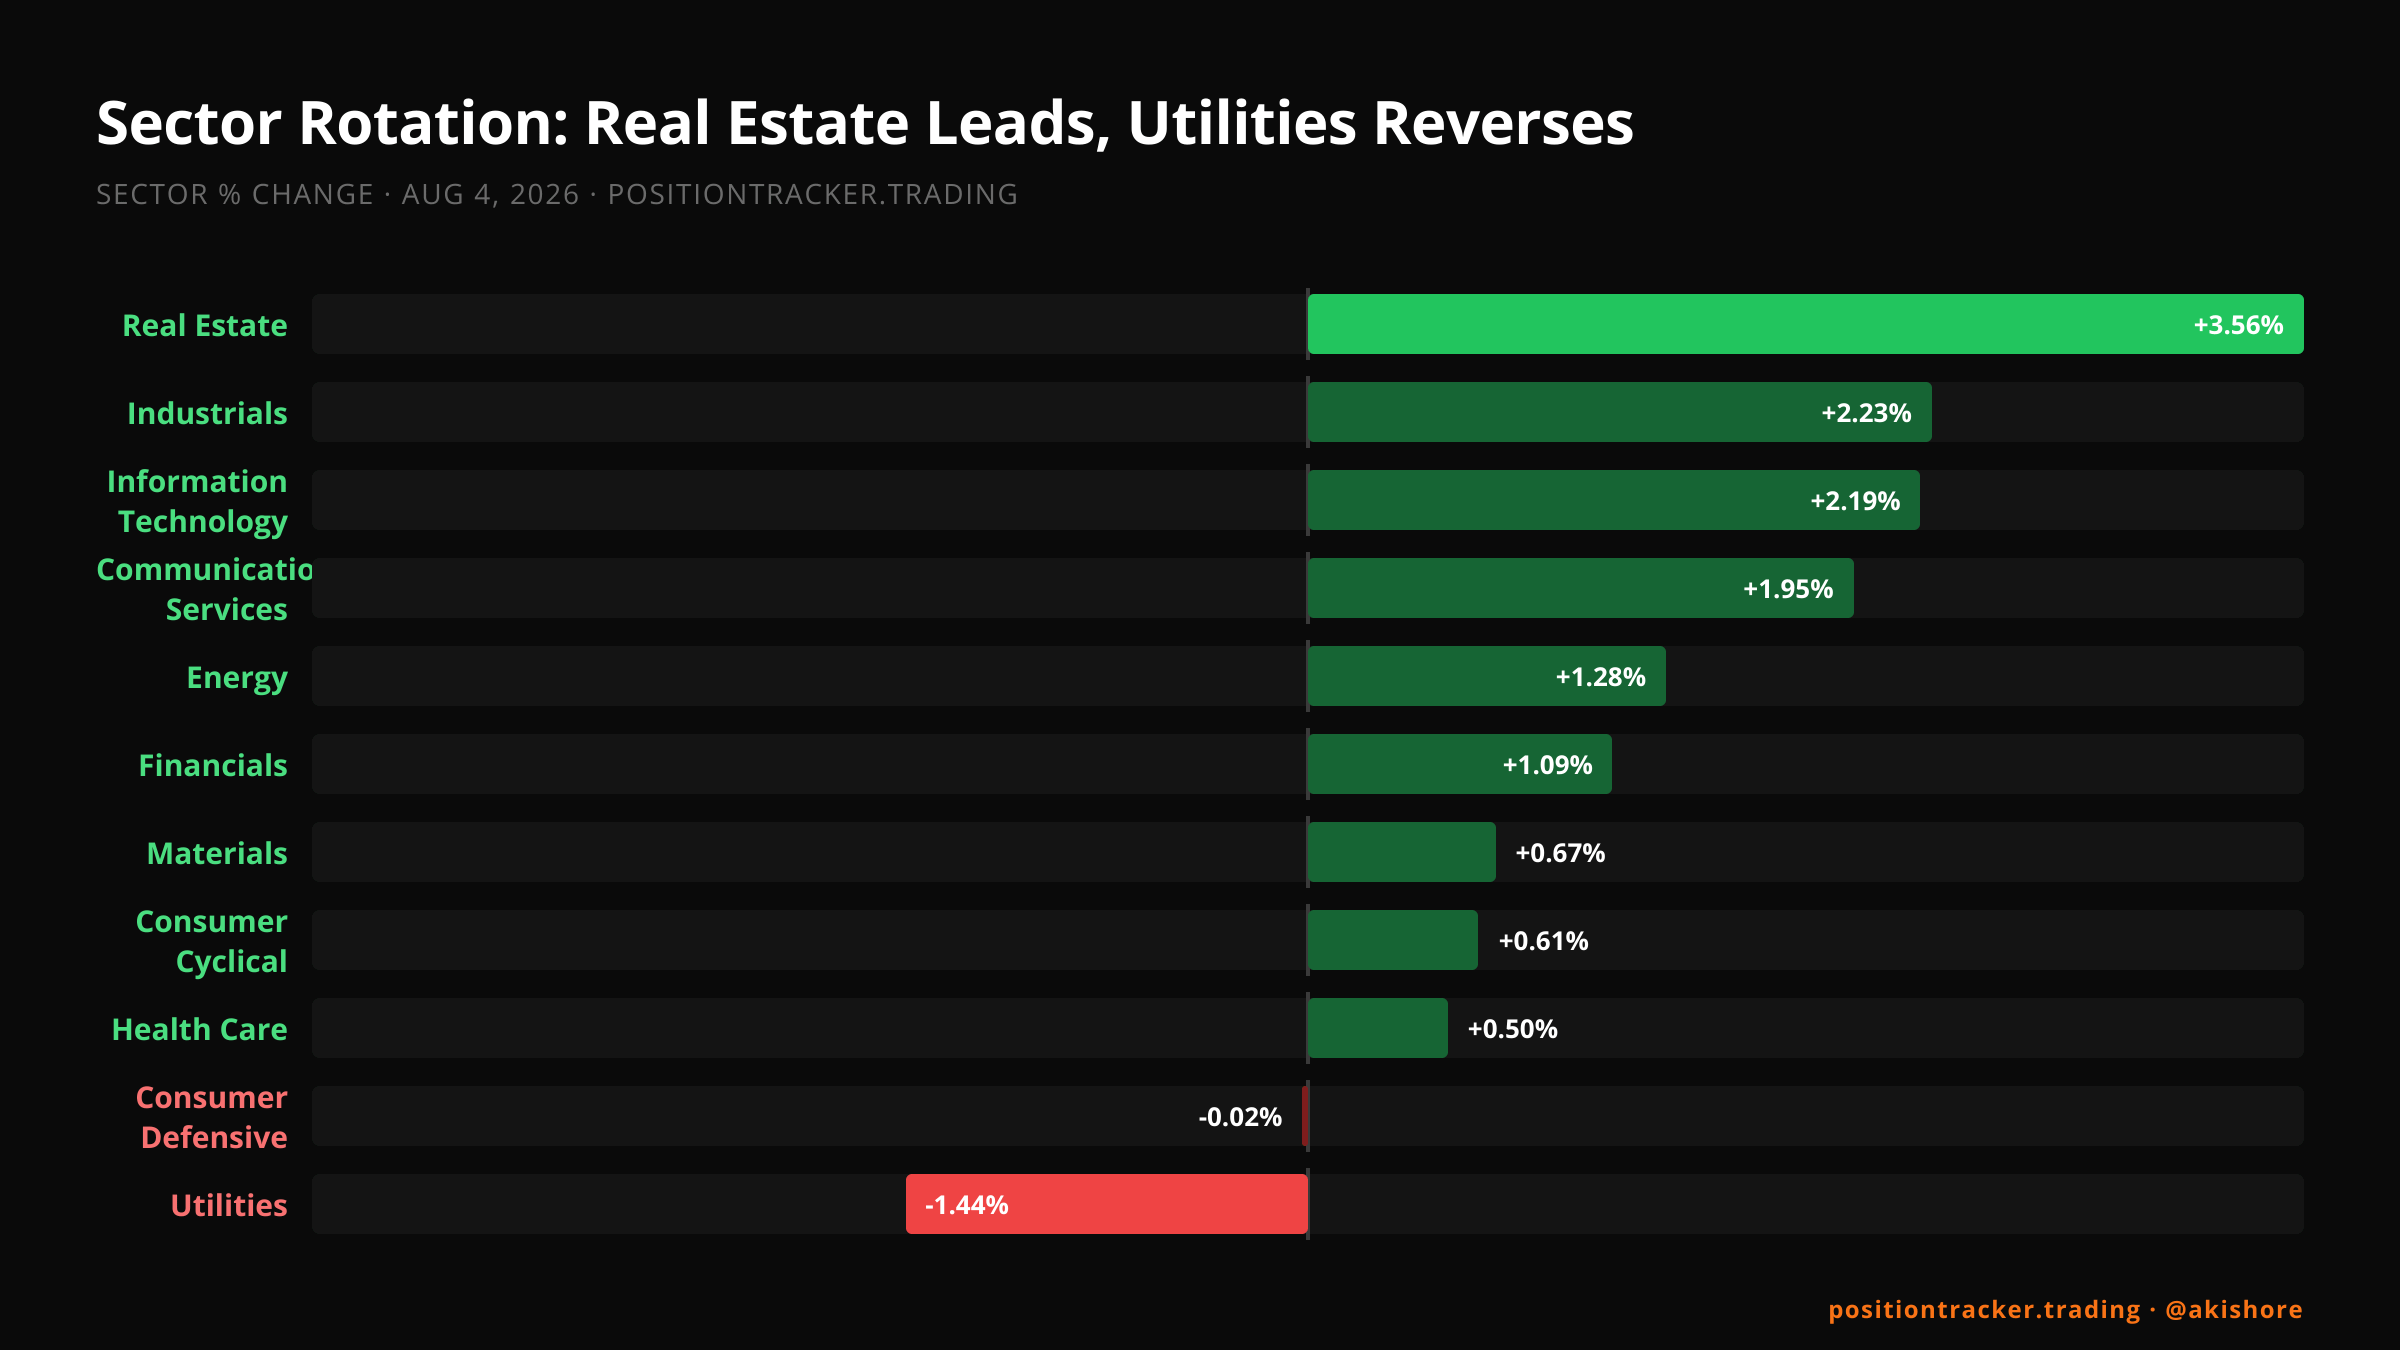
Energy returned +2.60% in Friday's session, the largest gain among all tracked sectors and more than five times the next-best, Information Technology at +0.49%. Only three of eleven sectors finished positive, with Real Estate barely in the green at +0.12%. The narrowness…
Sunday BTC/ETH research | October 25, 2026 · Sunday BTC/ETH deep dive
Sunday BTC/ETH research | October 25, 2026 BTC is $80,305.70, down 0.45% over 24 hours.
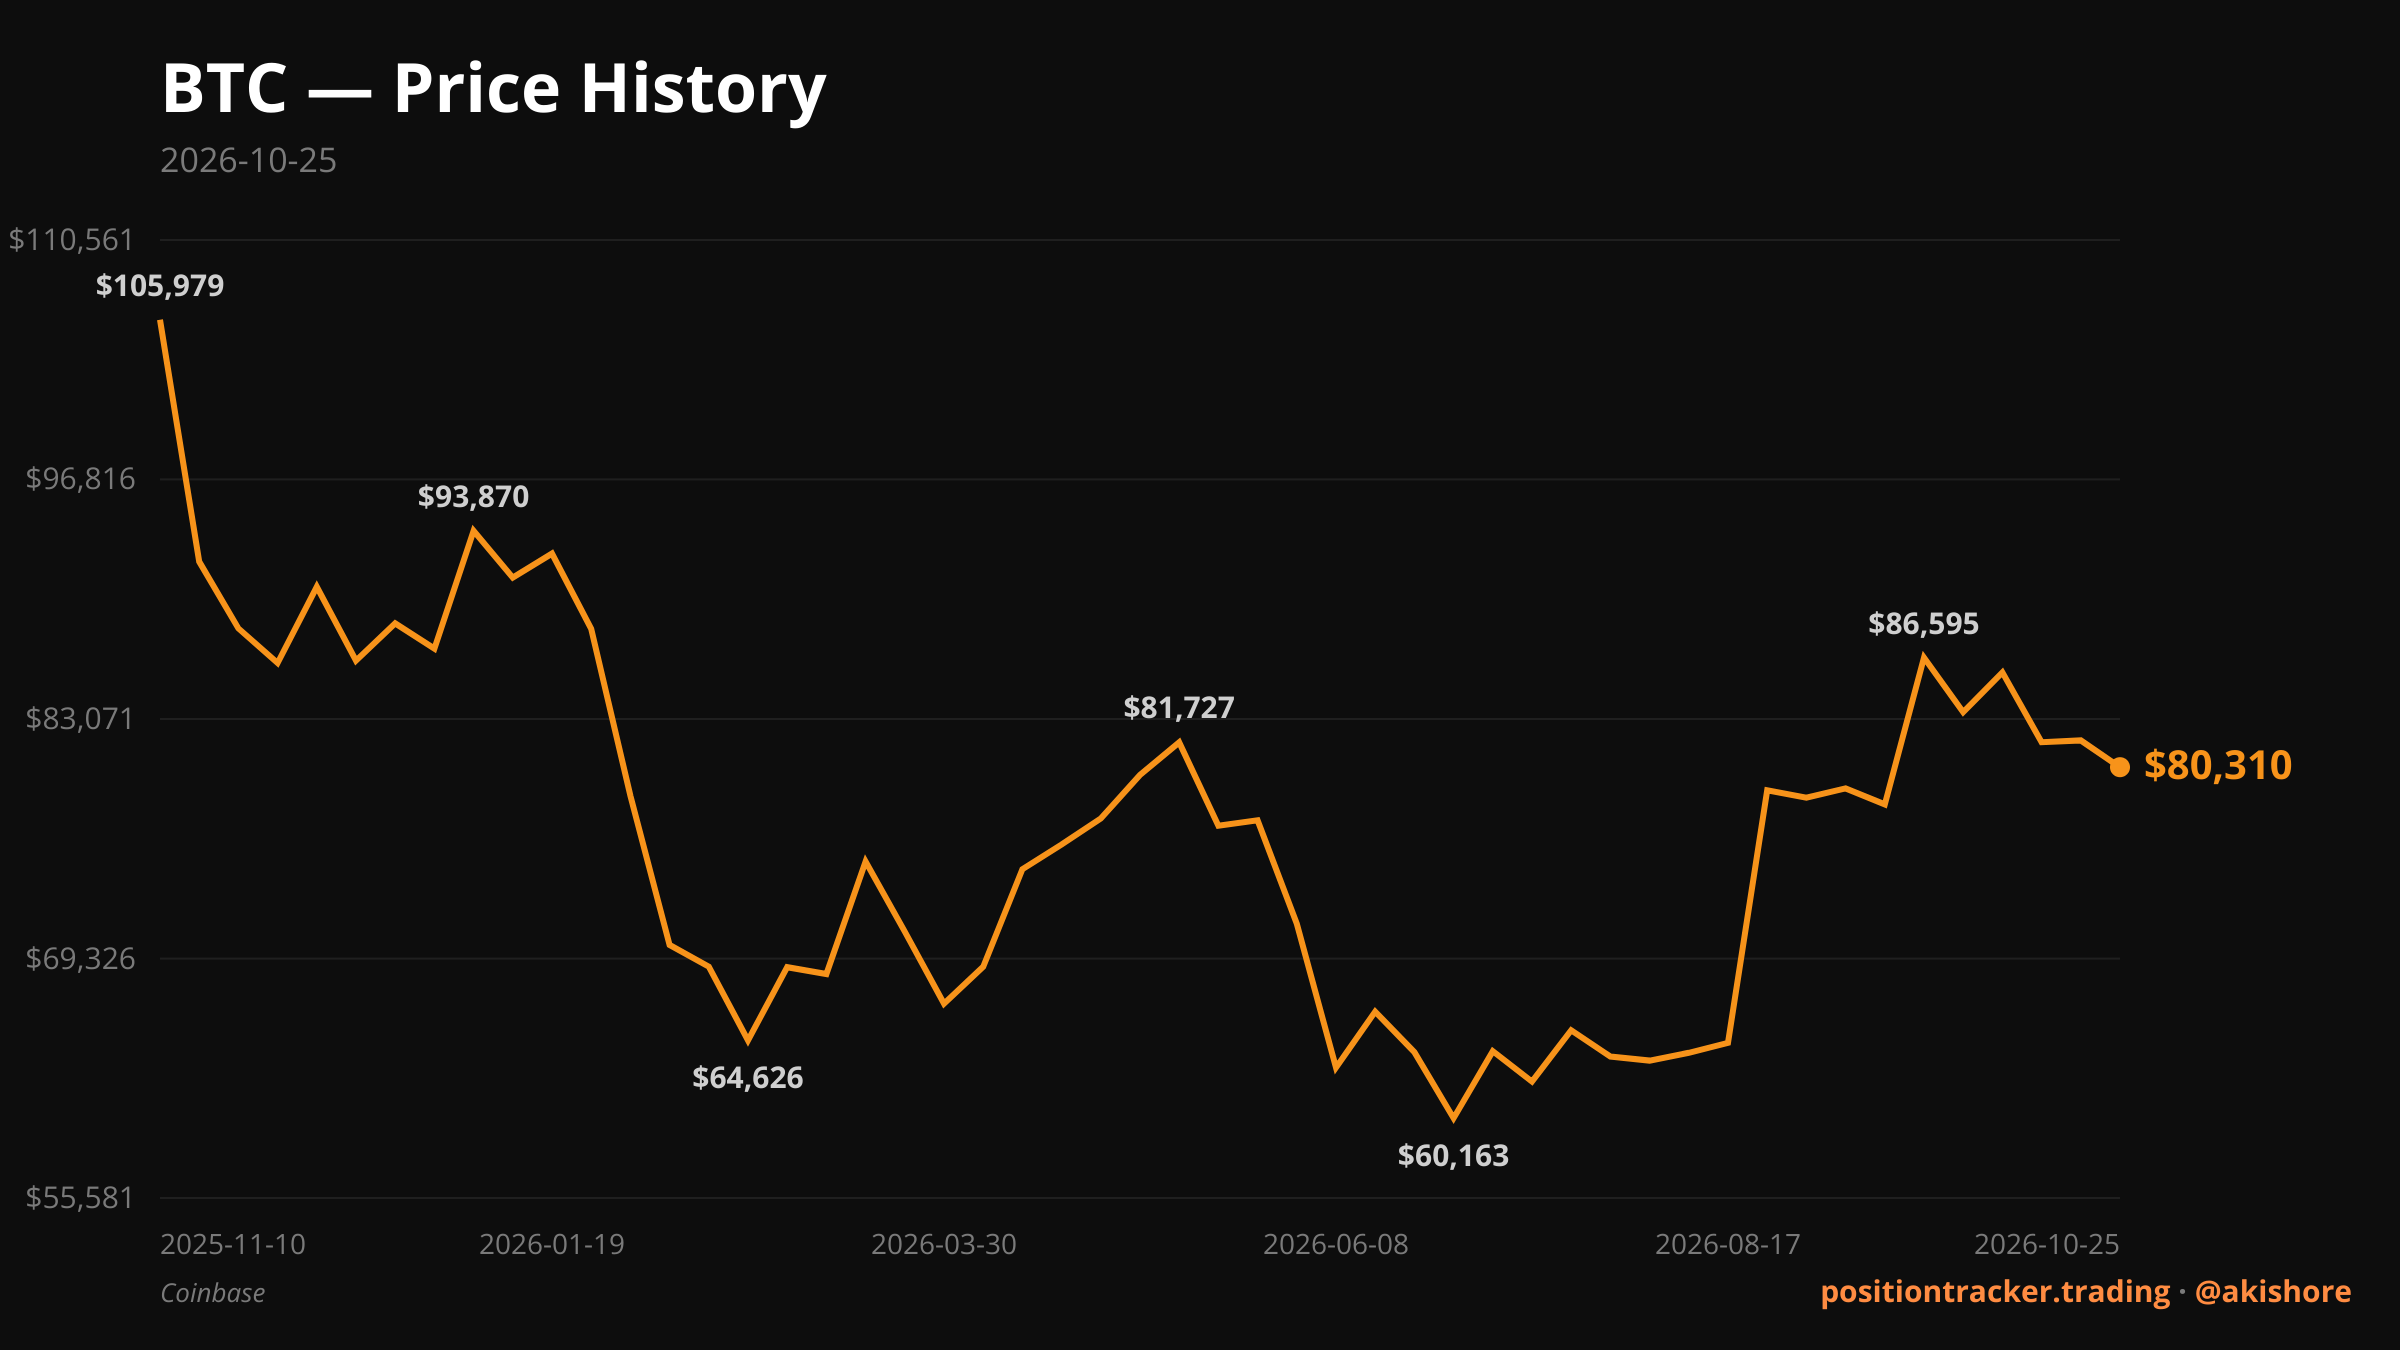
Sunday BTC/ETH research | October 25, 2026 BTC is $80,305.70, down 0.45% over 24 hours. ETH is $2,328.79, down 1.58%. The four-session changes are −4.42% for BTC and −5.74% for ETH. ETH has weakened more over both of those measures.