T-Mobile US ($TMUS): buy in pieces $144 to $160, long term
$TMUS: I think this is a buy after the SpaceX scare.
16% below its 200-day
About 11x 2027 earnings estimates
$18.7B+ of free cash flow guided for 2026
The market is pricing a 2030 problem into a 2026 cash machine.
Not financial advice
The bear case is real. SpaceX agreed to buy $8B of 800 MHz spectrum and is in talks for at least 80,000 cell sites to build a fourth carrier. Account churn rose to 1.09% from 0.97% and Q3 account adds fell to 274K from 396K a year ago.
The chart: I read the fall from the $276 top in March 2025 as an A-B-C correction. A hit $194 in December, B bounced to $225 in February and C bottomed at $143.75 on Oct 28. C is about as long as A and the low sits on the 61.8% retrace of the 2020 to 2025 run.
The business: Q3 EPS of $3.22 beat the $2.89 estimate. Postpaid service revenue grew 9%, Core Adjusted EBITDA grew 11% and management raised the 2026 free cash flow guide to $18.7B to $18.8B. They returned $3.5B to shareholders in Q3 alone.
My plan: I'm buying in pieces between $144 and $160 and holding for years. A weekly close below $135 means I'm wrong. SpaceX still needs towers, approvals and years of capex to match a network T-Mobile already runs. This is a multi-year hold, not a trade.
Sources: T-Mobile Q3 2026 results press release · T-Mobile Q3 2026 investor factbook (SEC exhibit 99.2) · Motley Fool: TMUS Q3 2026 earnings call transcript · MarketWatch: T-Mobile 3Q profit and revenue rise on postpaid growth · Reuters via Investing.com: T-Mobile raises annual FCF forecast · Yahoo Finance: TMUS falls as SpaceX spectrum deal raises competition concerns
Not financial advice. For informational and educational purposes only.
$AVGO daily pick: sell Nov 20 $300 cash-secured put
$AVGO: I'm selling the Nov 20 $300 put and getting paid to wait on Broadcom. As of Friday's close ($328.75): 11% below the 200-day and 34% off the June high Credit $5.15 for ~1.7% in 35 days (~18% annualized) Breakeven $294.85 sits just above the $289.96 March low About 17x next year's EPS estimate with revenue up 85% last quarter
$CAT daily pick: sell Dec 18 $560 put (buy-side) after the Q3 selloff
$CAT: I'm selling the Dec 18 $560 put on @CaterpillarInc after the post-earnings drop and getting paid to wait. As of midday ($632.92): Down 11% in two days, 22% below the 200-day and 41% off the June high Credit $9.45 for about 1.7% in 49 days (~13% annualized) Breakeven $550.55, about 13% below today About 19.5x 2027 EPS estimates
AI Capex Is Splitting Free Cash Flow Margins Across 11 Tech Names
$NVDA recorded $302.97B in trailing twelve-month revenue and a 41.9% free cash flow margin, 5.1 percentage points below the 47.0% of the four…
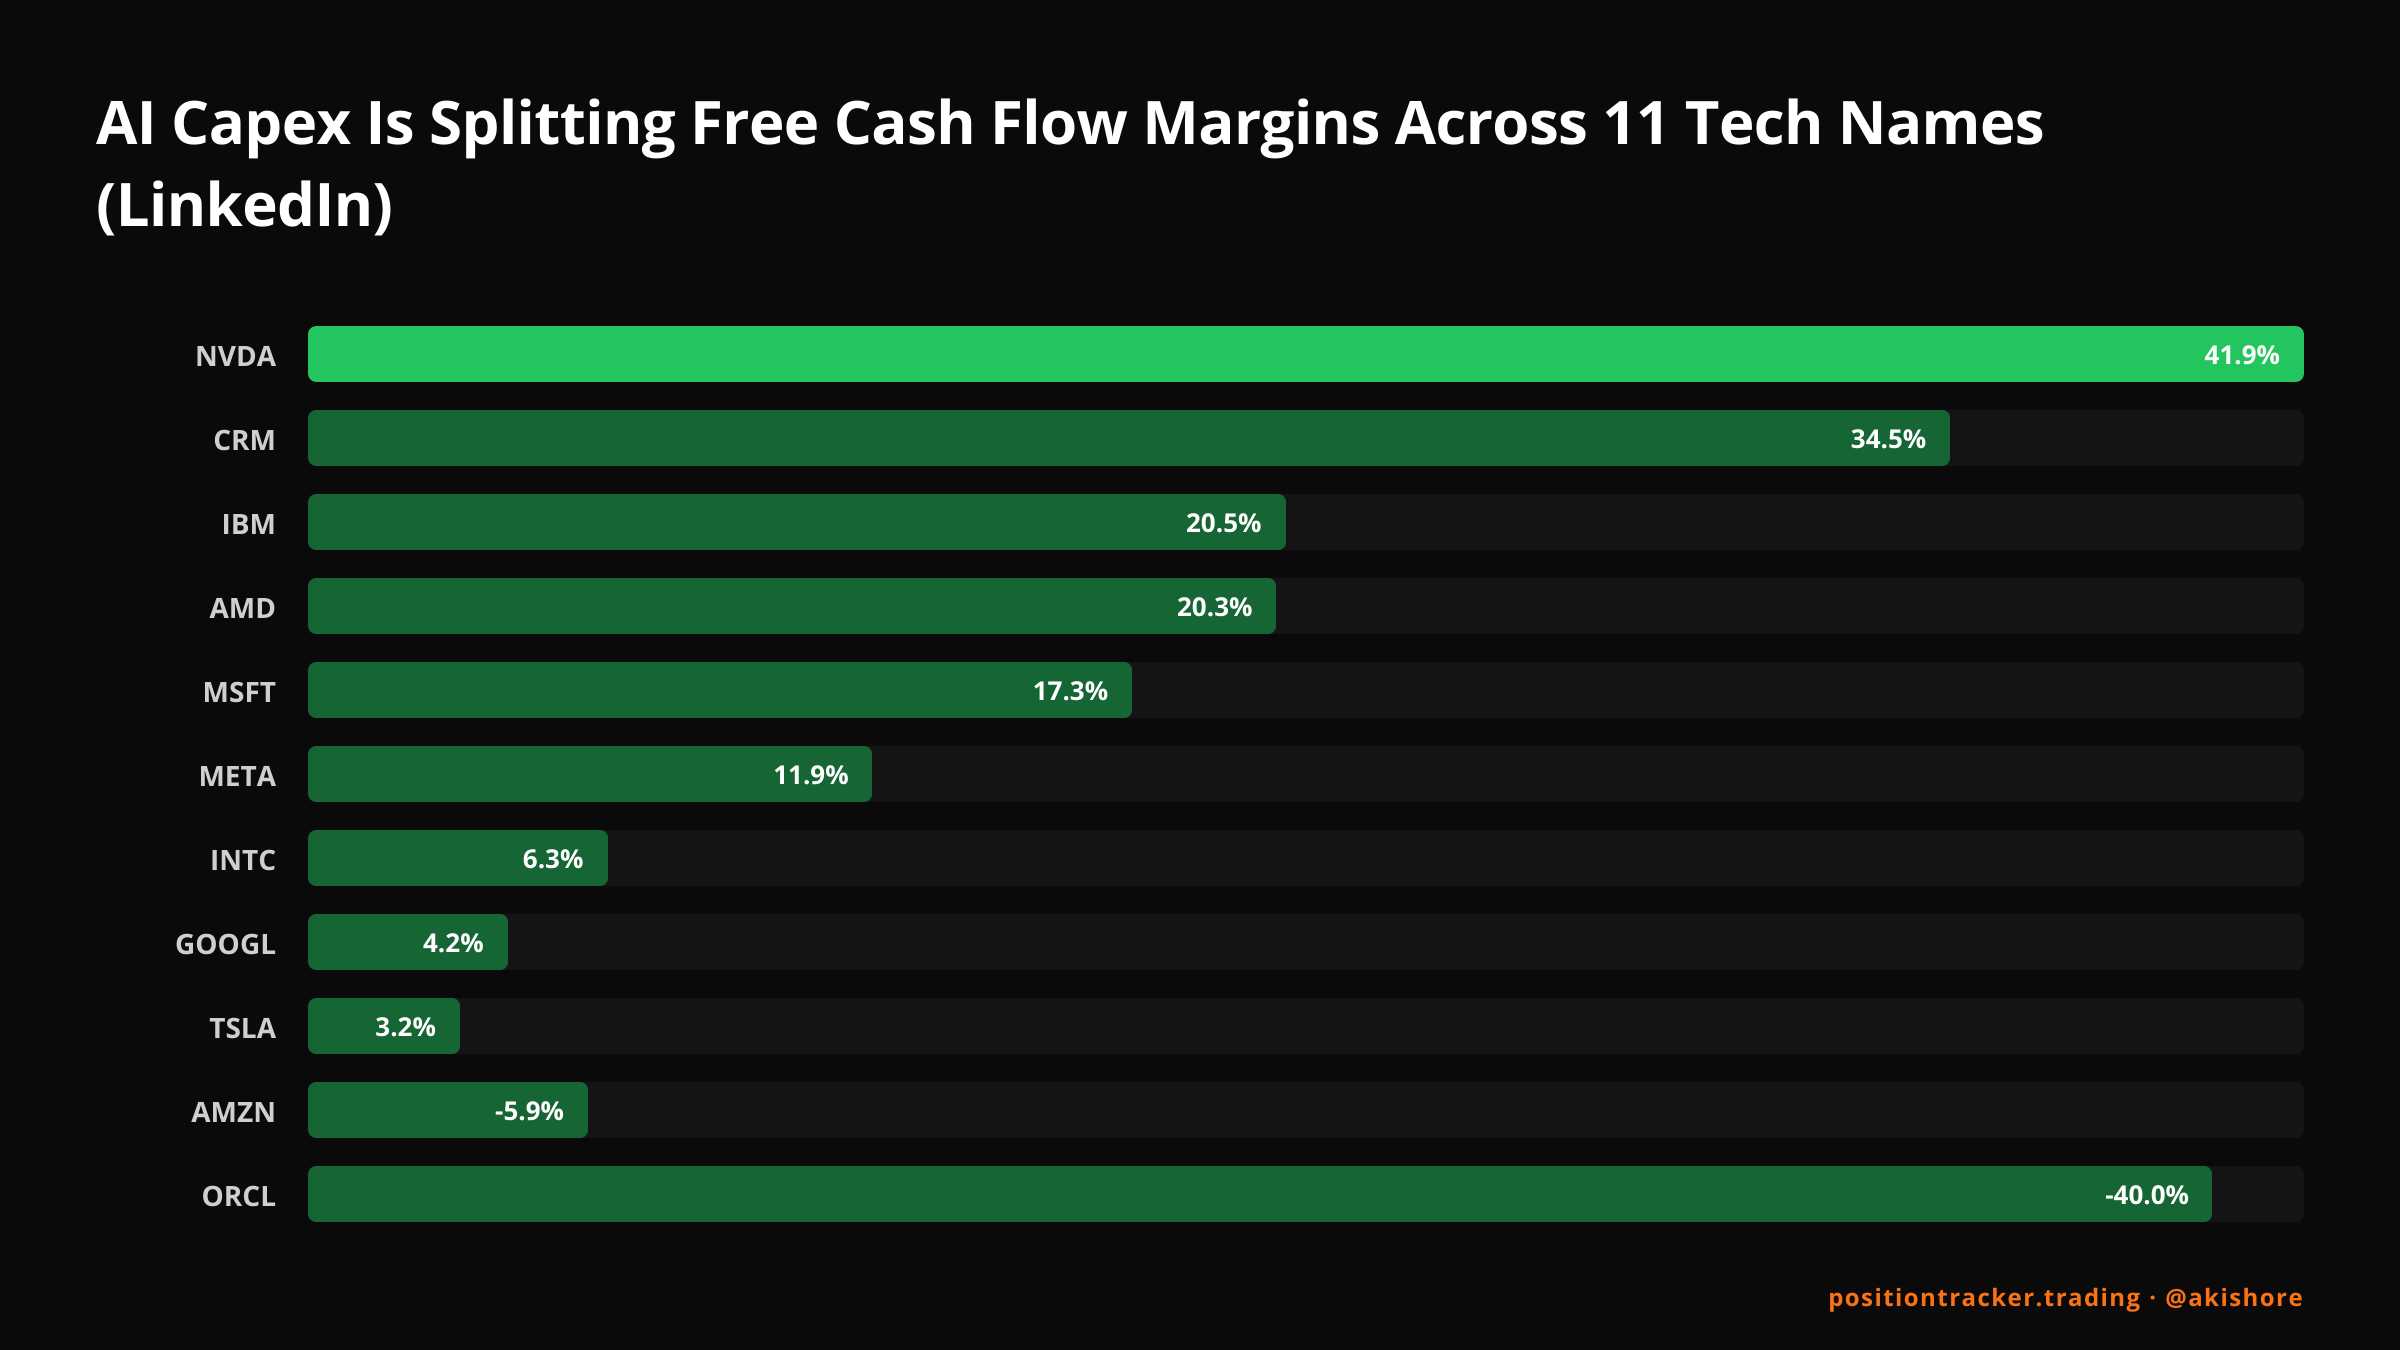
$NVDA recorded $302.97B in trailing twelve-month revenue and a 41.9% free cash flow margin, 5.1 percentage points below the 47.0% of the four quarters ending one quarter earlier. Nvidia still leads the tracked group by margin, with about $127B in TTM free cash flow.
Lovable at $13.3B and $600M+ ARR
Lovable's $400M Series C at a $13.3B valuation doubled the $6.6B mark it set in December 2025.
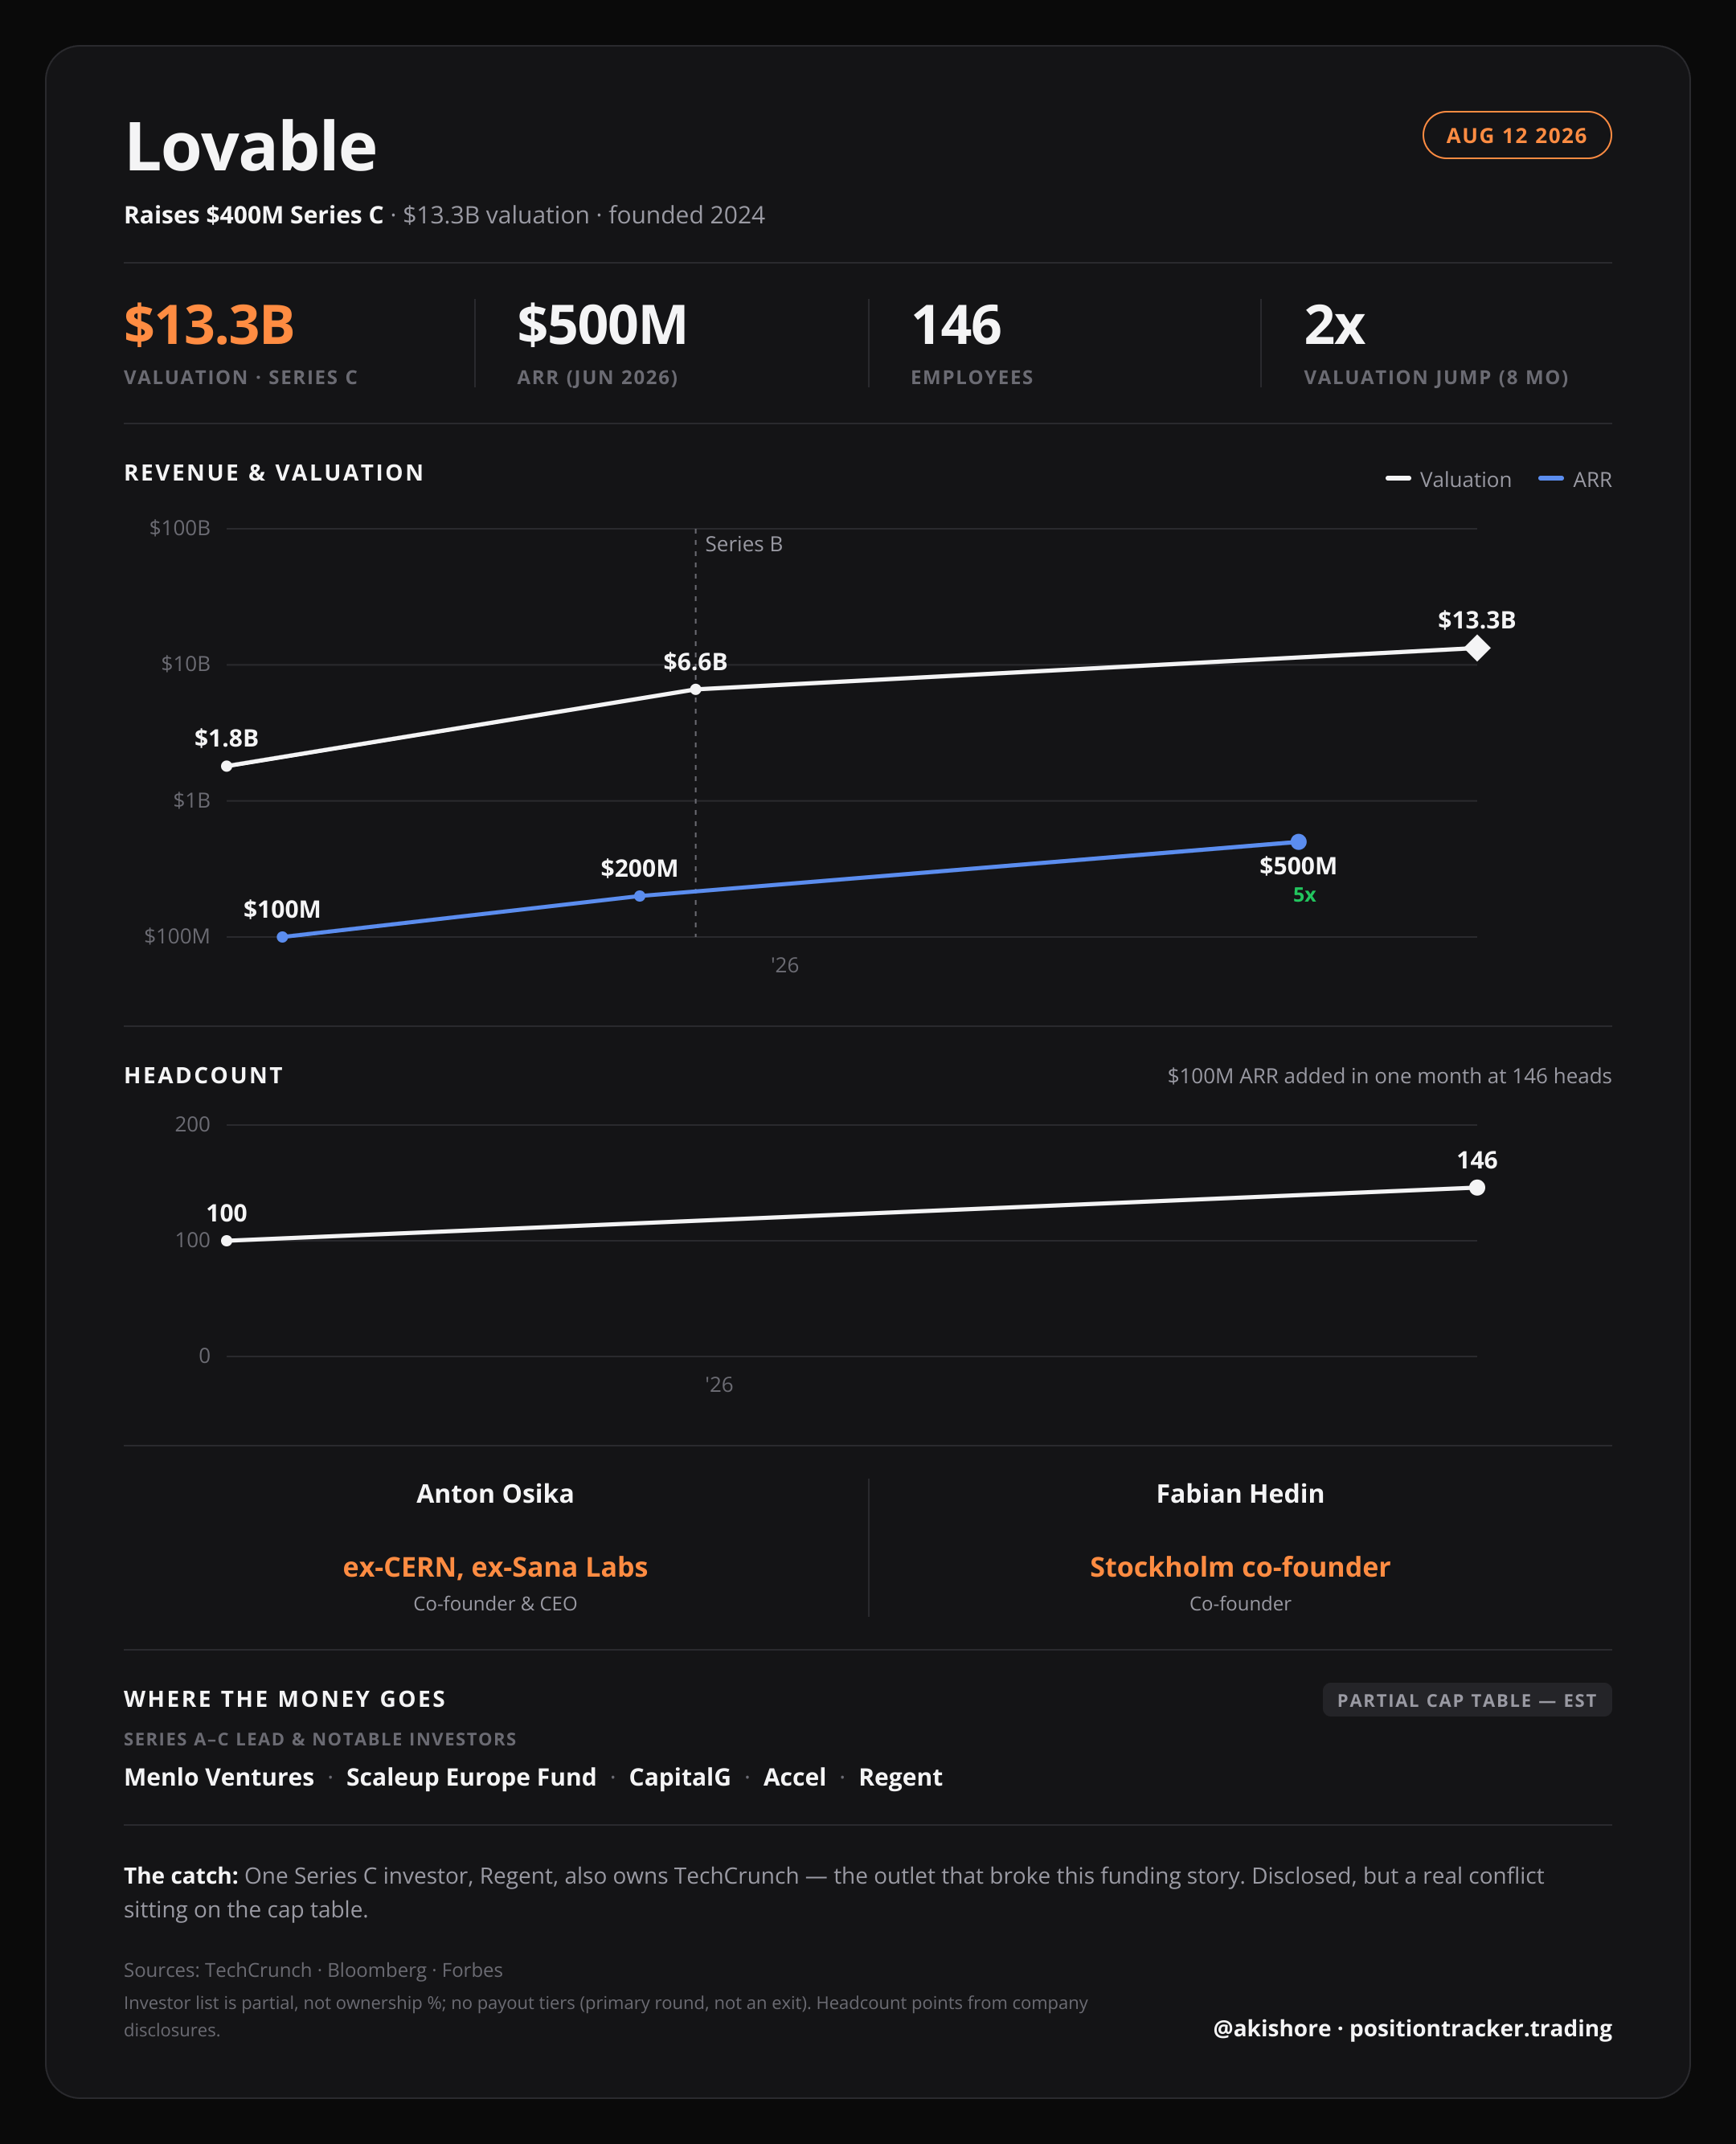
Lovable's $400M Series C at a $13.3B valuation doubled the $6.6B mark it set in December 2025. The run rate keeps climbing: co-founder Fabian Hedin has put annualized revenue above $600M, up from about $500M reported in…