Target's $2.65 adjusted EPS is a good quarter with a tariff-refund boost on top, and I'd value it on the sales line and the comps rather…
Target's $2.65 adjusted EPS is a good quarter with a tariff-refund boost on top, and I'd value it on the sales line and the comps rather than the 48.9% EPS jump.
- Adjusted EPS went from $1.78 to $2.65. About $0.50 of that came from $301 million in pretax tariff refunds, so strip it out and growth is still decent, just a lot less flashy.
- The demand side looks real to me: net sales up 7.1% to $27.07 billion, comps up 5.6%, comparable traffic up 5.0%, digital comps up 9.8%.
- FY26 sales guidance went to about 6% from about 5%, and adjusted EPS guidance is now $10.65 to $11.40. That includes roughly $2.14 per share of refunds recognized to date, so a chunk of the full-year number won't repeat.
- Funny part: tariffs squeezed retailers, and now the refunds flatter their earnings. I still think tariffs hurt in the end, and one company's refund check doesn't change my inflation worry.
TGT closed up 7.08% at $170.82 on November 18, and the traffic numbers earn some of that. What I'm watching is the Q4 commentary on whether refunds keep coming, because I'd pay for the 5.6% comps and not for a one-time refund line.
Sources:
Zacks: https://www.zacks.com/stock/news/3031902/target-q3-earnings-beat-on-sales-growth-and-tariff-refunds-fy26-view-up?cid=CS-STOCKNEWSAPI-FT-analyst_blog|earnings_article-3031902
CNBC: https://www.cnbc.com/2026/11/18/stocks-moving-the-most-today-live-updates.html
Not financial advice. For informational and educational purposes only.
An analyst forecast hit memory stocks harder on Nov.
An analyst forecast hit memory stocks harder on Nov. 18 than SanDisk's split news could lift them. That fits my skepticism on memory: these names trade on where prices are headed, and the share count doesn't change that. GF Securities reportedly cut its…
$UNH daily pick: buy a starter in UnitedHealth after a 13.5% two-day drop on the CMS audit proposal
$UNH: I'm buying a starter in @UnitedHealthGrp after two bad days. At $356 (midday Wednesday, down 13.5% since Monday): 18% off the July high and 3% under the 200-day About 17x the 2026 adjusted EPS guide of at least $20.50 Q3 medical care ratio 88.4% vs 89.9% a year ago
Afternoon update
Cybersecurity and off-price retail led the afternoon of Nov. 18, while managed care and refiners took the heaviest losses.
Cybersecurity and off-price retail led the afternoon of Nov. 18, while managed care and refiners took the heaviest losses. The Nasdaq rose 0.66% and the S&P 500 finished essentially flat at -0.01%. $OKTA gained 11.23% to $194.14 and CrowdStrike rose 9.04% to…
Midday update
Midday Wednesday shows a split tape. $TJX is up 10.38% on a beat-and-raise, while gold's drop to a 1-year low sends miners down 8-9%.
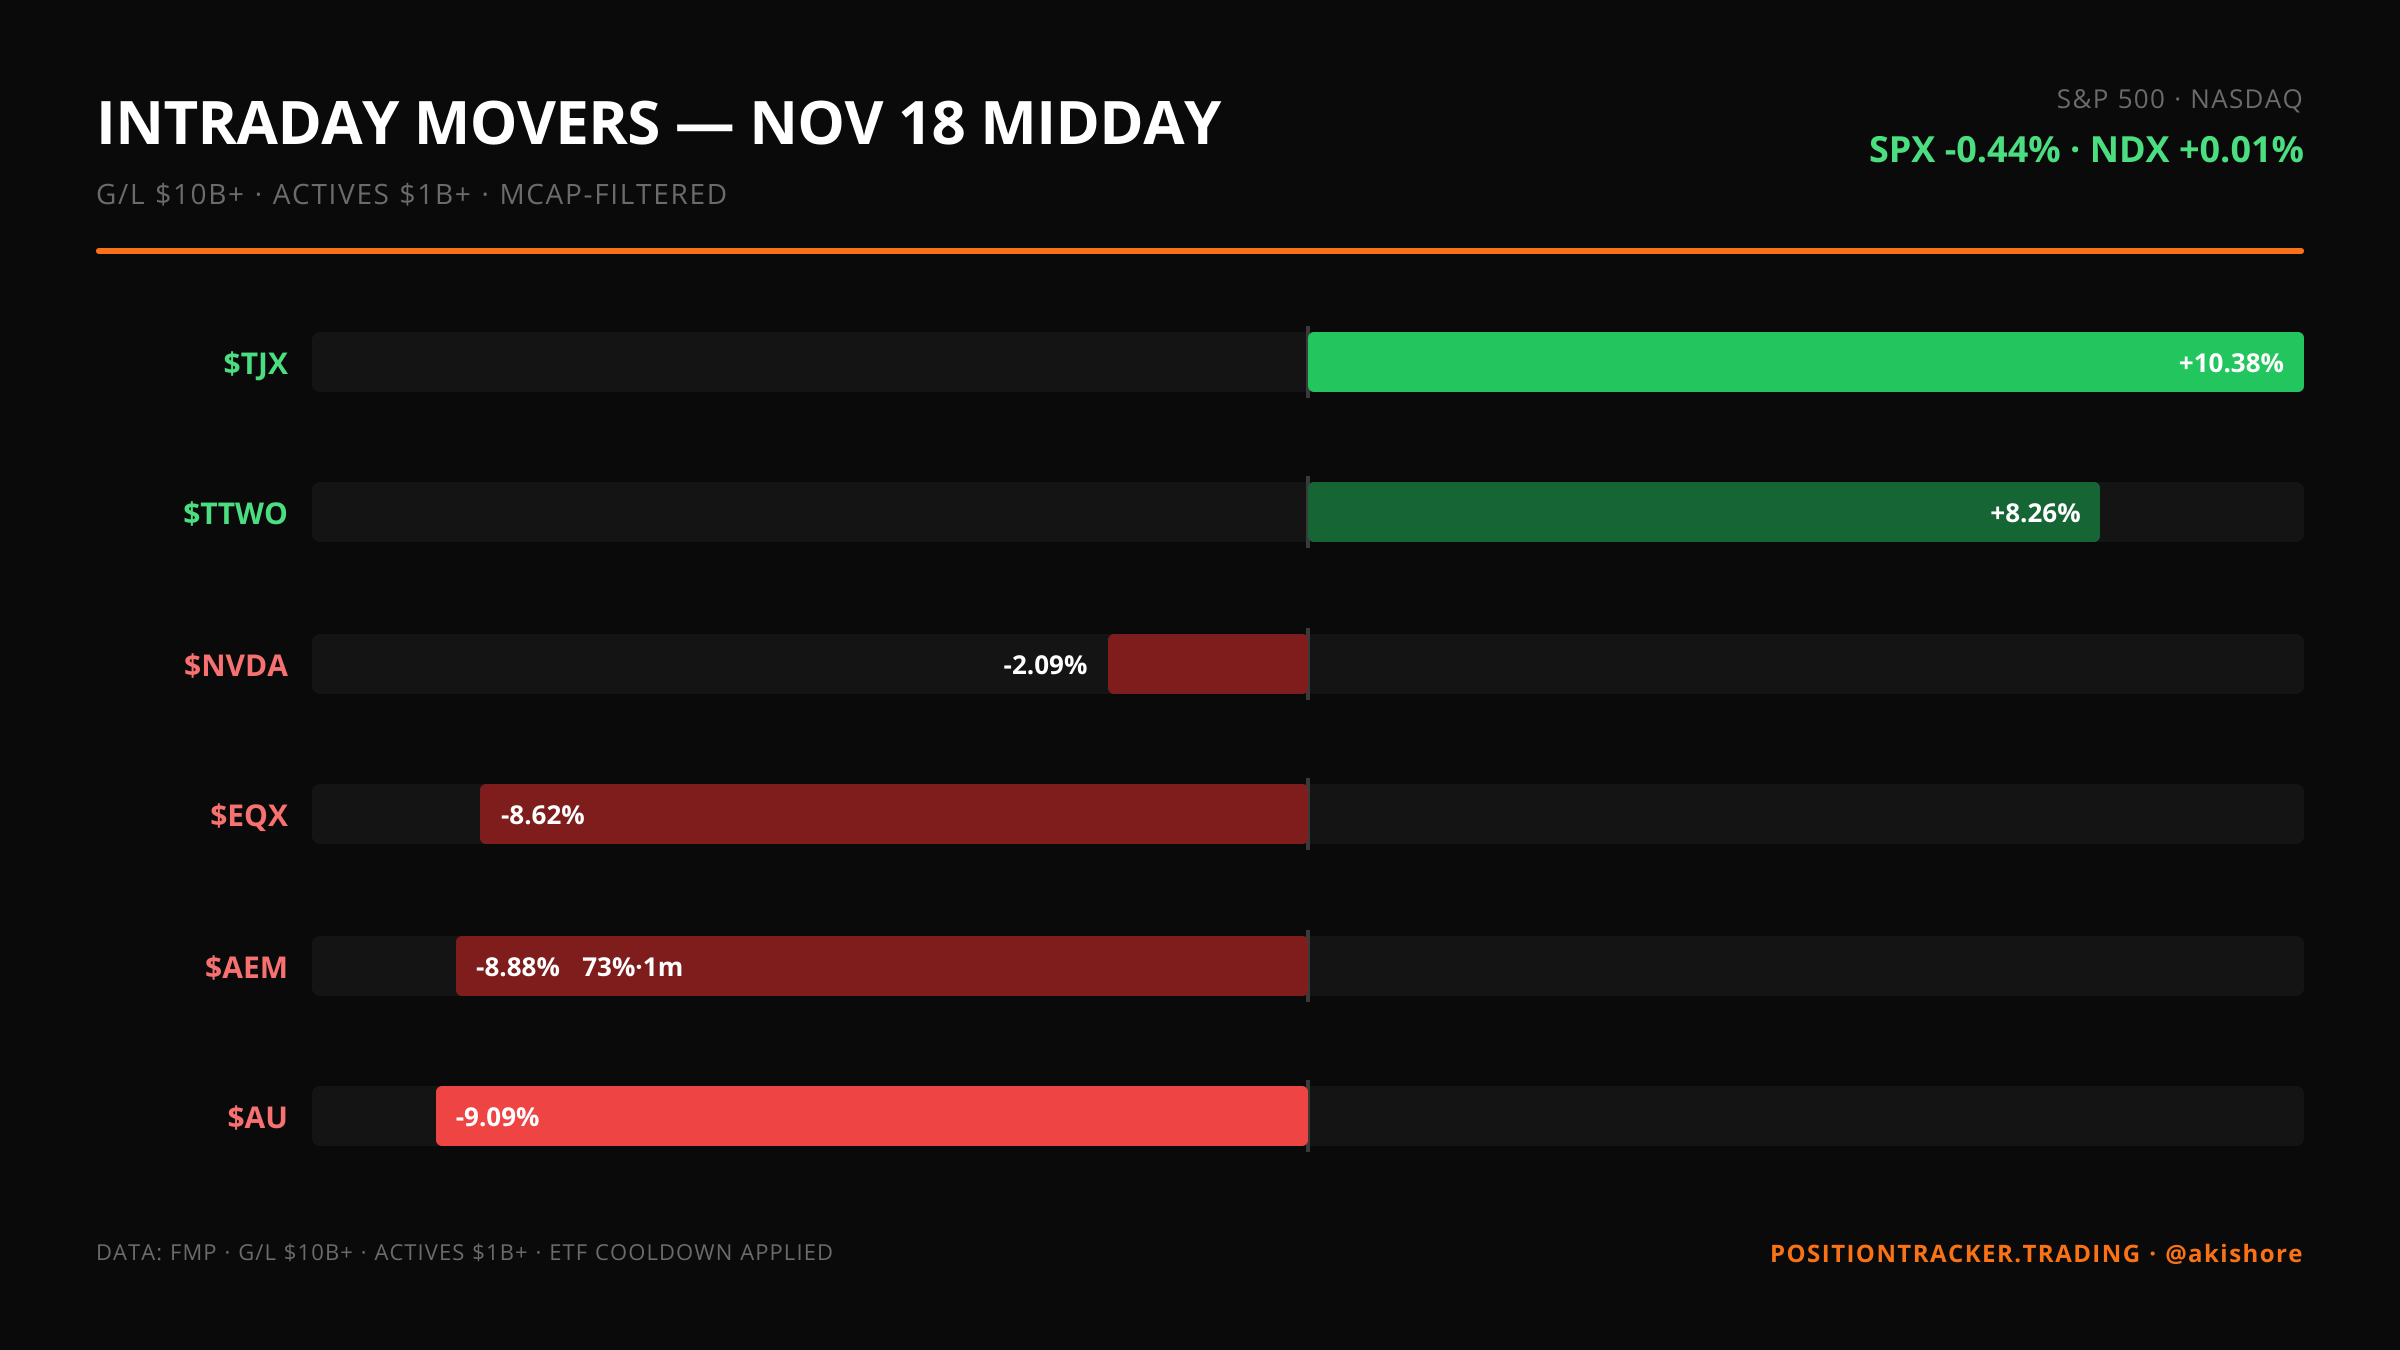
Midday Wednesday shows a split tape. $TJX is up 10.38% on a beat-and-raise, while gold's drop to a 1-year low sends miners down 8-9%. The S&P 500 is down 0.44% and the Nasdaq is flat at +0.01%. TJX +10.38%: Q3 FY27 revenue was $15.95B, up…