$17.85 to $17.95.
$17.85 to $17.95. That's Royal Caribbean's new 2026 adjusted EPS range, up from $17.73 to $17.87, and to me it matters more than the Q3 beat itself. Raising guidance with fuel and currency working against you says demand is doing the heavy lifting.
- Q3 net income came in around $1.73B vs about $1.58B a year earlier. GAAP EPS was $6.45; adjusted EPS was $6.57, ahead of the $6.38 consensus. I'd keep both numbers in view since I always check past the adjusted figure.
- Revenue was $5.59B, up about 9% year over year, though slightly below some estimates. Worth noting before anyone calls this a clean sweep.
- The company credits stronger close-in demand, especially in Europe and the Caribbean, plus expense timing that pushed some costs into Q4. That timing piece means Q4 carries more of the cost load.
- RCL was $298.55 in pre-market on October 27, up 6.4% from the $280.60 close on October 26.
My read: the demand story looks real, and the guidance raise backs it up more than the headline EPS does. What I'd want next is management's 2027 booking commentary and pricing trends, because a pre-market pop on a raise only holds if next year fills at good prices. I could be wrong if those Q4 costs land heavier than expected.
Sources:
WSJ: https://www.wsj.com/business/earnings/royal-caribbean-lifts-full-year-forecast-after-posting-higher-quarterly-profit-cf18ff38
Zacks: https://www.zacks.com/stock/news/3015542/royal-caribbean-rcl-beats-q3-earnings-and-revenue-estimates?cid=CS-STOCKNEWSAPI-FT-fundamental_analysis|yseop_template_4-3015542
Not financial advice. For informational and educational purposes only.
155 responses.
155 responses. That's the number Cloudflare put on its GLM-5.3 cache leak, and I think publishing it does more for trust in Workers AI than the bug does damage. Cloudflare disclosed on October 26 that 155 GLM-5.3 responses on…
The number I'm watching is October 28, the day SK hynix reports.
The number I'm watching is October 28, the day SK hynix reports. Market coverage tied a US filing to a rally in a Seoul chipmaker on October 27, and the read-through is only worth what the earnings confirm. Anthropic publicly filed its S-1 on October 26, disclosing…
America ($BAC)
Bank of America ($BAC) is the conviction pick of the analysis this week: a large-cap the market is pricing like a broken business, when the core…
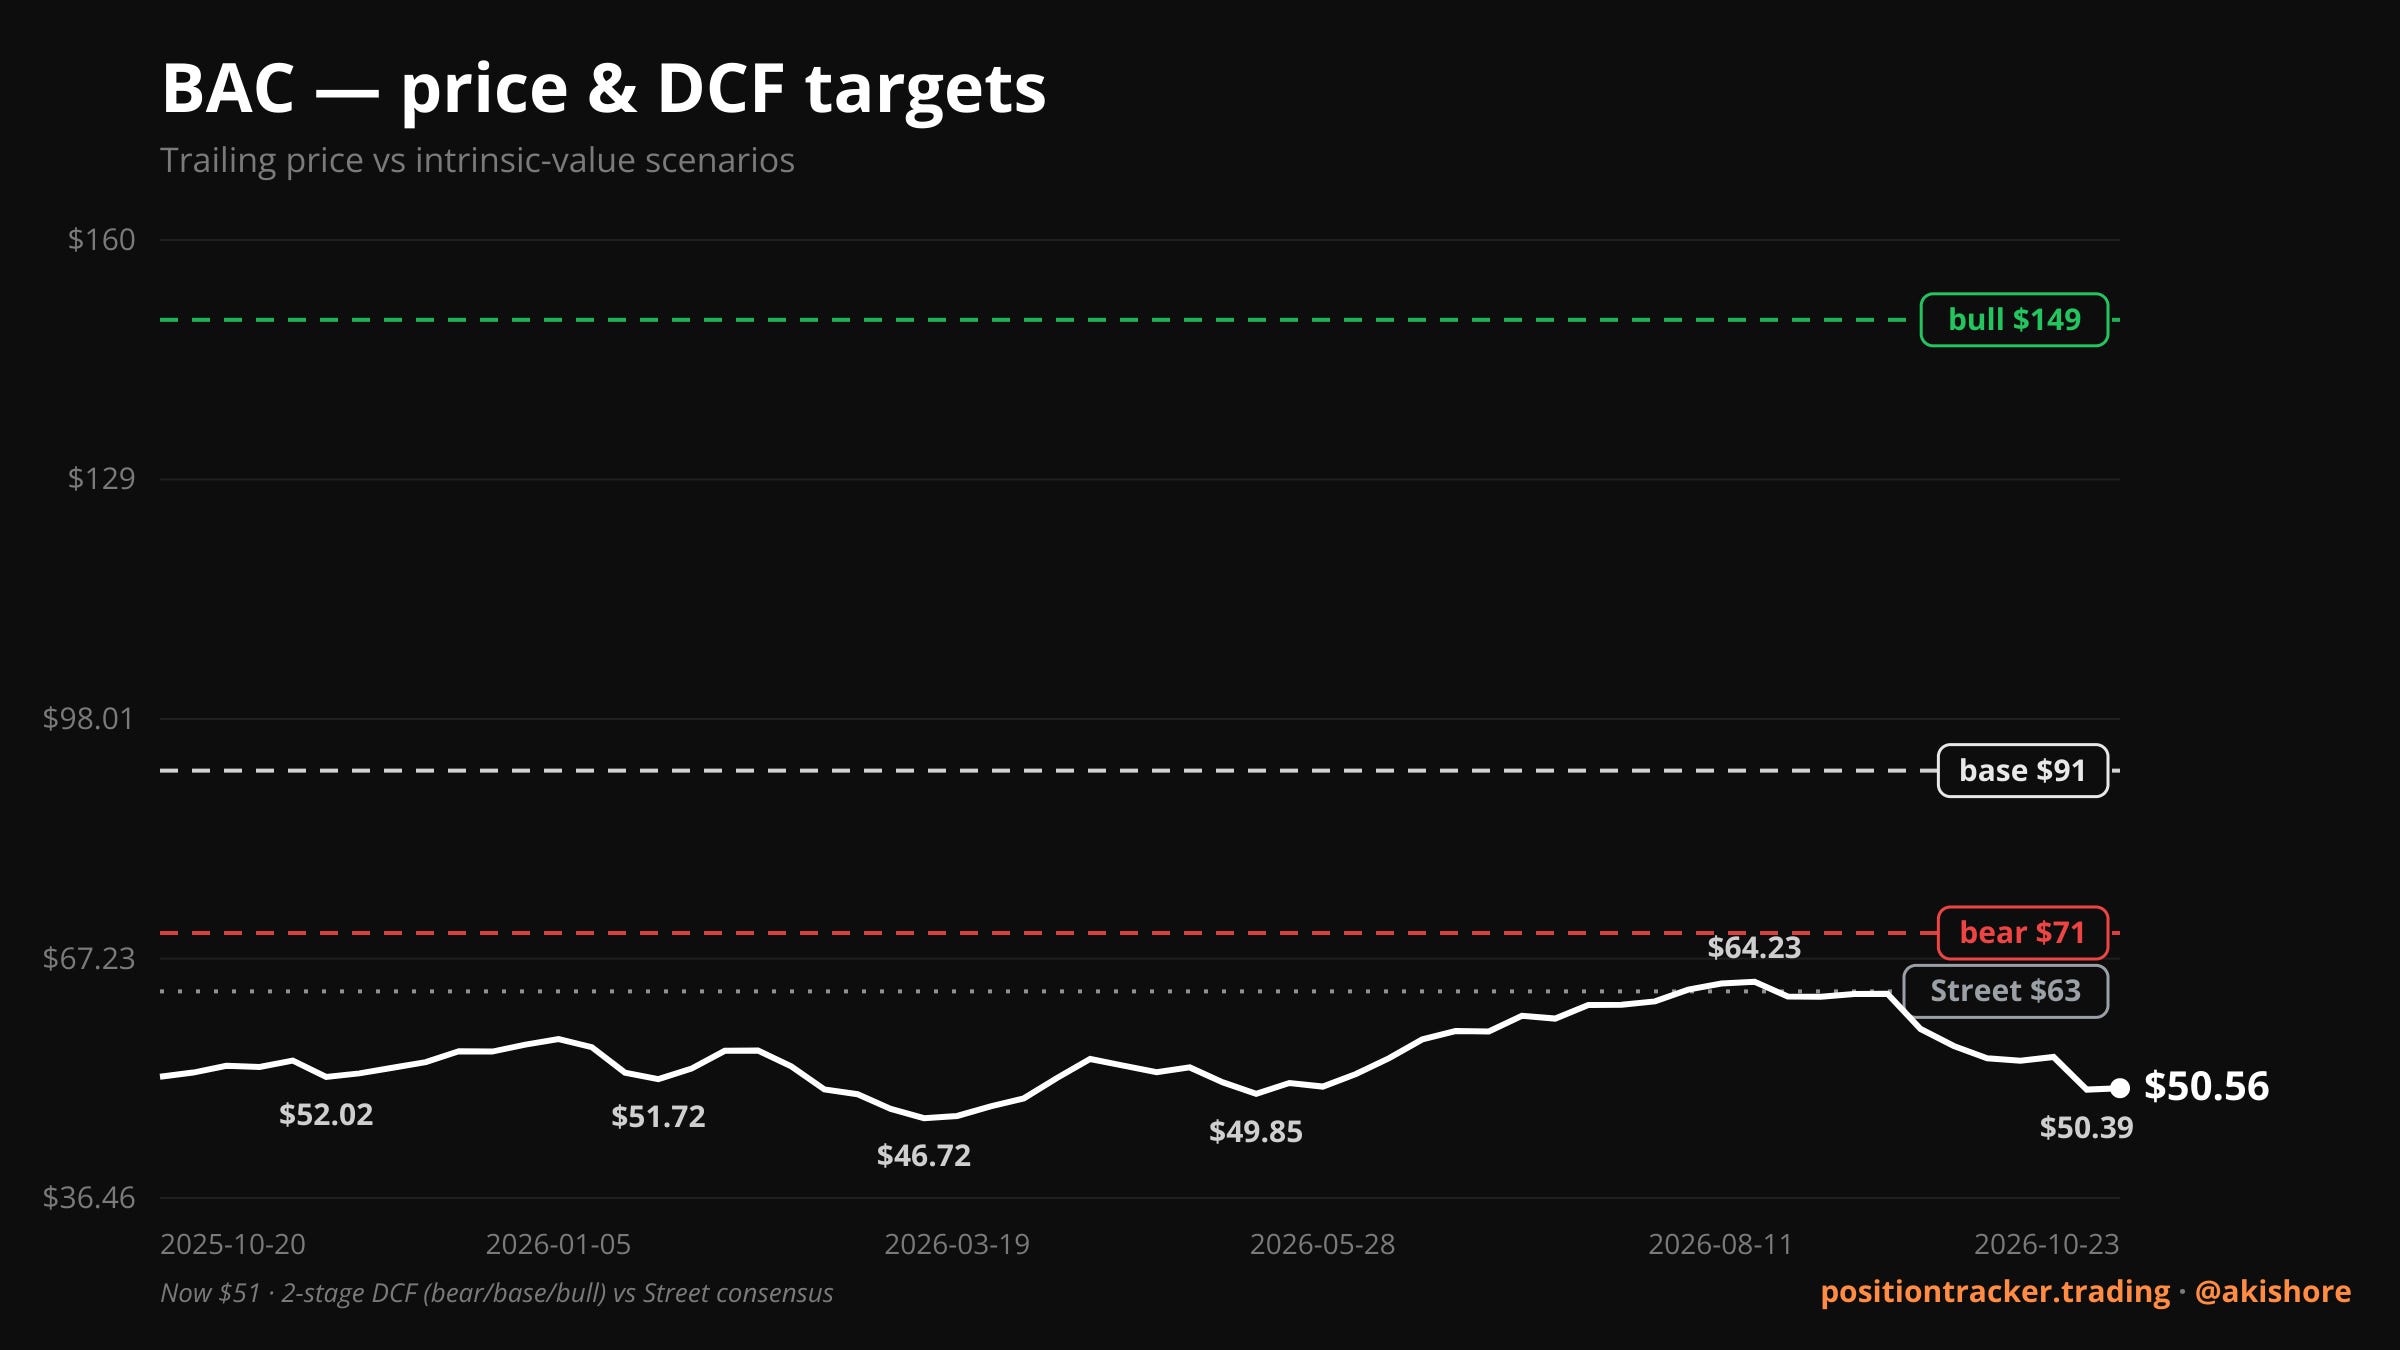
Bank of America ($BAC) is the conviction pick of the analysis this week: a large-cap the market is pricing like a broken business, when the core numbers say otherwise. The stock is at $50.87 in pre-market trading, up 0.7% from Monday's $50.52 close, and still 22% below its 52-week high of $65.23. It has not recovered from Q3 results day,…
End-of-day recap
Lula's runoff win sparked a Brazil selloff, with XP Inc falling 48.36% to $15.71 as markets headed toward the Fed decision.
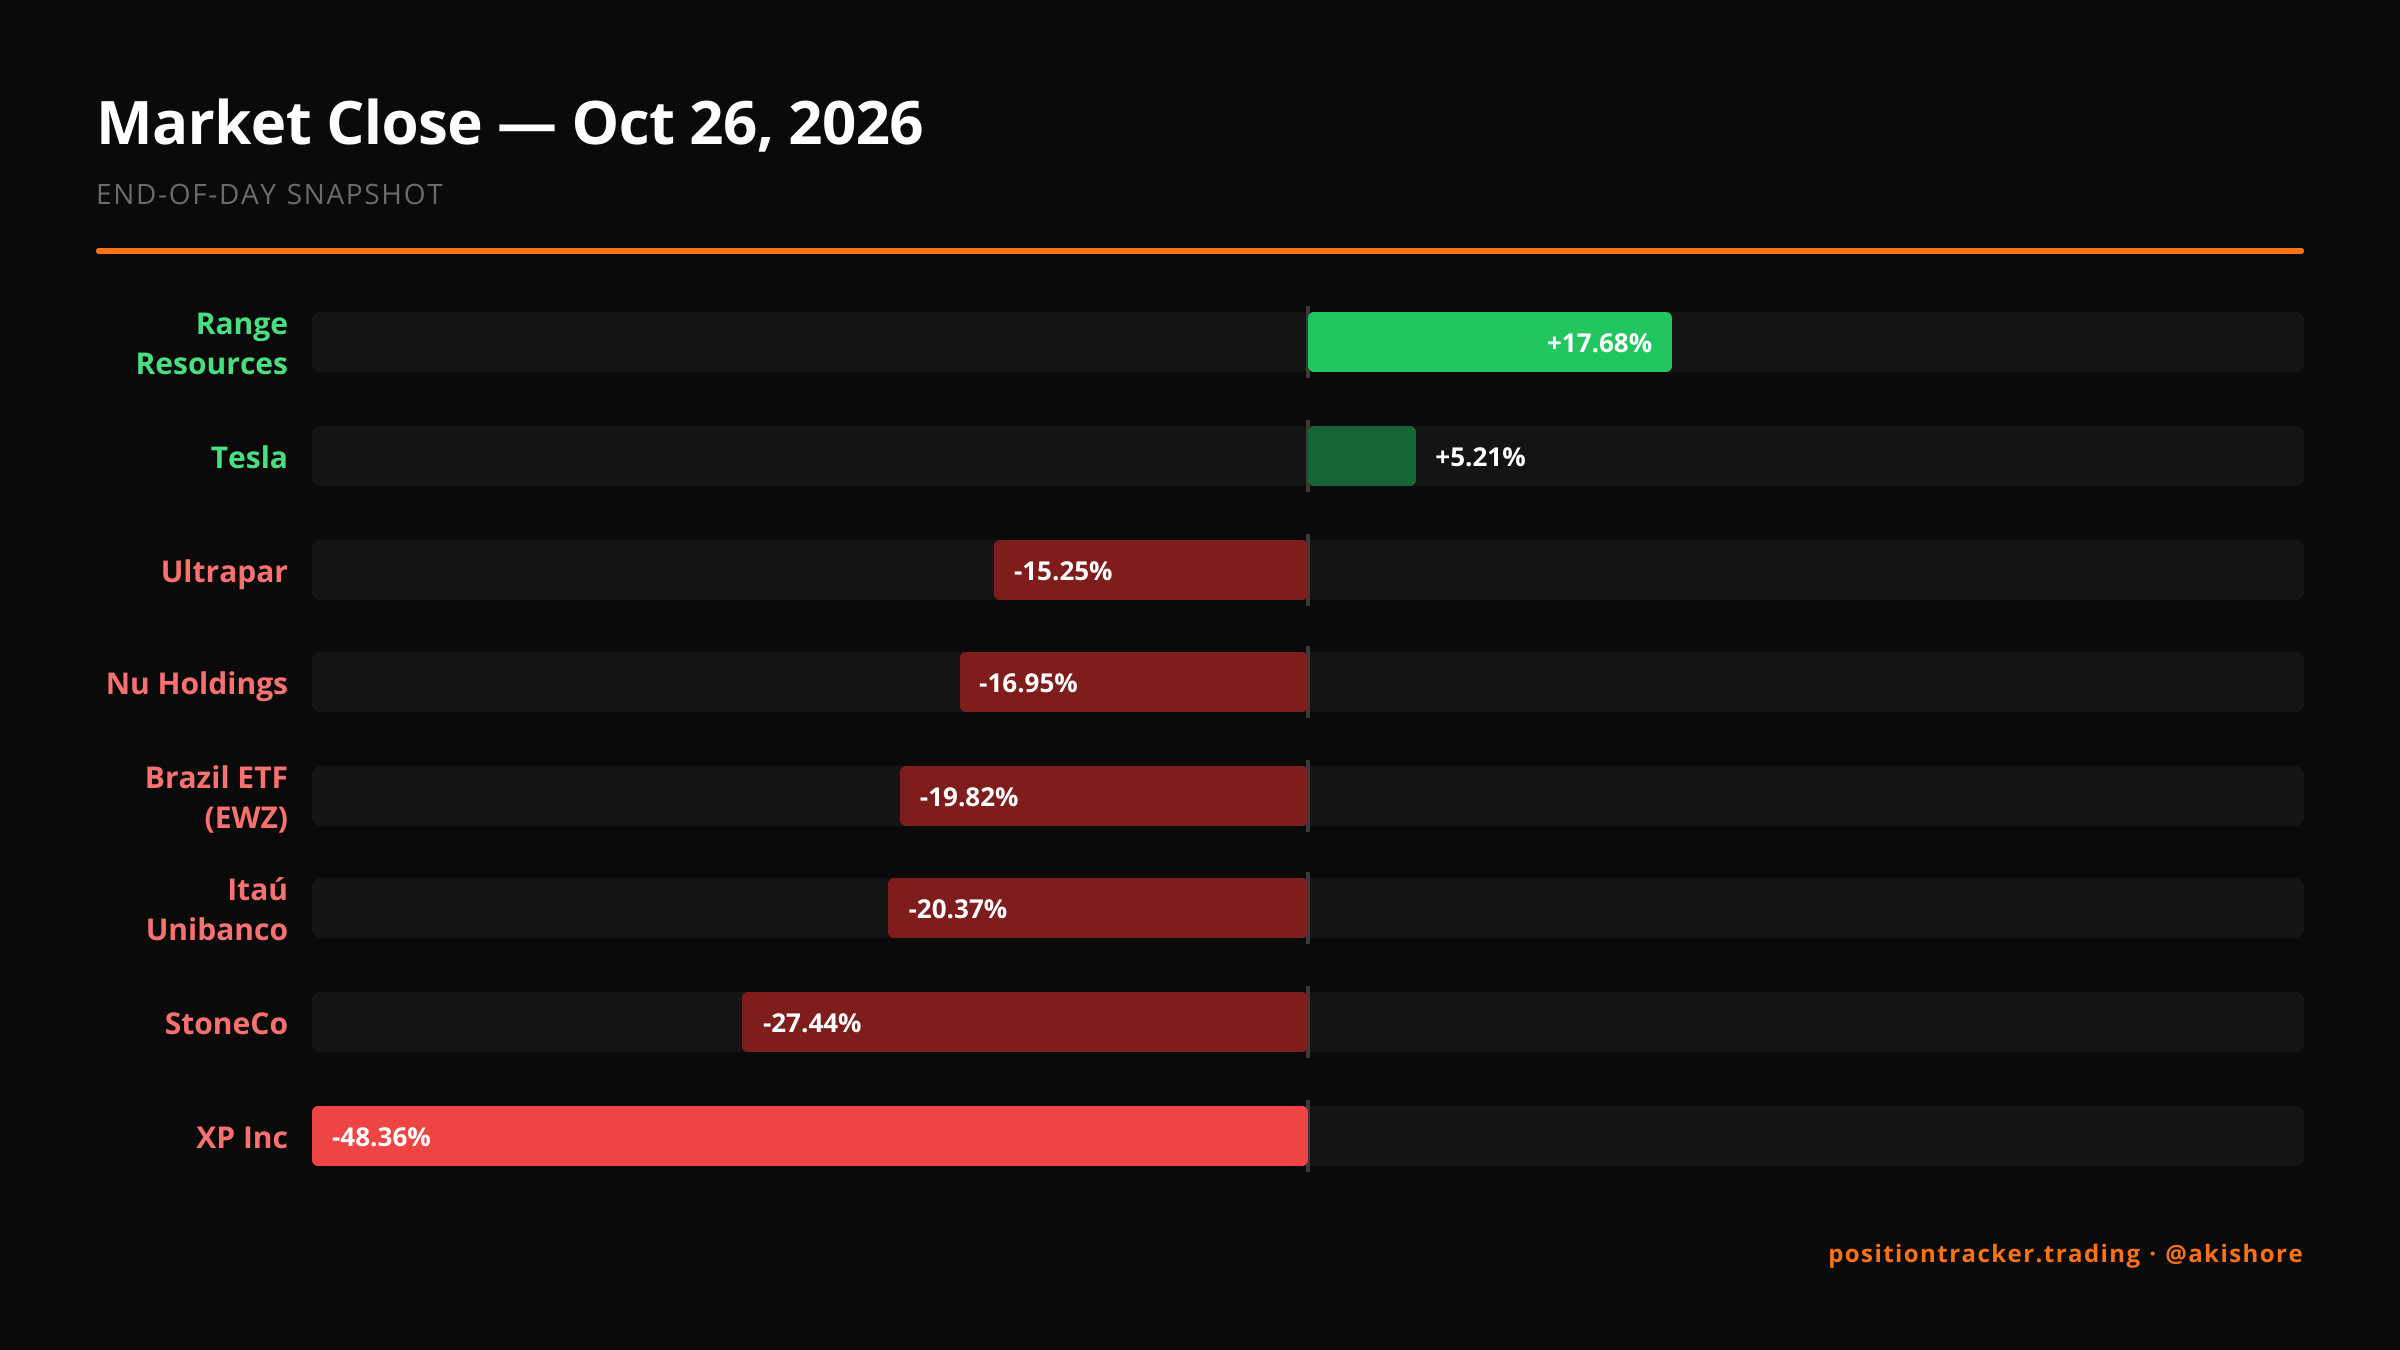
Brazil's runoff result drove the session's largest single-stock move. A natural gas deal and tech gains set the pace elsewhere as markets headed toward Wednesday's Federal Reserve decision. XP Inc fell 48.36% to $15.71, the session's biggest single-stock move. President Luiz Inacio Lula da Silva won Sunday's runoff with 51.8% over Flavio Bolsonaro, a result markets had not priced in.