Amazon delivered a Q2 that reminded everyone why AWS remains the core valuation driver.
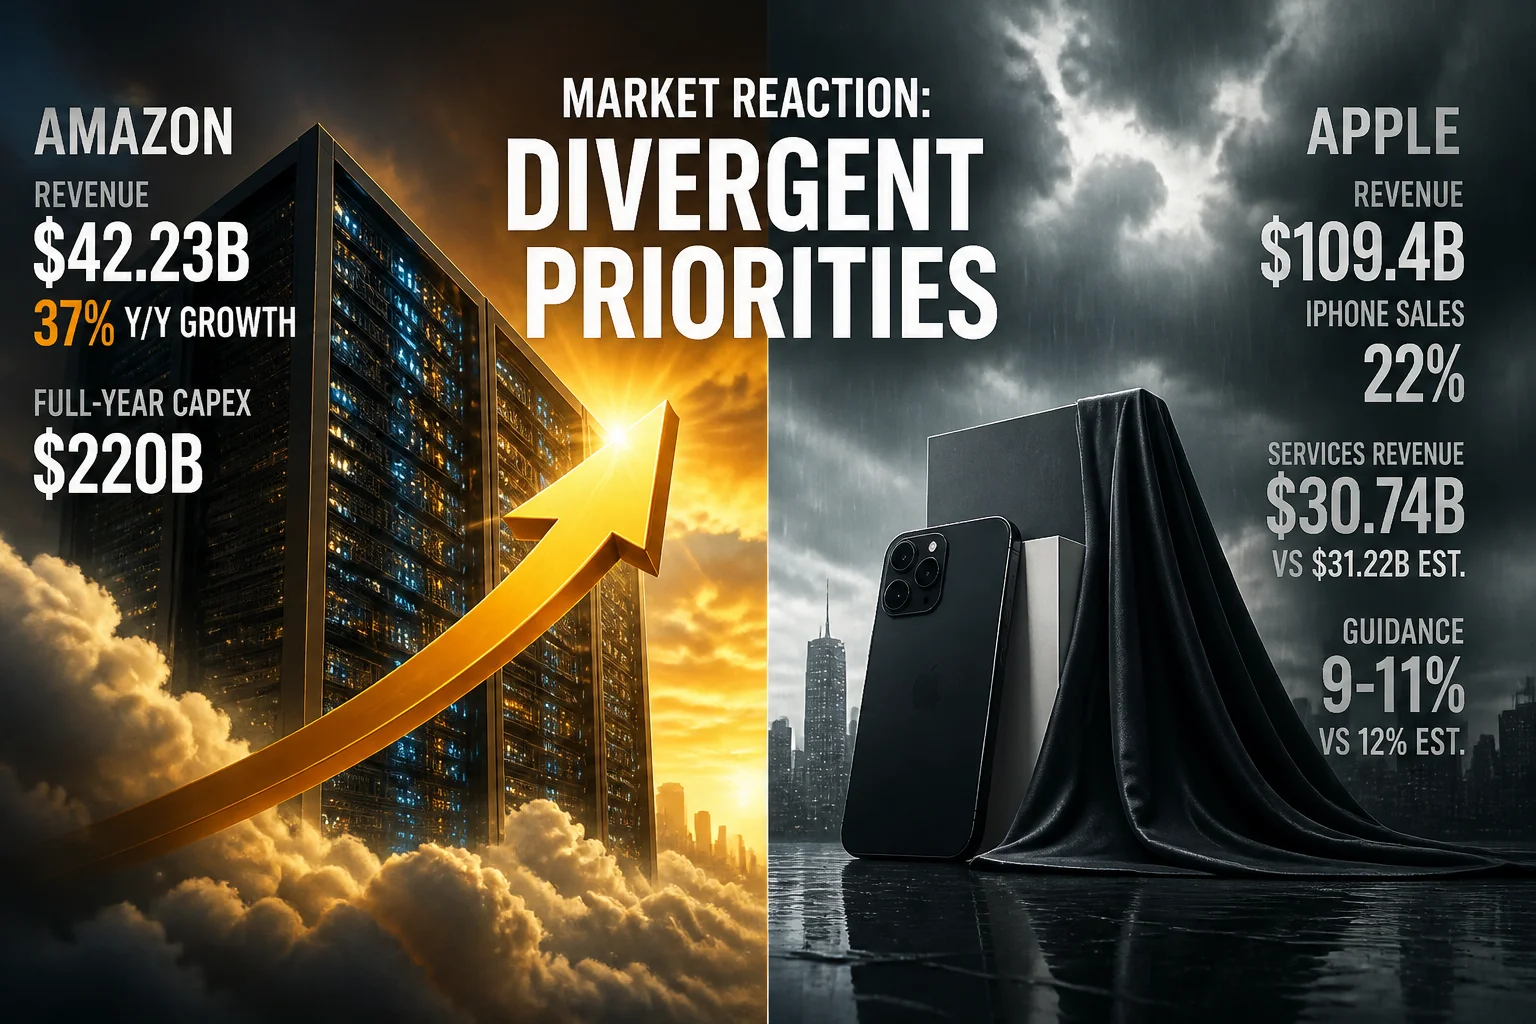
Amazon delivered a Q2 that reminded everyone why AWS remains the core valuation driver. Revenue hit $42.23 billion against expectations of $40.54 billion, representing 37% year-over-year growth that accelerated meaningfully from 28% in the prior quarter. The stock responded with a double-digit surge as CEO Andy Jassy signaled confidence by guiding full-year capex to $220 billion.
Apple posted strong headline numbers in the same window with $109.4 billion in revenue and iPhone sales climbing 22%, but the market focused on what was missing. Services revenue came in at $30.74 billion versus estimates of $31.22 billion, and forward guidance of 9-11% growth disappointed analysts looking for 12%. Management cited foreign exchange headwinds and supply constraints as the primary drags on near-term momentum.
The divergent reactions show how differently the market is weighting these businesses right now. Amazon's acceleration in cloud growth validates capital expenditure plans because the revenue conversion is visible and immediate. Apple's hardware strength matters less when the higher-margin services segment stumbles and forward visibility gets murky. Investors are currently prioritizing proven infrastructure monetization over consumer device cycles, even when those cycles are beating top-line expectations.
Not financial advice. For informational and educational purposes only.
$DECK daily pick: sell Dec 18 $75 put (buy-side)
$DECK: I'm selling the Dec 18 $75 put and getting paid to wait on the @hoka and @UGG owner. As of Friday's close ($81.09, markets are closed today): 19% below the 200-day and 34% off the February high Credit $1.90 for ~2.5% in 54 days (~17% annualized) Breakeven $73.10, about 10% below Friday About 10.5x this fiscal year's EPS estimate…
S&P 500 up after all 19 midterms since 1950; at a 70% base rate that streak is roughly 1 in 880
With US midterms on November 3, traders are sharing the stat that the S&P 500 rose in the 12 months after all 19…
S&P Global US Manufacturing PMI hits 56.0 in October, beating the 55.5 consensus by half a point
US manufacturing PMI hit 56.0 in October, the highest since May 2022. The Street expected a dip. Factory hiring was…
Energy Leads Alone as Defensives Lag
Energy led all sectors at +2.60%, more than five times the next-best gain in Information Technology (+0.49%), while eight of eleven sectors finished negative.
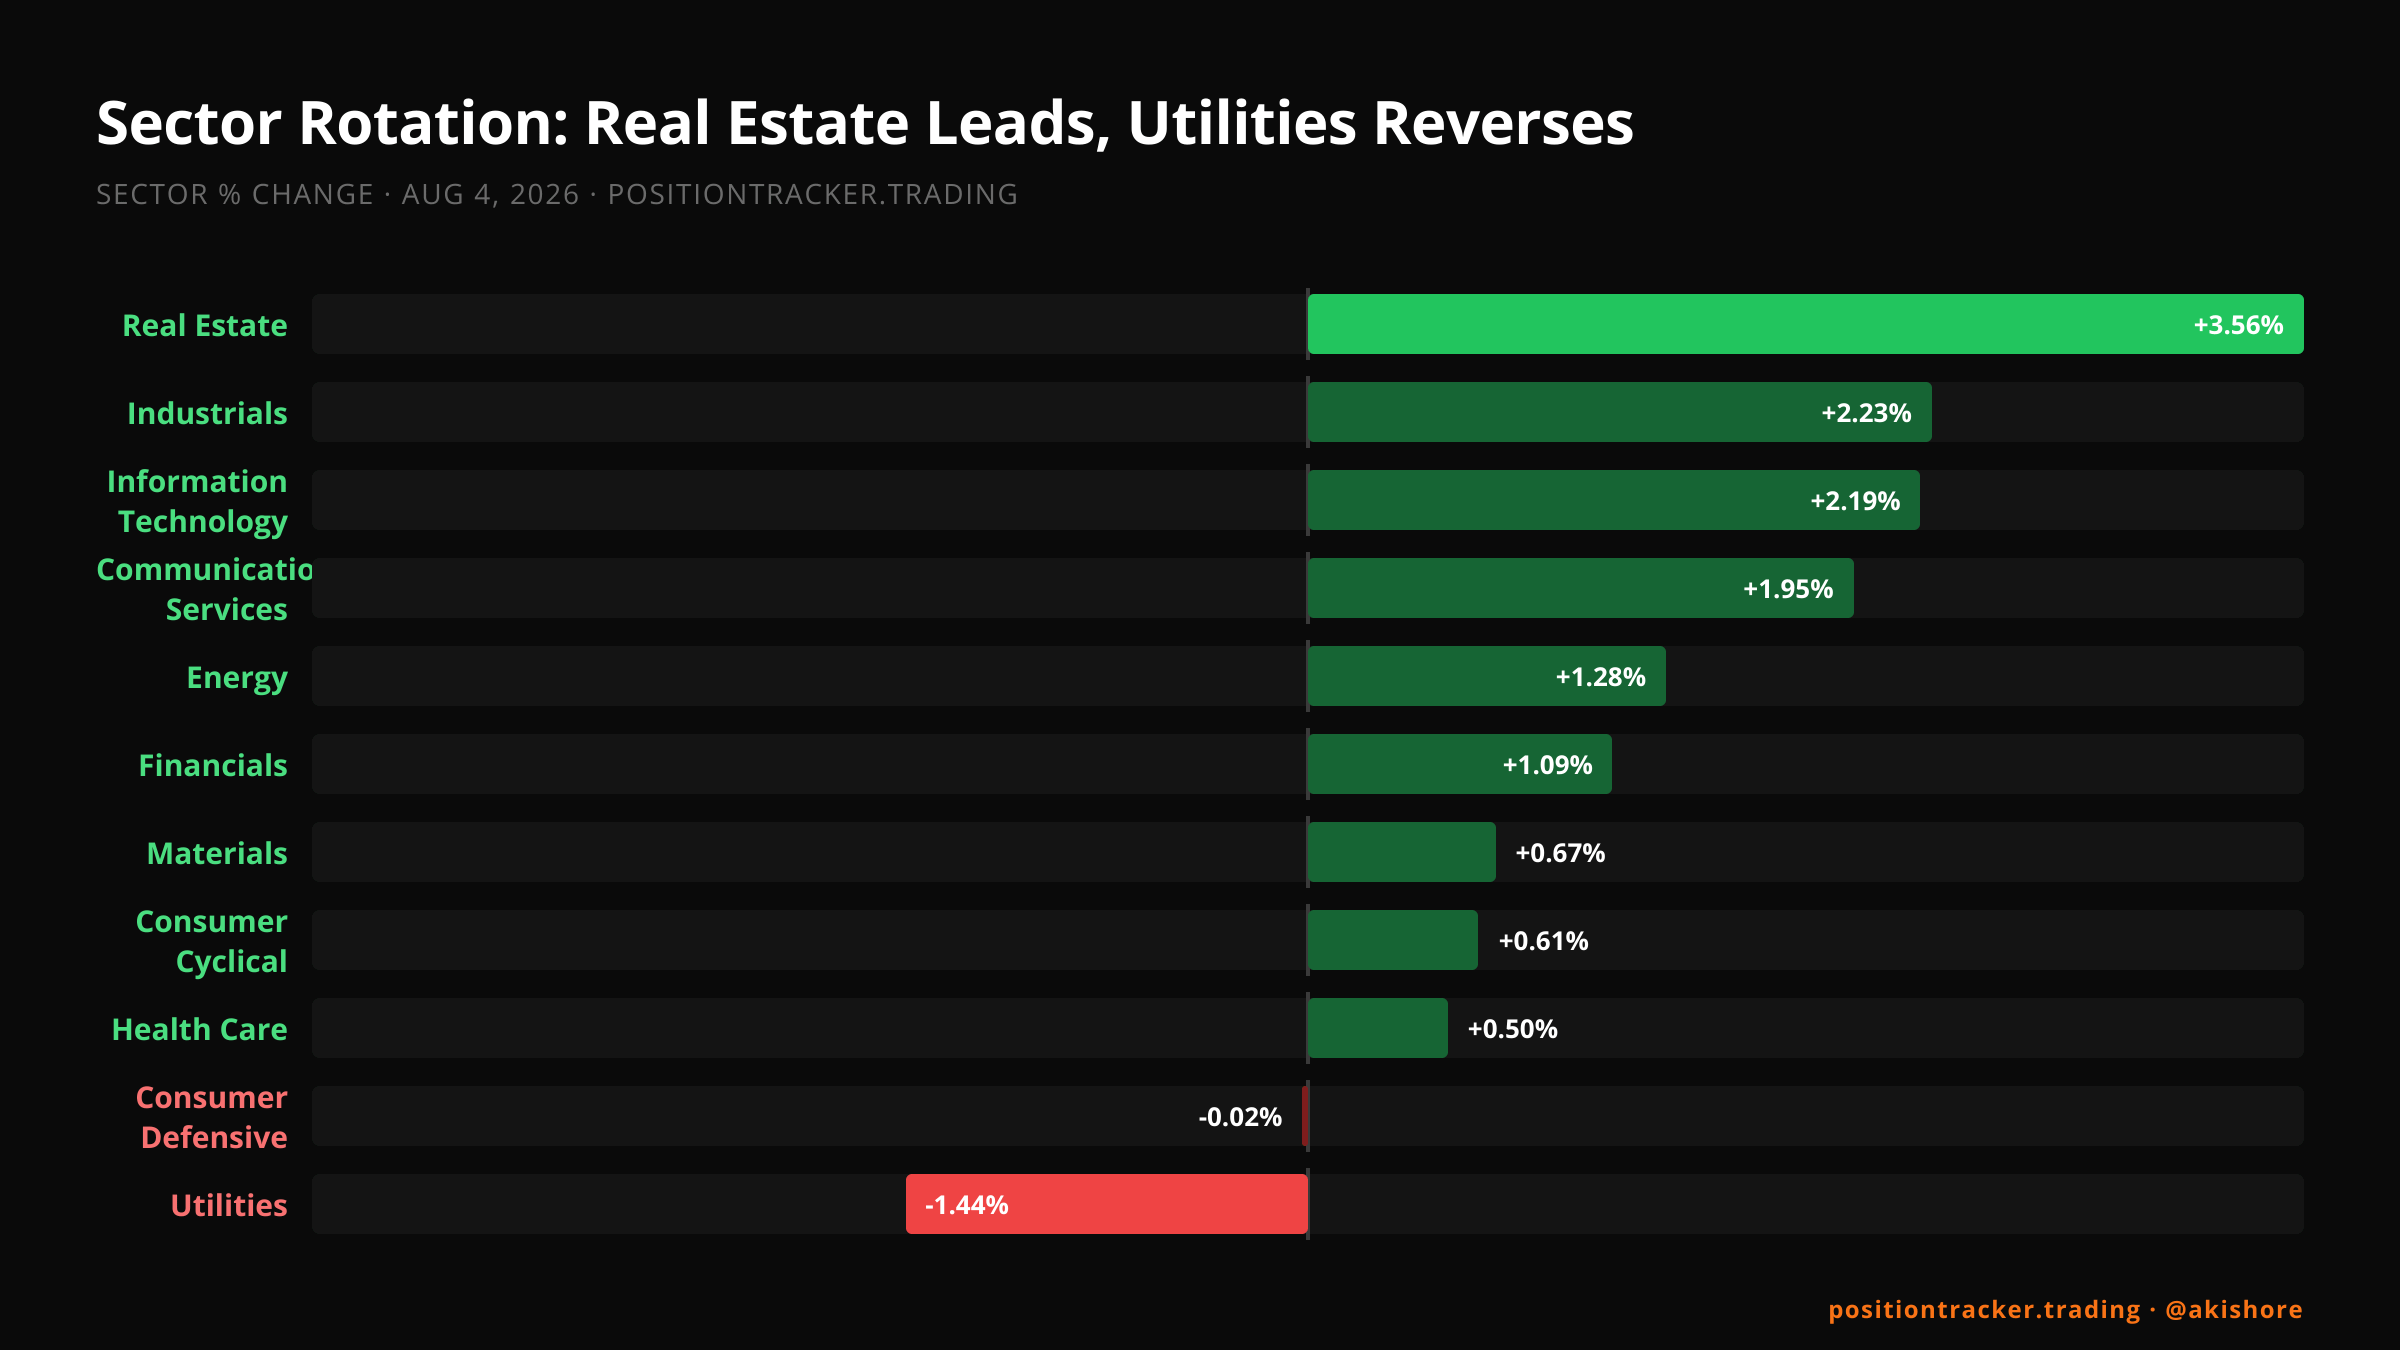
Energy returned +2.60% in Friday's session, the largest gain among all tracked sectors and more than five times the next-best, Information Technology at +0.49%. Only three of eleven sectors finished positive, with Real Estate barely in the green at +0.12%. The narrowness…