Booking Holdings ($BKNG): buy now, add down to $135, long term
$BKNG: I think this is a buy right here.
15% below its 200-day
17x earnings vs a ~40x 5-yr avg
$9.5B of free cash flow in a year
I think AI agents need its hotels and payments more than it needs them.
Would you buy Booking at $152?
Not financial advice
Bear case: Expedia teamed up with Meta's Muse AI agent on Sep 22 so people can book trips inside the assistant. Booking has no matching deal yet and the stock fell about 4% to 5% the next day. An EU court also upheld the block on its ETraveli flights deal.
Chart + wave read: I read the drop from the $234 top in July 2025 as an A-B-C. A bottomed at $150 in May, B bounced to $217 in August and C is at $152 now. That's the 78.6% retrace of the 2024-25 run ($150) and C = A projects $134. The 50 and 200-day are rolling over near $177.
The business: a 34.5% operating margin, revenue up 12.9% over the last year and 8.1% last quarter. Free cash flow was $9.5B, about an 8% yield at this price. Net debt is only about 0.3x EBITDA. Q3 results come Nov 3 after the close.
My plan: I'd start a position here and add down to $135, where the 78.6% retrace, the C = A target and the early 2024 base line up. Earnings could hand me a better price, so I'd buy in pieces. A weekly close below $127, the Aug 2024 low, means I'm wrong. Multi-year hold.
Sources: Booking Holdings IR: Q3 2026 results on Nov 3 · StockAnalysis: BKNG stats, earnings date Nov 3 · MarketBeat: BKNG Q3 2026 earnings date · Investing.com: Booking slides on Expedia and Meta Muse deal · TIKR: BKNG drops as Expedia partners with Meta's Muse · CNBC: Booking seen as AI victim, data suggests otherwise
Not financial advice. For informational and educational purposes only.
Verizon Q3: phone adds nearly double estimates while revenue misses
$VZ added 406K postpaid phones vs 209K expected, beat on EPS ($1.31 vs $1.27) and raised its…
Video explainer: @AnthropicAI just made its IPO filing public. $16.3B in revenue next to an $80.7B loss in just six months.
@AnthropicAI just made its IPO filing public. $16.3B in revenue next to an $80.7B loss in just six months. It plans to list on the @Nasdaq as $ANT with @GoldmanSachs and @MorganStanley leading. Per @CNBC marketing could start the week of Nov 9.
Oil Shocks of the 1970s — CPI Then vs Now
Crude oil near $101.58 a barrel and CPI at 3.7% year-over-year still look tame next to the 1970s.
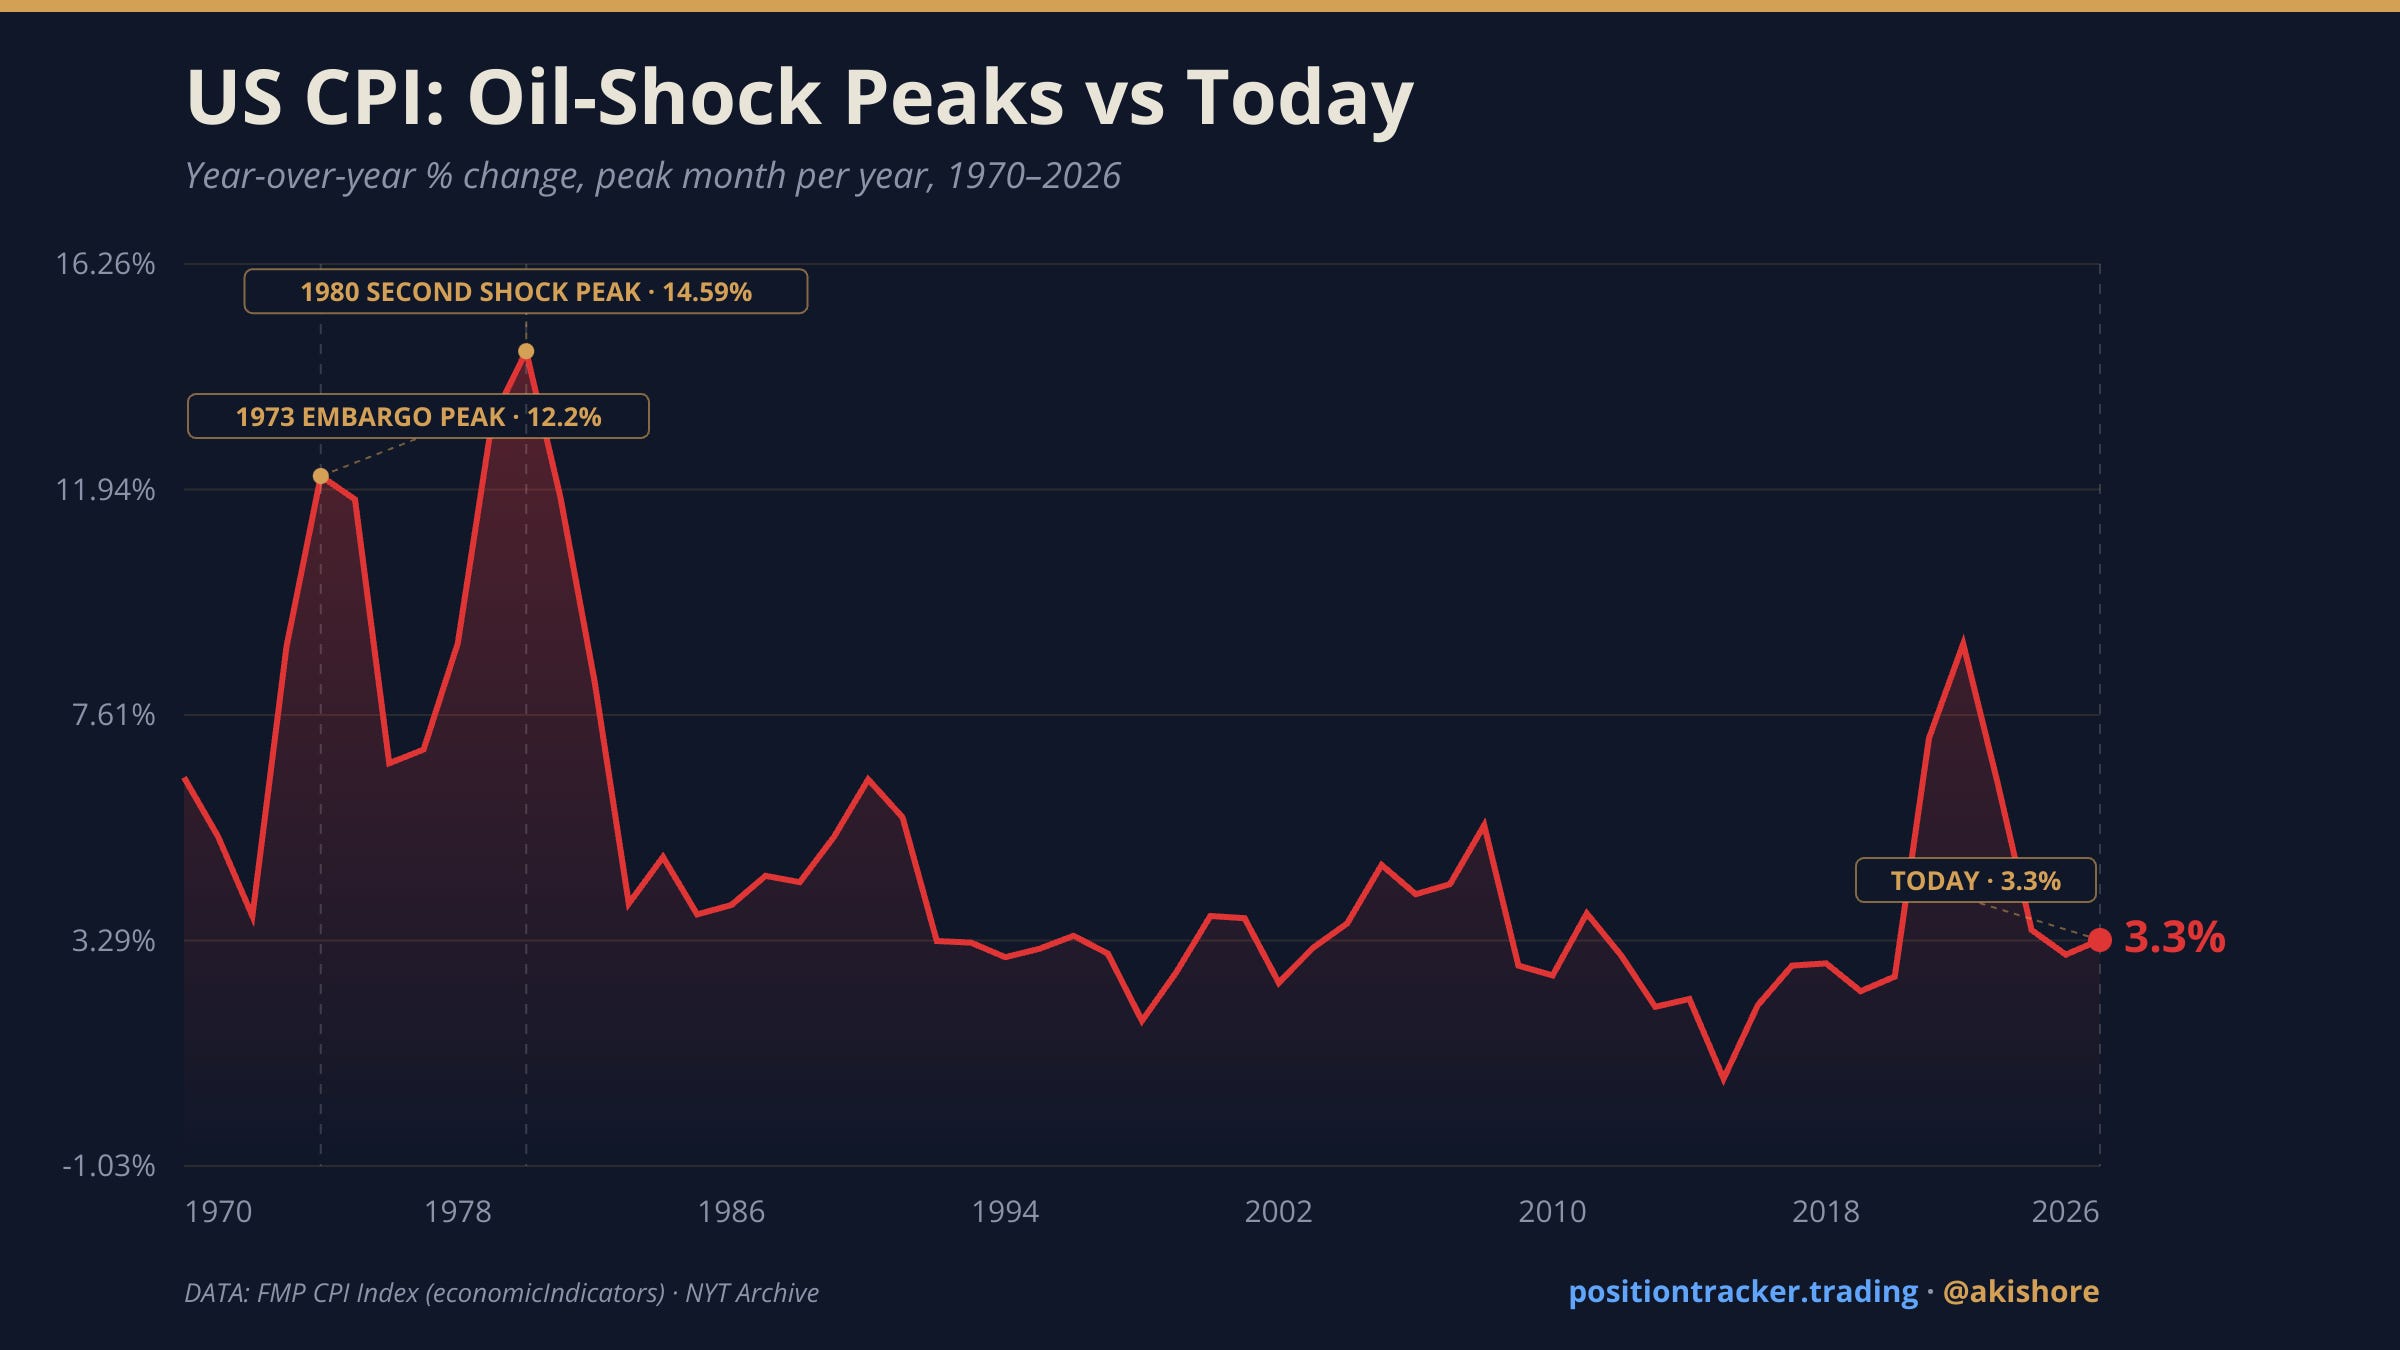
Crude oil near $101.58 a barrel and CPI at 3.7% year-over-year still look tame next to the 1970s. But September's inflation print is moving the wrong way, and energy is a big reason why. The latest CPI, for September, came in at 3.7% year-over-year, up from 3.4% in August, with prices up 0.6% on the…
Afternoon update
Brazil's election result and an AI-lab IPO filing set the direction for Monday afternoon's session.
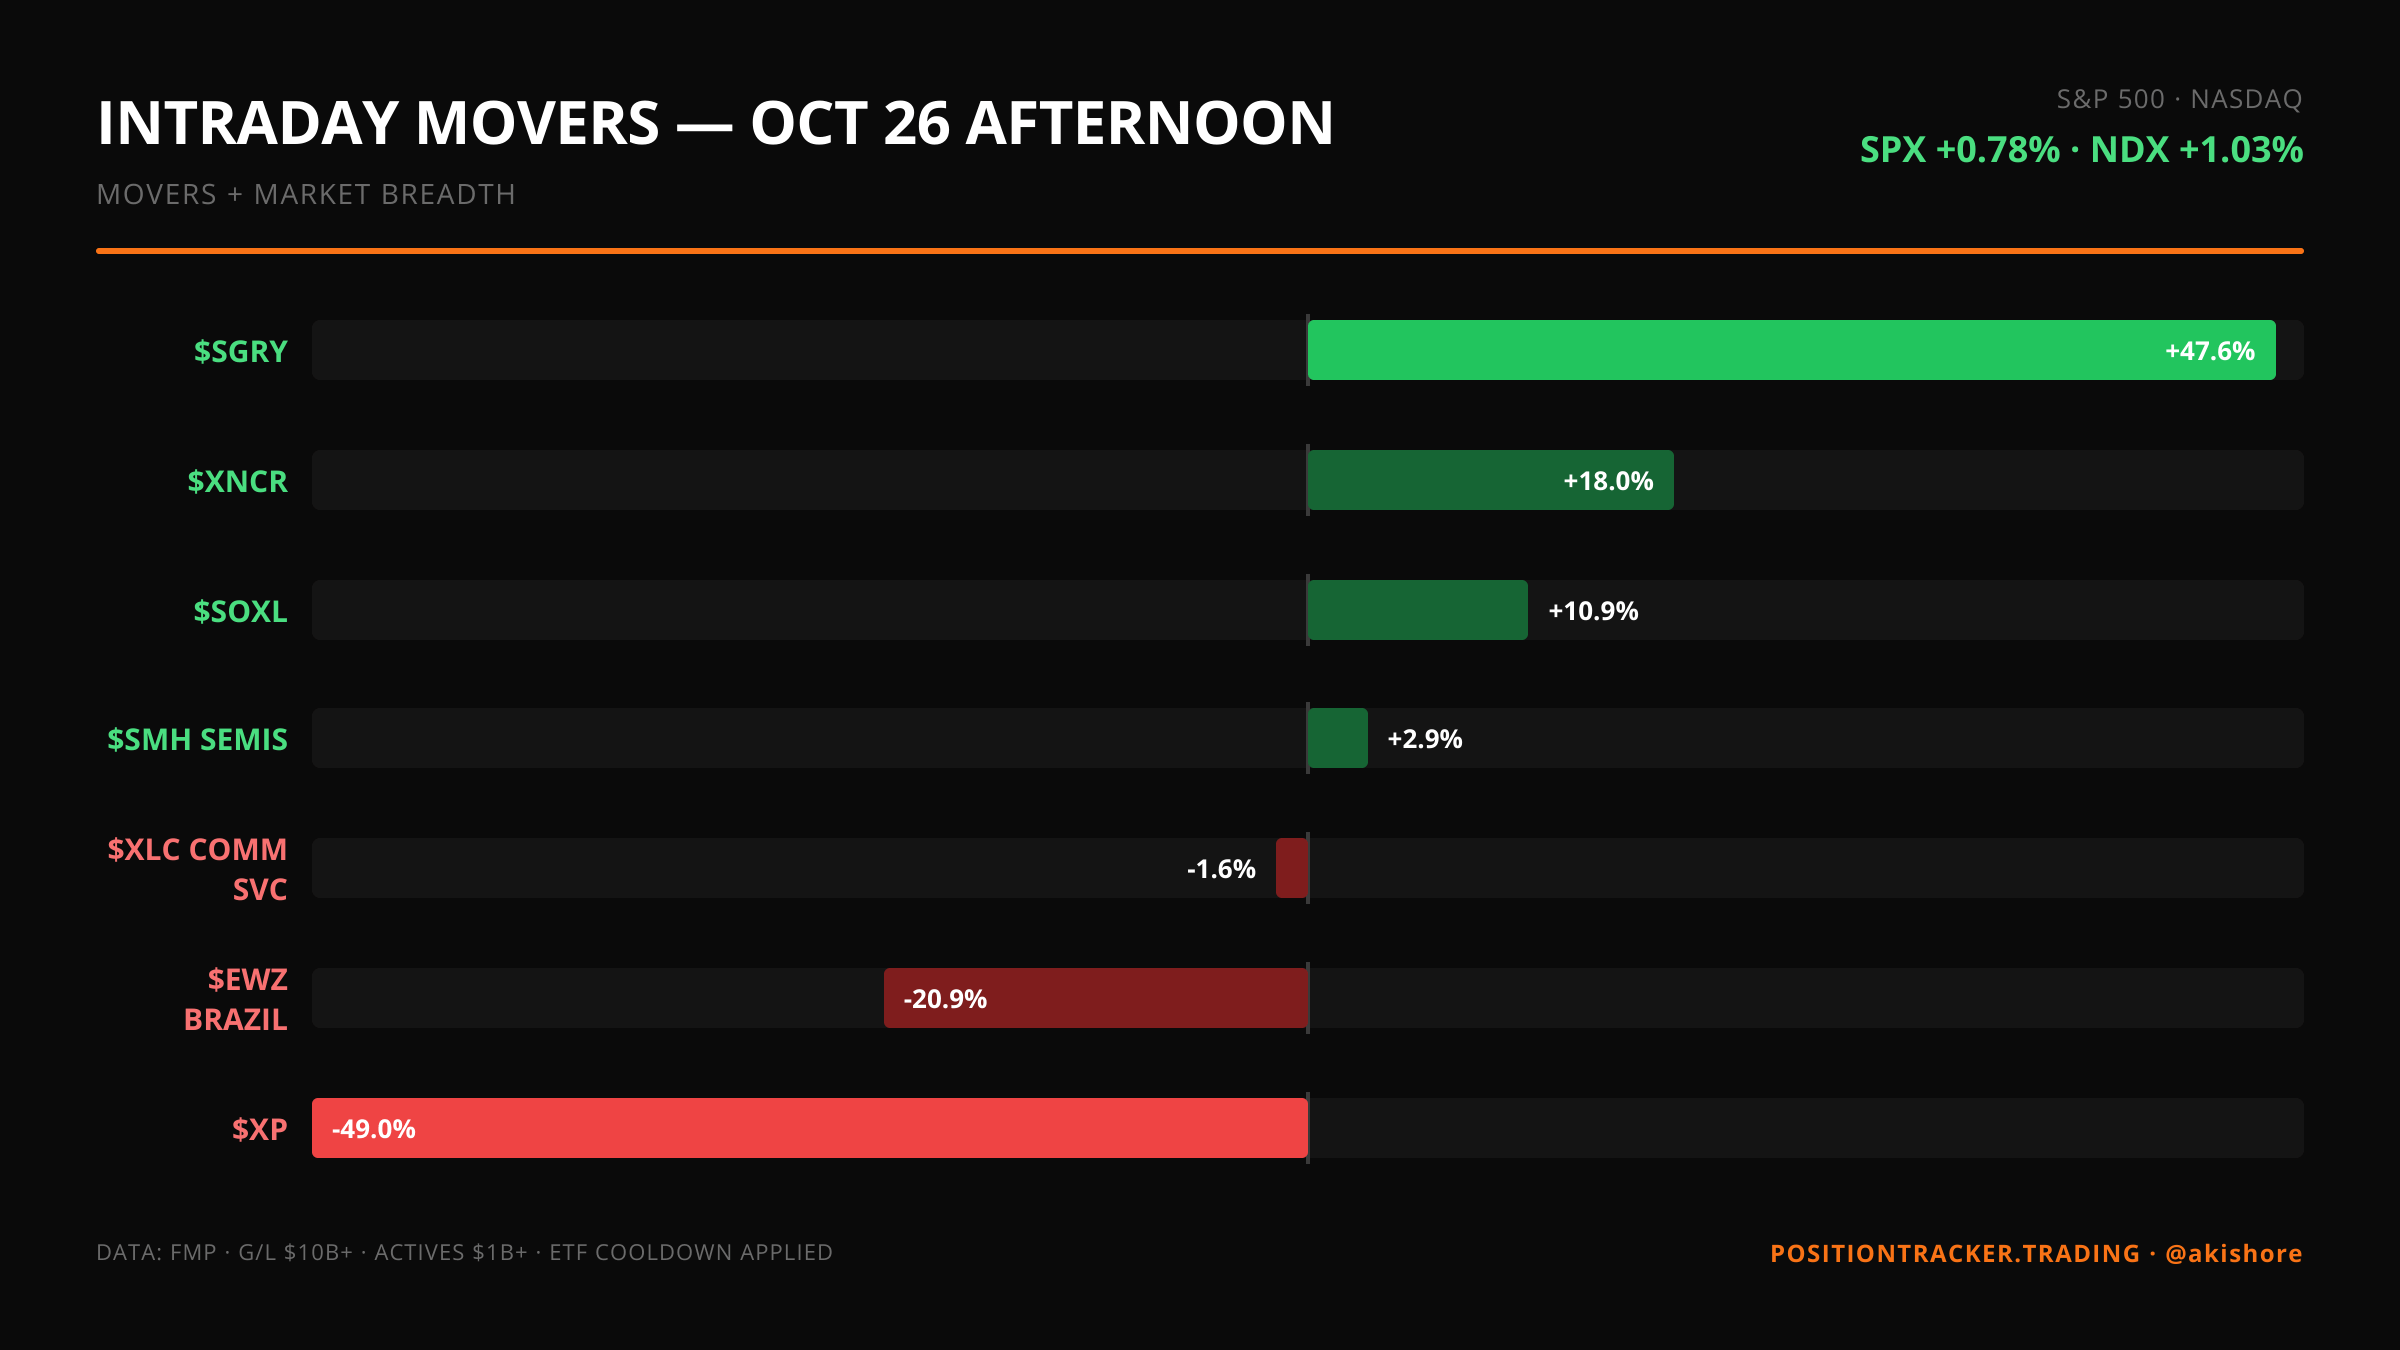
Brazil's election result and an AI-lab IPO filing set the direction for Monday afternoon's session. The S&P 500 rose 0.78% and the Nasdaq gained 1.03%. $XP fell 49.0% after Lula won reelection in an upset over Flavio Bolsonaro. The $7.9B broker had rallied the…