I think Bank of America makes a bold case that $NVDA is undervalued by 55%.
I think Bank of America makes a bold case that $NVDA is undervalued by 55%. They believe we should view Nvidia as an infrastructure owner instead of just a chip seller.
Analyst Vivek Arya set a $350 price target based on this shift. That implies significant upside from Monday’s close before the next earnings report.
This thesis relies on structural advantages beyond simple GPU sales:
- Control over data center land and power
- Ownership of the full infrastructure stack
- Cash flow generation past hardware cycles
BofA projects $470 billion in combined free cash flow for 2026 and 2027. This looks well beyond near-term hardware demand.
We get a direct test of this view when Q2 earnings arrive on August 26. The bank forecasts $94 to $95 billion in revenue versus official guidance of $91 billion.
Everything hinges on whether the market accepts this platform framing over old chip models. Do you think that is a reasonable target for Nvidia? What time frame?
Not financial advice. For informational and educational purposes only.
$DECK daily pick: sell Dec 18 $75 put (buy-side)
$DECK: I'm selling the Dec 18 $75 put and getting paid to wait on the @hoka and @UGG owner. As of Friday's close ($81.09, markets are closed today): 19% below the 200-day and 34% off the February high Credit $1.90 for ~2.5% in 54 days (~17% annualized) Breakeven $73.10, about 10% below Friday About 10.5x this fiscal year's EPS estimate…
S&P 500 up after all 19 midterms since 1950; at a 70% base rate that streak is roughly 1 in 880
With US midterms on November 3, traders are sharing the stat that the S&P 500 rose in the 12 months after all 19…
S&P Global US Manufacturing PMI hits 56.0 in October, beating the 55.5 consensus by half a point
US manufacturing PMI hit 56.0 in October, the highest since May 2022. The Street expected a dip. Factory hiring was…
Energy Leads Alone as Defensives Lag
Energy led all sectors at +2.60%, more than five times the next-best gain in Information Technology (+0.49%), while eight of eleven sectors finished negative.
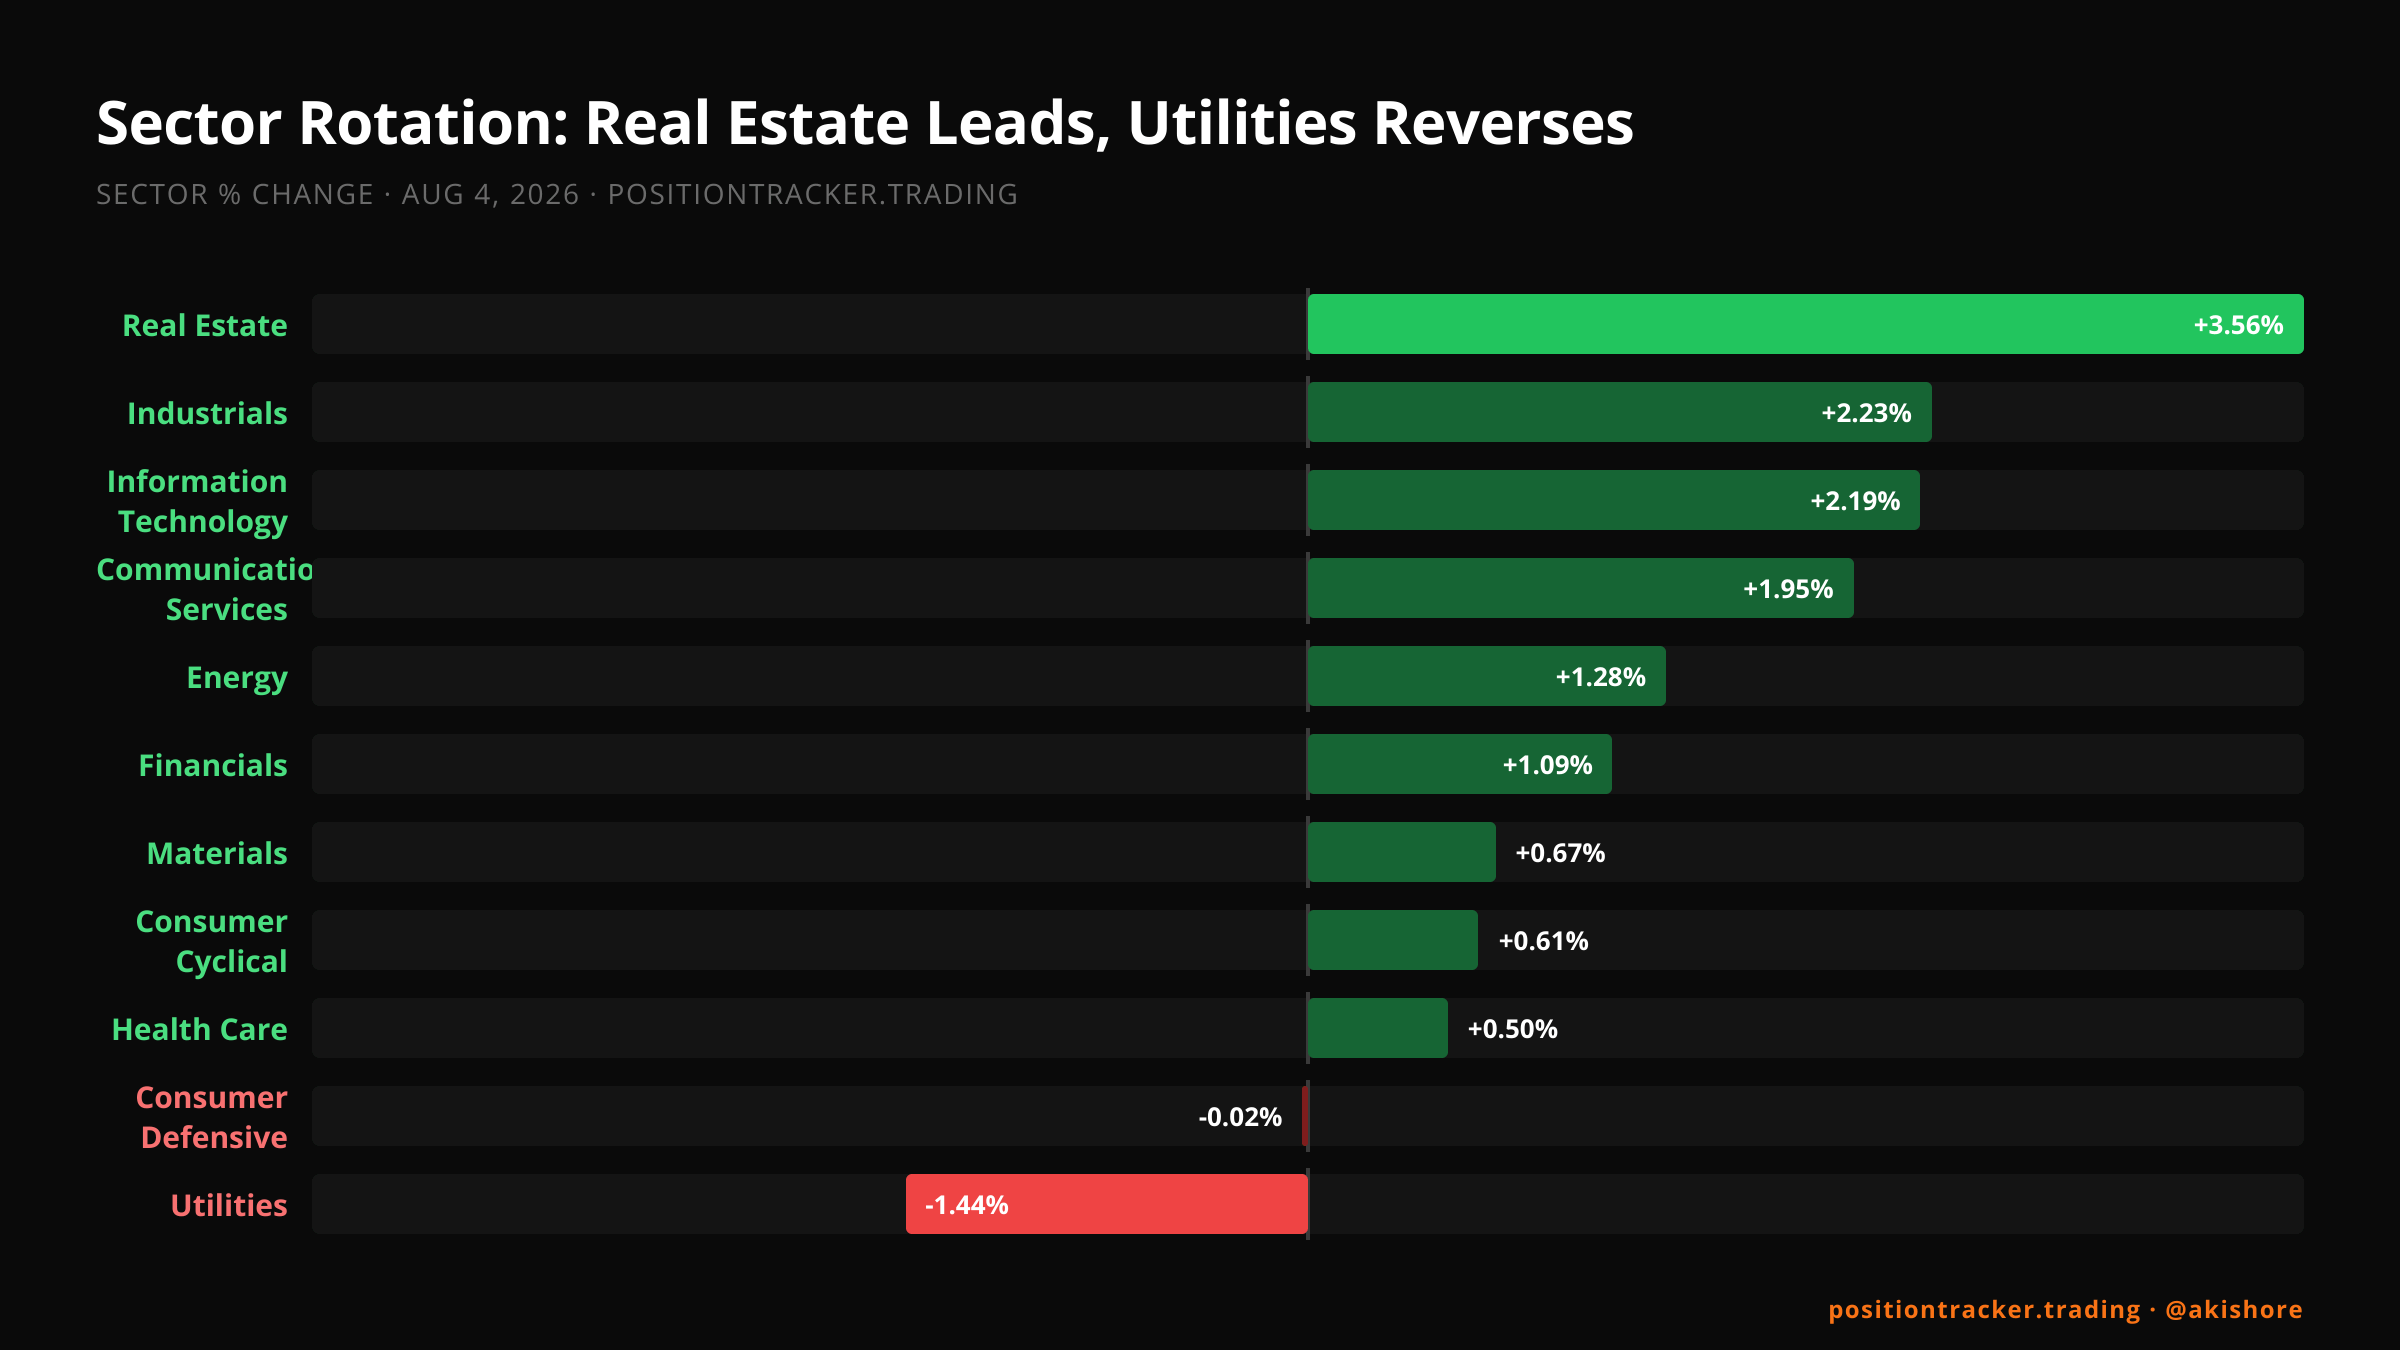
Energy returned +2.60% in Friday's session, the largest gain among all tracked sectors and more than five times the next-best, Information Technology at +0.49%. Only three of eleven sectors finished positive, with Real Estate barely in the green at +0.12%. The narrowness…