Intel just delivered its fastest quarterly revenue growth in more than fifteen years, but the market reaction has been volatile.
Intel just delivered its fastest quarterly revenue growth in more than fifteen years, but the market reaction has been volatile. Q2 2026 revenue came in at $16.1 billion, up 25% year-over-year, while adjusted earnings per share of 42 cents roughly doubled Wall Street's 21-cent consensus. The data center and AI segment was the standout performer with 59% growth to $6.3 billion, and even the mature client computing business managed a respectable 13% increase to $8.9 billion.
What really caught my attention was the forward guidance. Intel projected Q3 revenue between $15.8 billion and $16.8 billion against a $15.1 billion consensus, alongside adjusted EPS guidance of 38 cents versus the expected 27 cents. That upside surprise initially sparked a 13% after-hours spike, but shares have since reversed and are now down 3.6% as investors weigh raised CapEx plans above $20 billion against the beat. It suggests the turnaround narrative is gaining operational traction, yet heavy spending commitments remain a concern.
Yet I cannot ignore the massive gap between adjusted profitability and GAAP reality. Despite the operational beat, Intel reported an $11 billion GAAP net loss and negative $2.16 per share. This tells me that while the core business momentum is undeniable, the company is still absorbing enormous restructuring and investment costs. Investors are choosing to look through the GAAP pain for now, but sustainable success will require closing that accounting gap eventually.
Not financial advice. For informational and educational purposes only.
$DECK daily pick: sell Dec 18 $75 put (buy-side)
$DECK: I'm selling the Dec 18 $75 put and getting paid to wait on the @hoka and @UGG owner. As of Friday's close ($81.09, markets are closed today): 19% below the 200-day and 34% off the February high Credit $1.90 for ~2.5% in 54 days (~17% annualized) Breakeven $73.10, about 10% below Friday About 10.5x this fiscal year's EPS estimate…
S&P 500 up after all 19 midterms since 1950; at a 70% base rate that streak is roughly 1 in 880
With US midterms on November 3, traders are sharing the stat that the S&P 500 rose in the 12 months after all 19…
S&P Global US Manufacturing PMI hits 56.0 in October, beating the 55.5 consensus by half a point
US manufacturing PMI hit 56.0 in October, the highest since May 2022. The Street expected a dip. Factory hiring was…
Energy Leads Alone as Defensives Lag
Energy led all sectors at +2.60%, more than five times the next-best gain in Information Technology (+0.49%), while eight of eleven sectors finished negative.
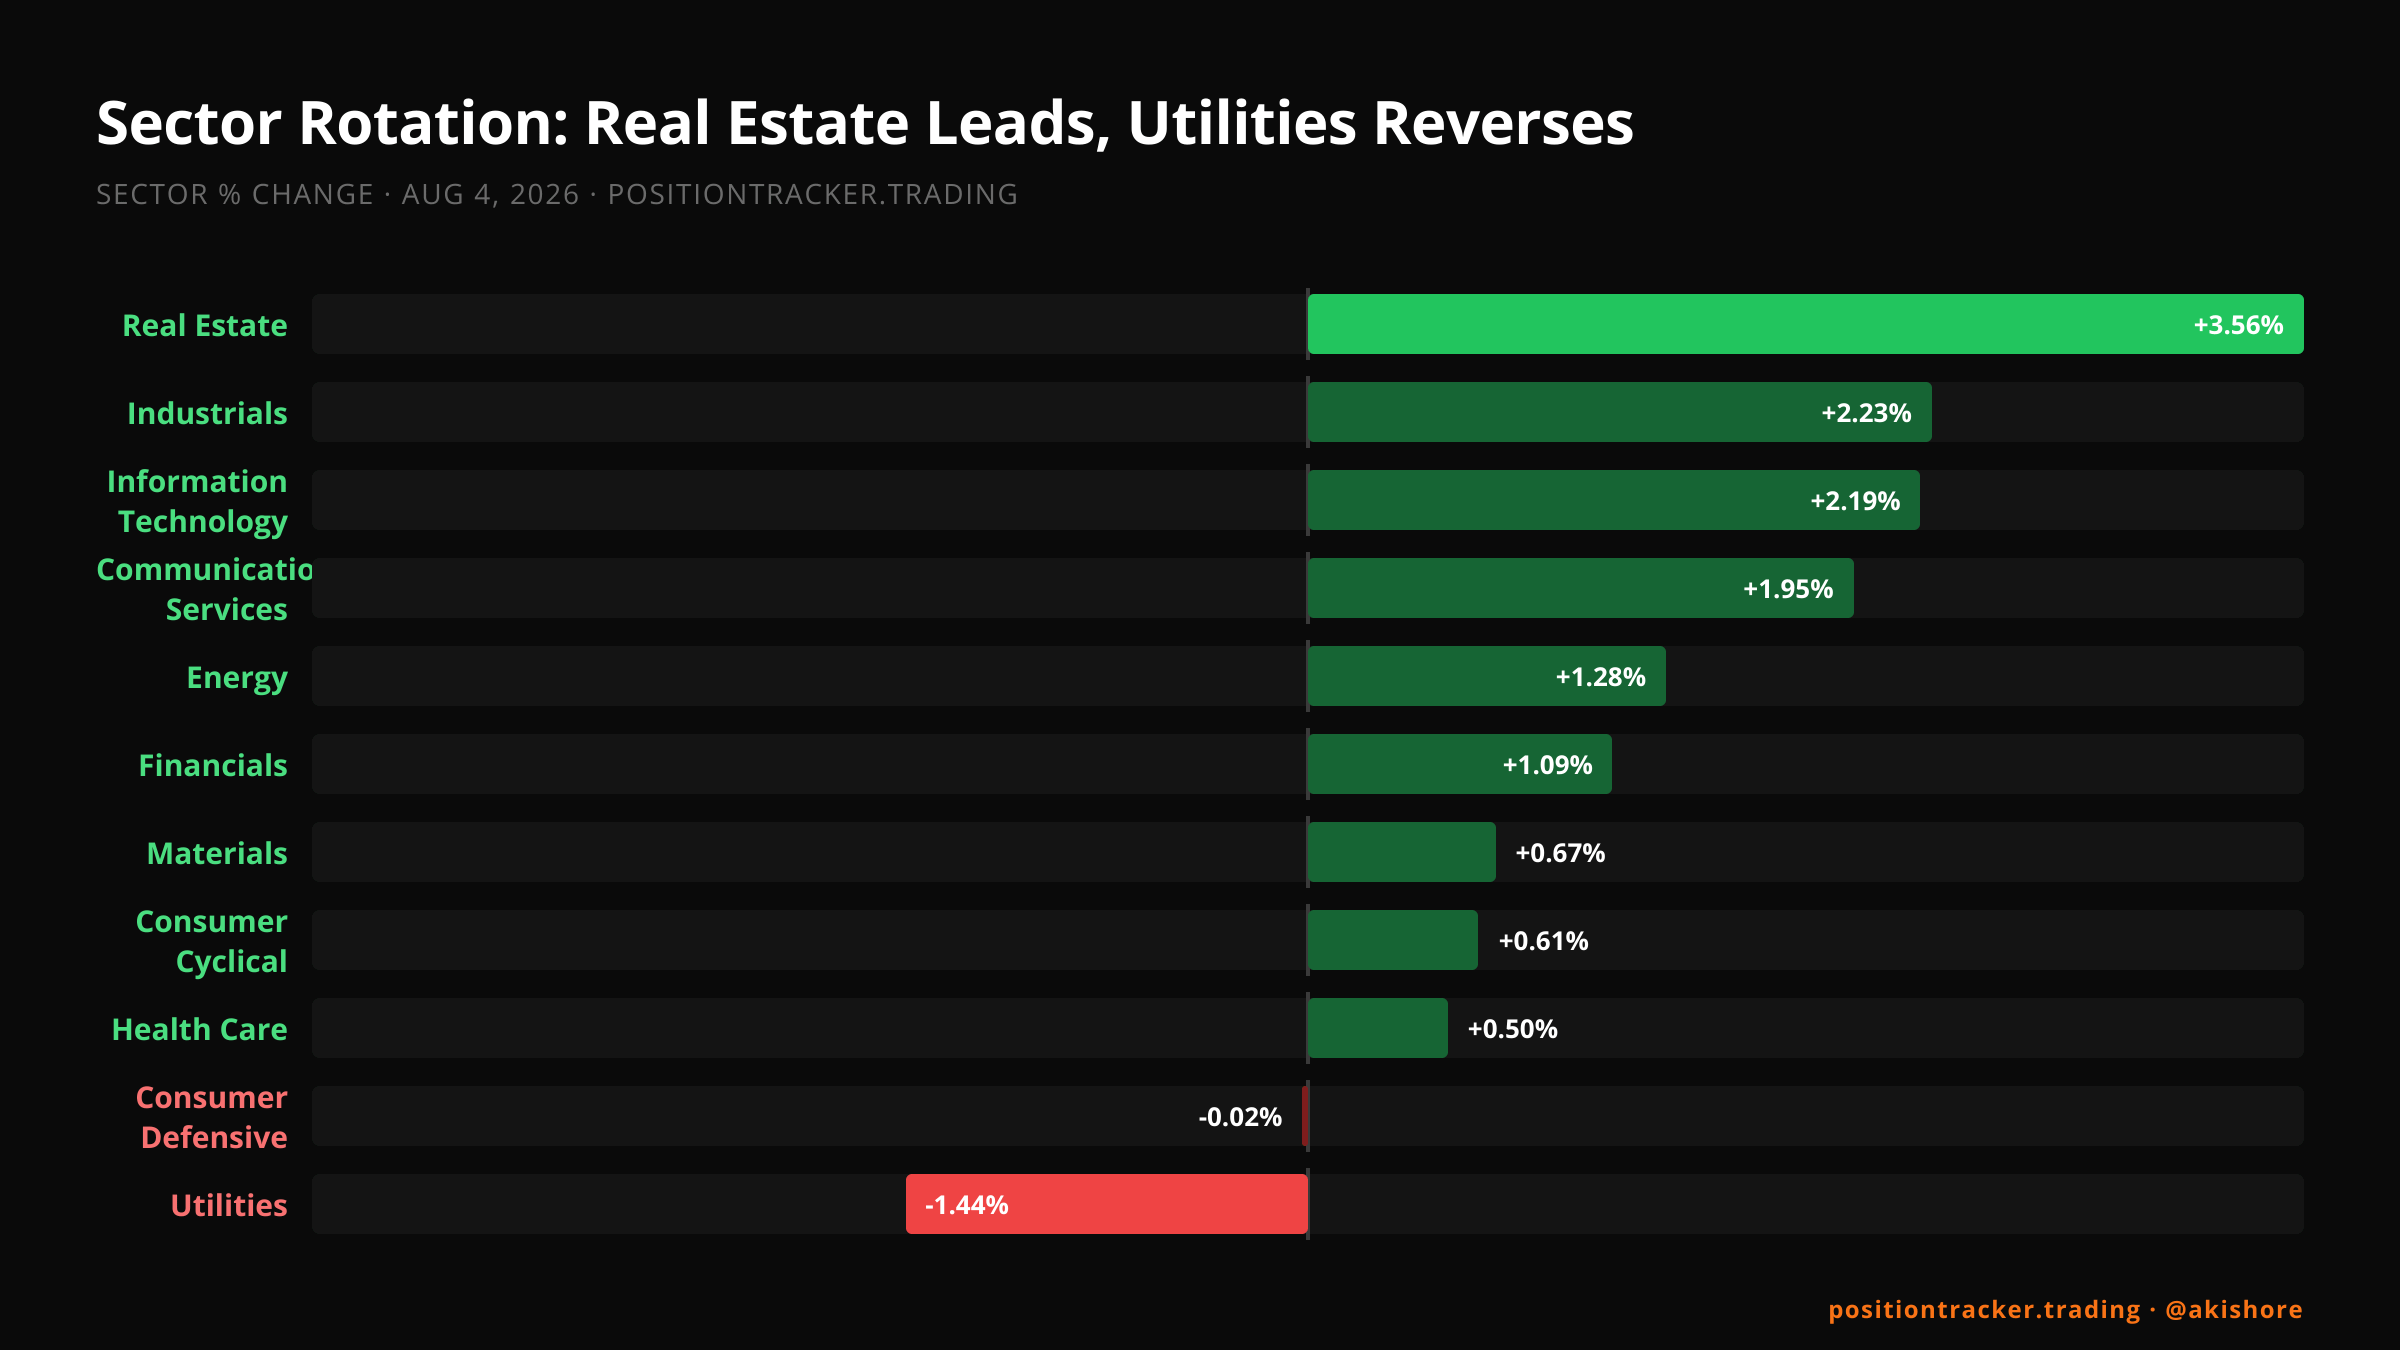
Energy returned +2.60% in Friday's session, the largest gain among all tracked sectors and more than five times the next-best, Information Technology at +0.49%. Only three of eleven sectors finished positive, with Real Estate barely in the green at +0.12%. The narrowness…