News hot-take
Microsoft shares jumped 9% yesterday and 2% up today in trading after fiscal fourth-quarter earnings and revenue beat analyst expectations. Azure surpassed $100 billion in revenue for fiscal 2026, while Microsoft's AI chatbot crossed 30 million paid seats.
Those are the numbers I would want to see if I were looking for evidence that AI adoption can translate into revenue and paying users. But the cash figures deserve equal attention too: free cash flow fell 23% to $19.64 billion, while capital expenditures reached $35.8 billion. That capex total was below FactSet expectations for more than $36 billion, but it still sits beside a sharp decline in free cash flow.
I keep coming back to this catch-22. Microsoft is showing visible AI monetization at the same time that pursuing it carries a substantial cash cost. The 9% premarket reaction says investors liked the report and I understand why!
My question is how long that enthusiasm lasts if paid seats keep climbing while free cash flow remains under pressure. At what point does the market demand more cash conversion from those AI milestones? Will it be a similar story to $META, just a few months down the line? $MSFT
Not financial advice. For informational and educational purposes only.
$DECK daily pick: sell Dec 18 $75 put (buy-side)
$DECK: I'm selling the Dec 18 $75 put and getting paid to wait on the @hoka and @UGG owner. As of Friday's close ($81.09, markets are closed today): 19% below the 200-day and 34% off the February high Credit $1.90 for ~2.5% in 54 days (~17% annualized) Breakeven $73.10, about 10% below Friday About 10.5x this fiscal year's EPS estimate…
S&P 500 up after all 19 midterms since 1950; at a 70% base rate that streak is roughly 1 in 880
With US midterms on November 3, traders are sharing the stat that the S&P 500 rose in the 12 months after all 19…
S&P Global US Manufacturing PMI hits 56.0 in October, beating the 55.5 consensus by half a point
US manufacturing PMI hit 56.0 in October, the highest since May 2022. The Street expected a dip. Factory hiring was…
Energy Leads Alone as Defensives Lag
Energy led all sectors at +2.60%, more than five times the next-best gain in Information Technology (+0.49%), while eight of eleven sectors finished negative.
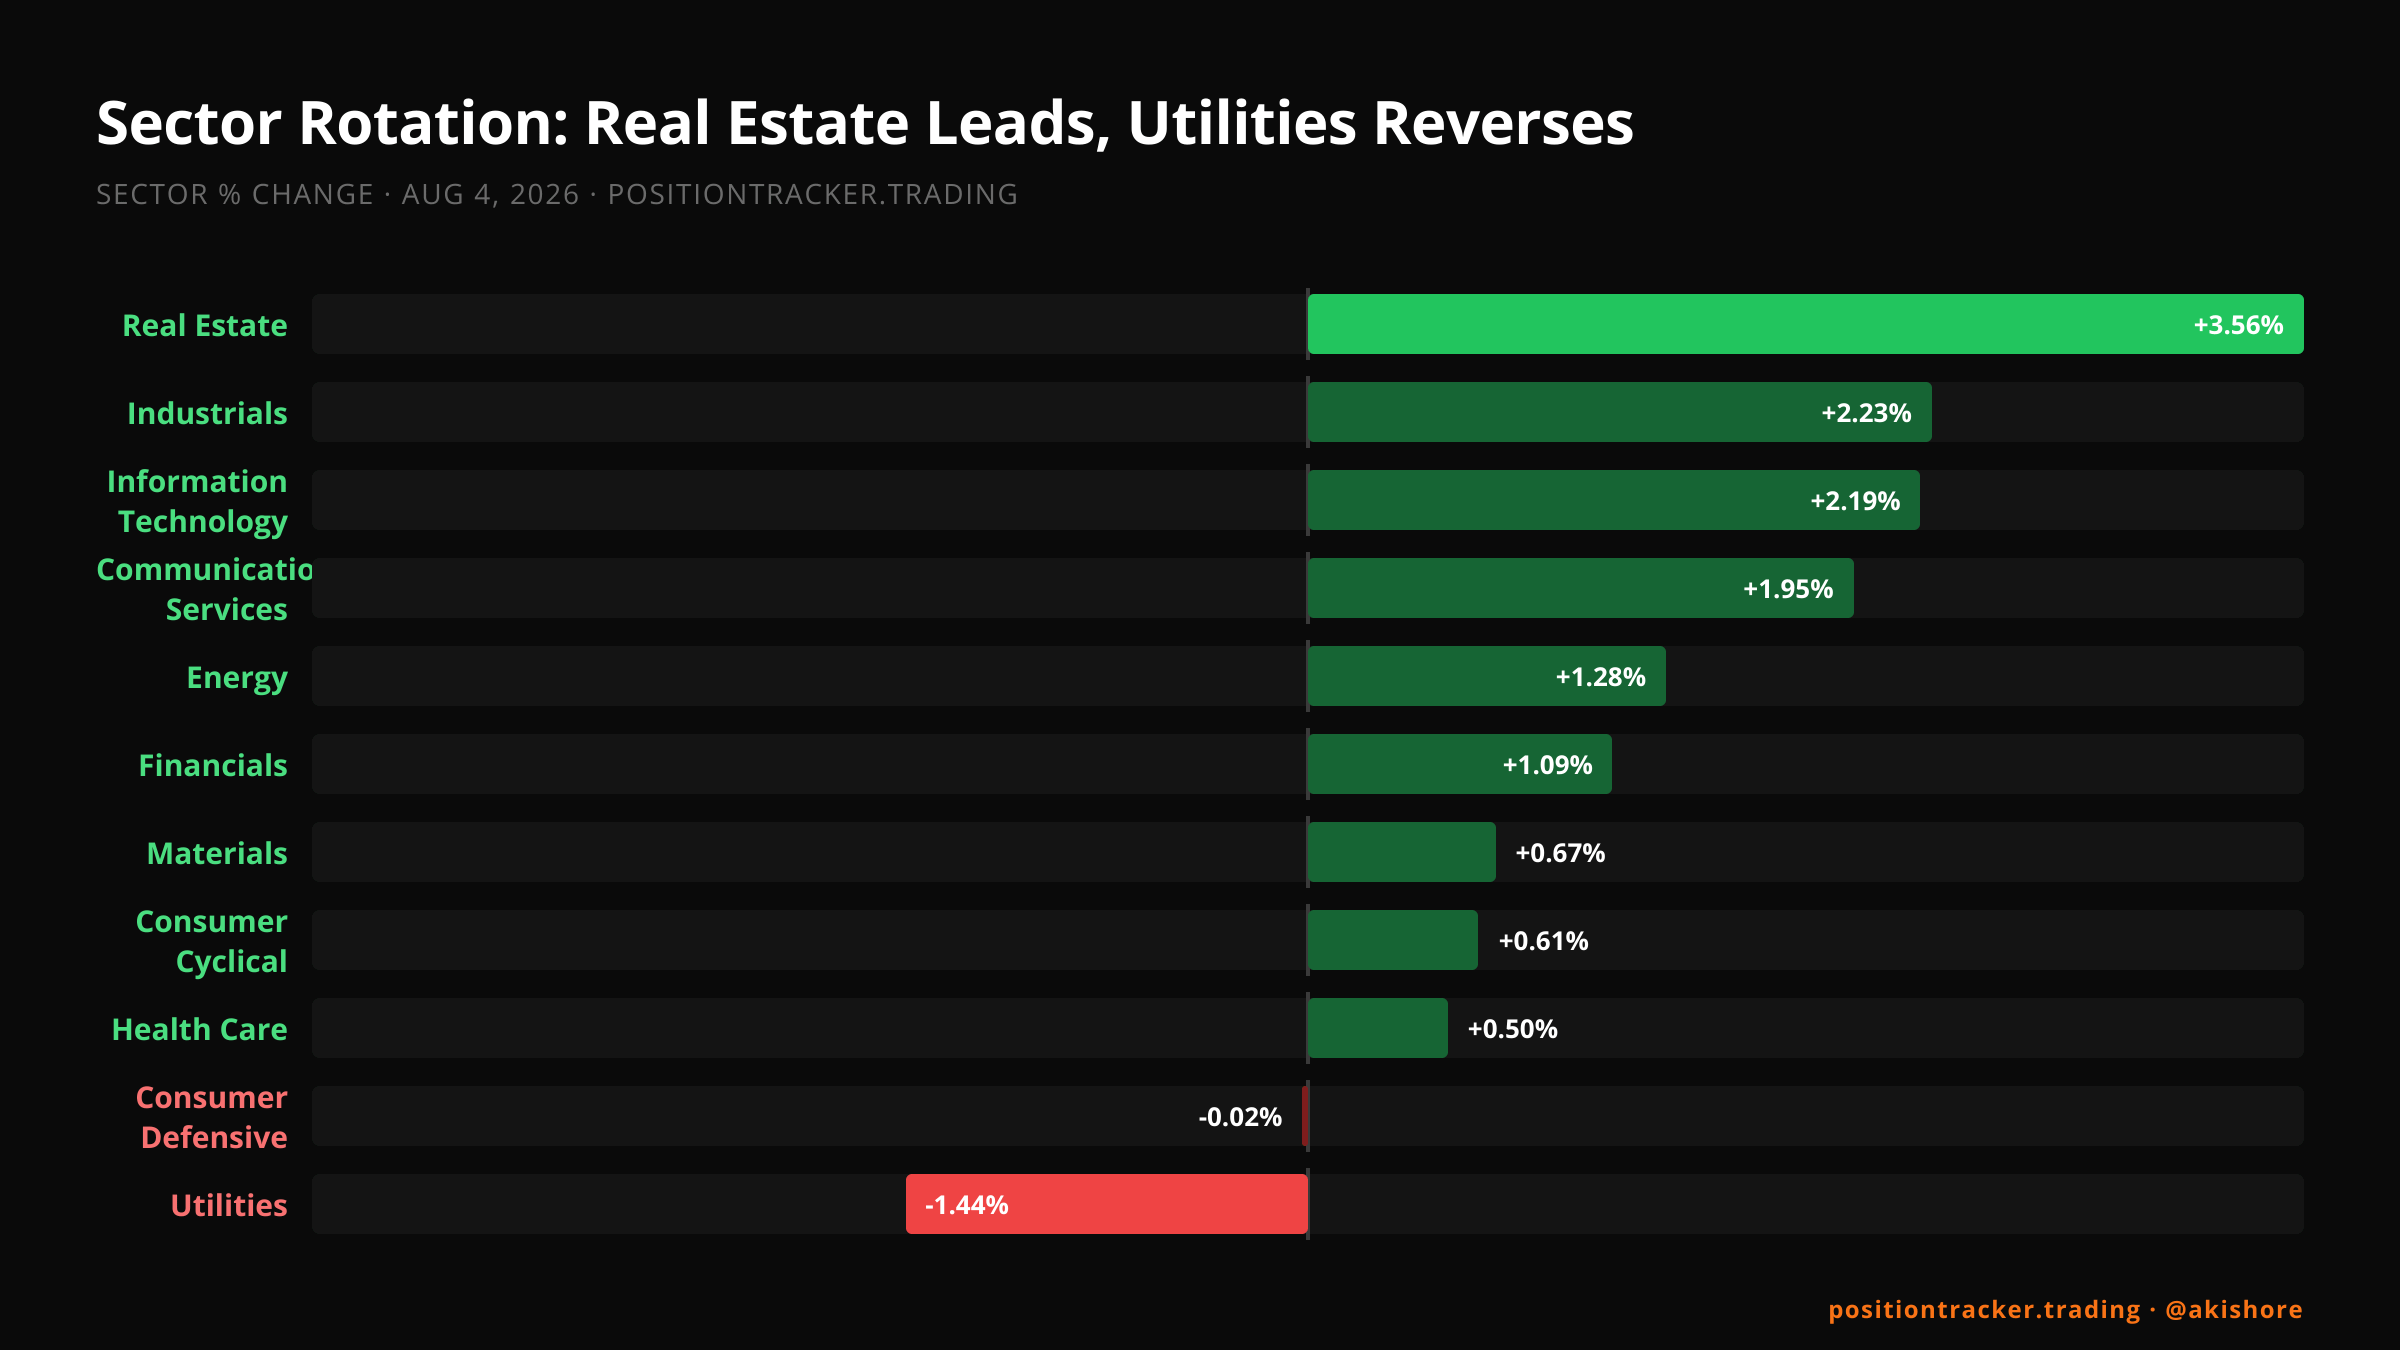
Energy returned +2.60% in Friday's session, the largest gain among all tracked sectors and more than five times the next-best, Information Technology at +0.49%. Only three of eleven sectors finished positive, with Real Estate barely in the green at +0.12%. The narrowness…