News hot-take
Reuters reported on July 30 that Meta's second-quarter free cash flow fell 91% and the shares are falling! WSJ separately reported that Meta anticipates about $137.5 billion of capital expenditures in 2026. Those two figures belong next to each other.
WSJ also cited FactSet analyst projections for negative free cash flow in the second half of 2026, which would be the first time since Meta's 2012 IPO. The same projections point to more than $20 billion of cash burn in 2027.
My read: the AI buildout is becoming a cash-flow judgment, not merely a product judgment. I can believe the spending is deliberate and still want a much clearer way to judge it. At $137.5 billion of anticipated capex, "invest now, explain later" feels like a harder pitch.
What I'm watching from here is simple: how much projected negative free cash flow will investors tolerate while they wait to see what this buildout produces? That is the tension in $META for me right now. The ambition is obvious. The acceptable cost of that ambition is the part investors now have to decide.
Not financial advice. For informational and educational purposes only.
$DECK daily pick: sell Dec 18 $75 put (buy-side)
$DECK: I'm selling the Dec 18 $75 put and getting paid to wait on the @hoka and @UGG owner. As of Friday's close ($81.09, markets are closed today): 19% below the 200-day and 34% off the February high Credit $1.90 for ~2.5% in 54 days (~17% annualized) Breakeven $73.10, about 10% below Friday About 10.5x this fiscal year's EPS estimate…
S&P 500 up after all 19 midterms since 1950; at a 70% base rate that streak is roughly 1 in 880
With US midterms on November 3, traders are sharing the stat that the S&P 500 rose in the 12 months after all 19…
S&P Global US Manufacturing PMI hits 56.0 in October, beating the 55.5 consensus by half a point
US manufacturing PMI hit 56.0 in October, the highest since May 2022. The Street expected a dip. Factory hiring was…
Energy Leads Alone as Defensives Lag
Energy led all sectors at +2.60%, more than five times the next-best gain in Information Technology (+0.49%), while eight of eleven sectors finished negative.
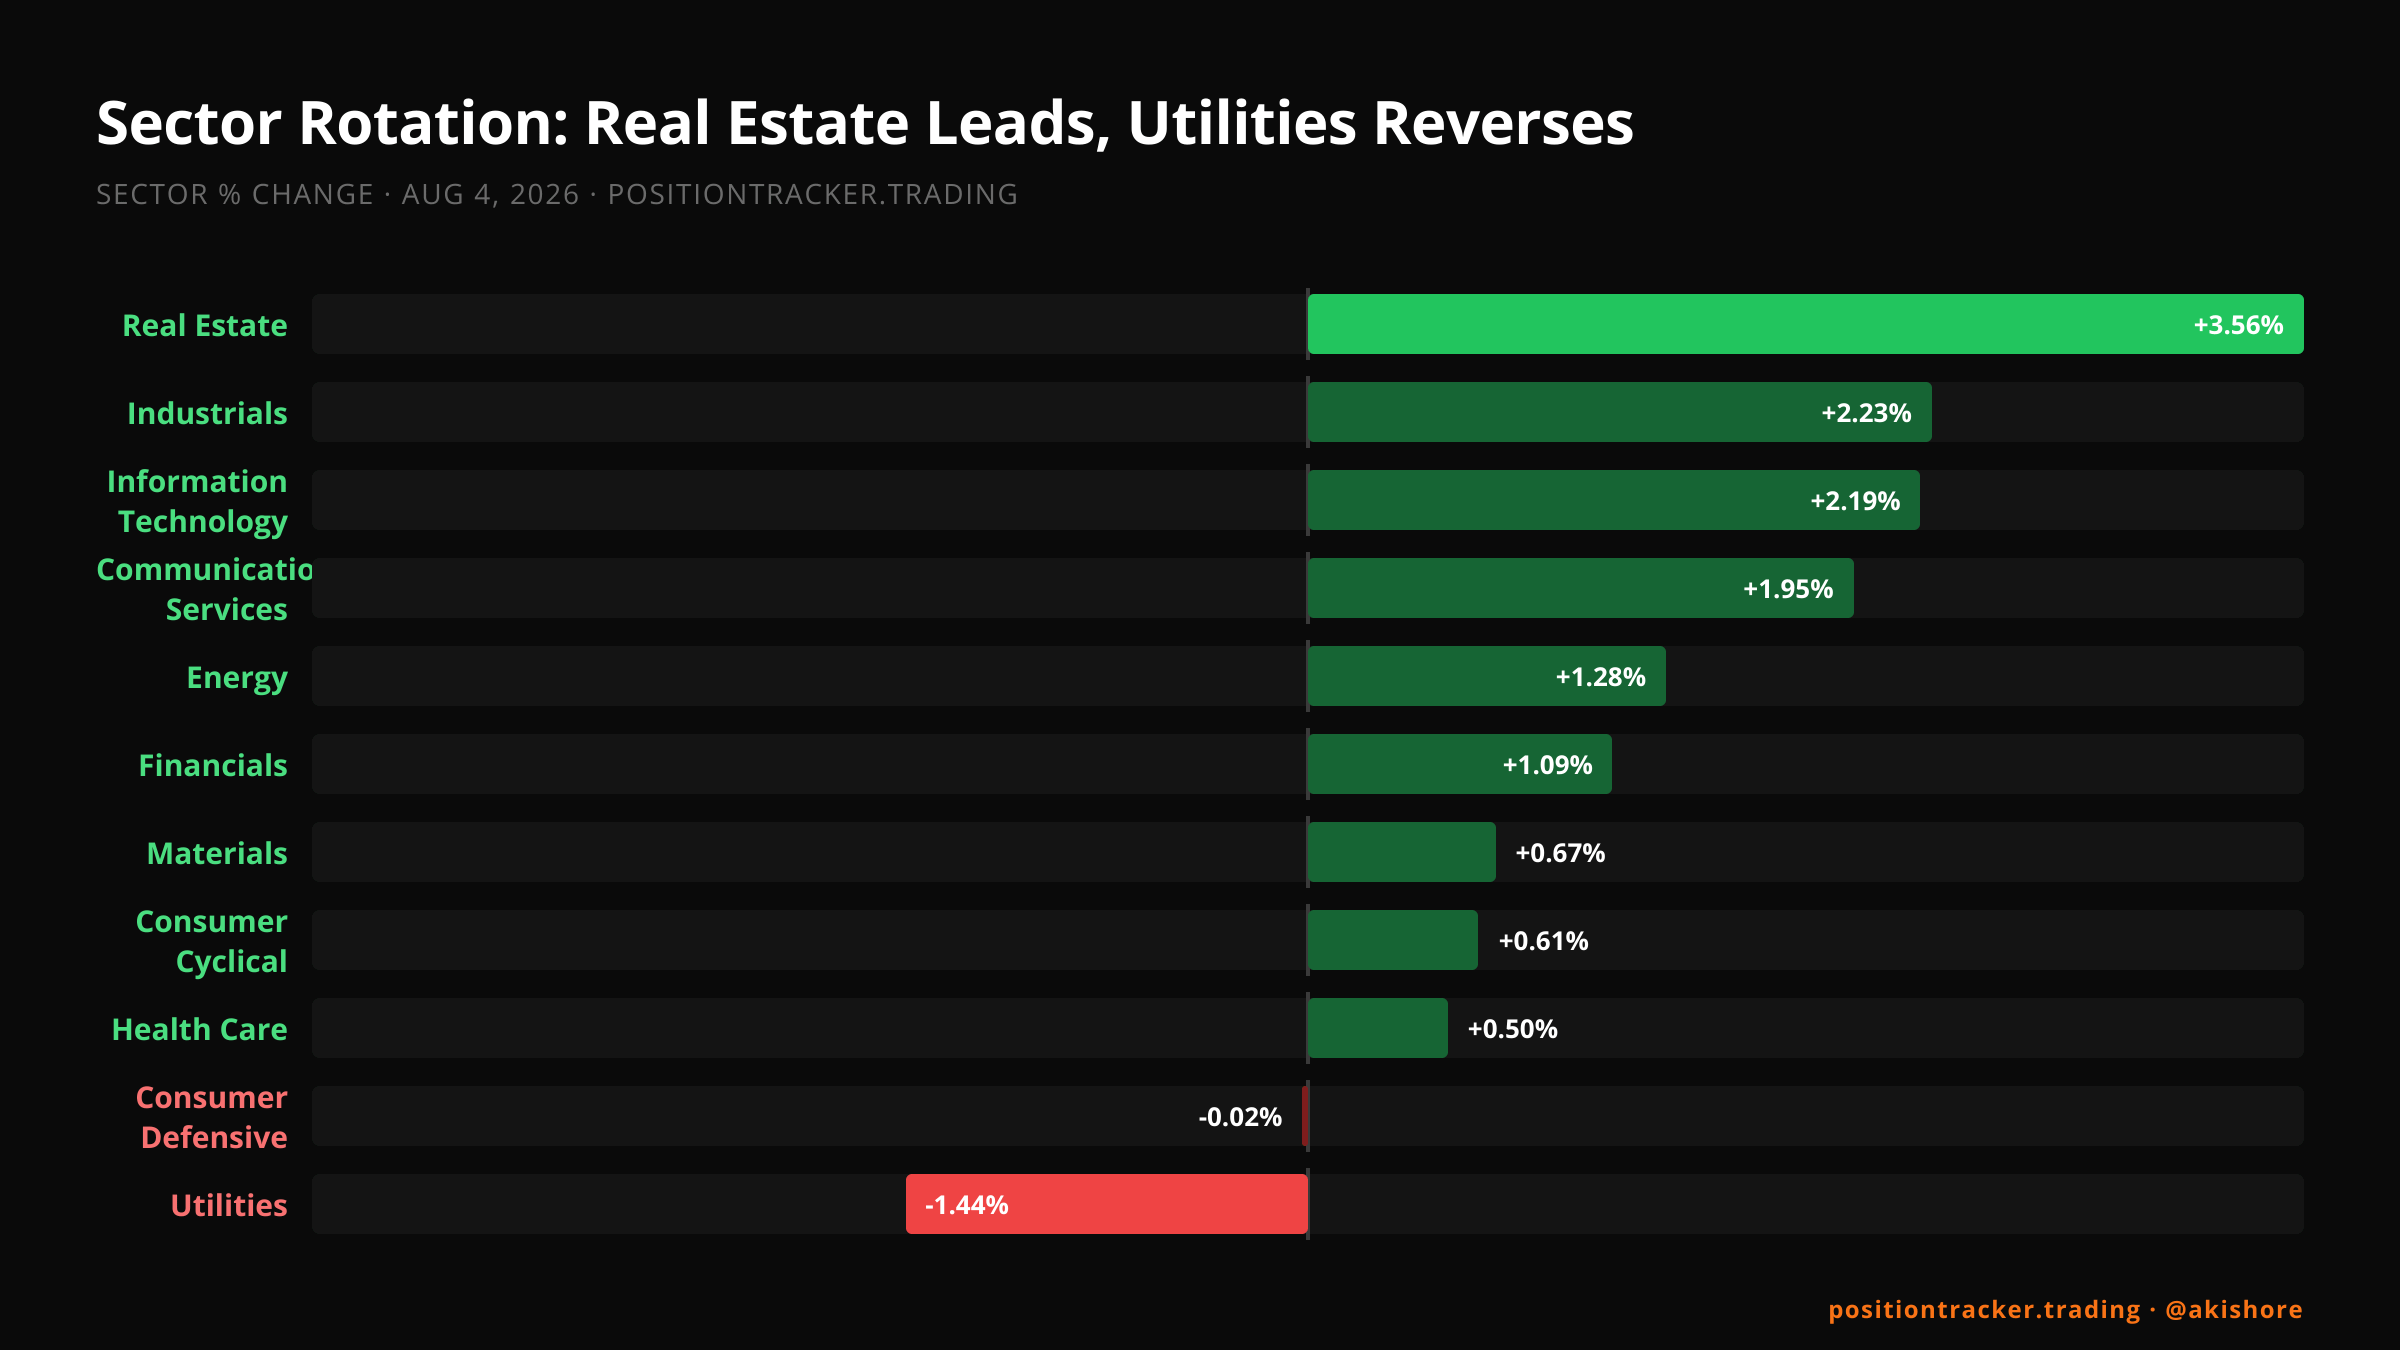
Energy returned +2.60% in Friday's session, the largest gain among all tracked sectors and more than five times the next-best, Information Technology at +0.49%. Only three of eleven sectors finished positive, with Real Estate barely in the green at +0.12%. The narrowness…