News hot-take
CoreWeave reported Q2 revenue of $2.58B, up 112% year over year and beating the $2.56B estimate. Adjusted operating margin hit 5% versus a 2.7% consensus, sending shares up more than 18.5% in premarket trading.
Super Micro also posted strong results with adjusted EPS guidance of $1.01-$1.10 against an expected 76 cents. Revenue guidance came in at $14.5B-$15.5B compared to the $11.68B estimate, lifting shares more than 7.5% premarket.
Reuters framed these moves as evidence that the AI buildout is real and sustained. If gains persist, CoreWeave could add about $8B in market value while Super Micro might add more than $2B.
The infrastructure spending clearly seems real right now, but what if these companies are over-building? This situation feels similar to telecoms that over-built fiber networks during their own expansion cycle.
These AI firms currently show high revenue and profit, yet they are also taking on lots of debt to fund growth. That leverage could become a significant problem down the road even if today looks bright.
Fresh numbers from two different companies make it hard to argue that spending is slowing this quarter. I prefer updating my view based on this concrete data rather than abstract arguments about where the cycle should be. $CRWV
Not financial advice. For informational and educational purposes only.
$DECK daily pick: sell Dec 18 $75 put (buy-side)
$DECK: I'm selling the Dec 18 $75 put and getting paid to wait on the @hoka and @UGG owner. As of Friday's close ($81.09, markets are closed today): 19% below the 200-day and 34% off the February high Credit $1.90 for ~2.5% in 54 days (~17% annualized) Breakeven $73.10, about 10% below Friday About 10.5x this fiscal year's EPS estimate…
S&P 500 up after all 19 midterms since 1950; at a 70% base rate that streak is roughly 1 in 880
With US midterms on November 3, traders are sharing the stat that the S&P 500 rose in the 12 months after all 19…
S&P Global US Manufacturing PMI hits 56.0 in October, beating the 55.5 consensus by half a point
US manufacturing PMI hit 56.0 in October, the highest since May 2022. The Street expected a dip. Factory hiring was…
Energy Leads Alone as Defensives Lag
Energy led all sectors at +2.60%, more than five times the next-best gain in Information Technology (+0.49%), while eight of eleven sectors finished negative.
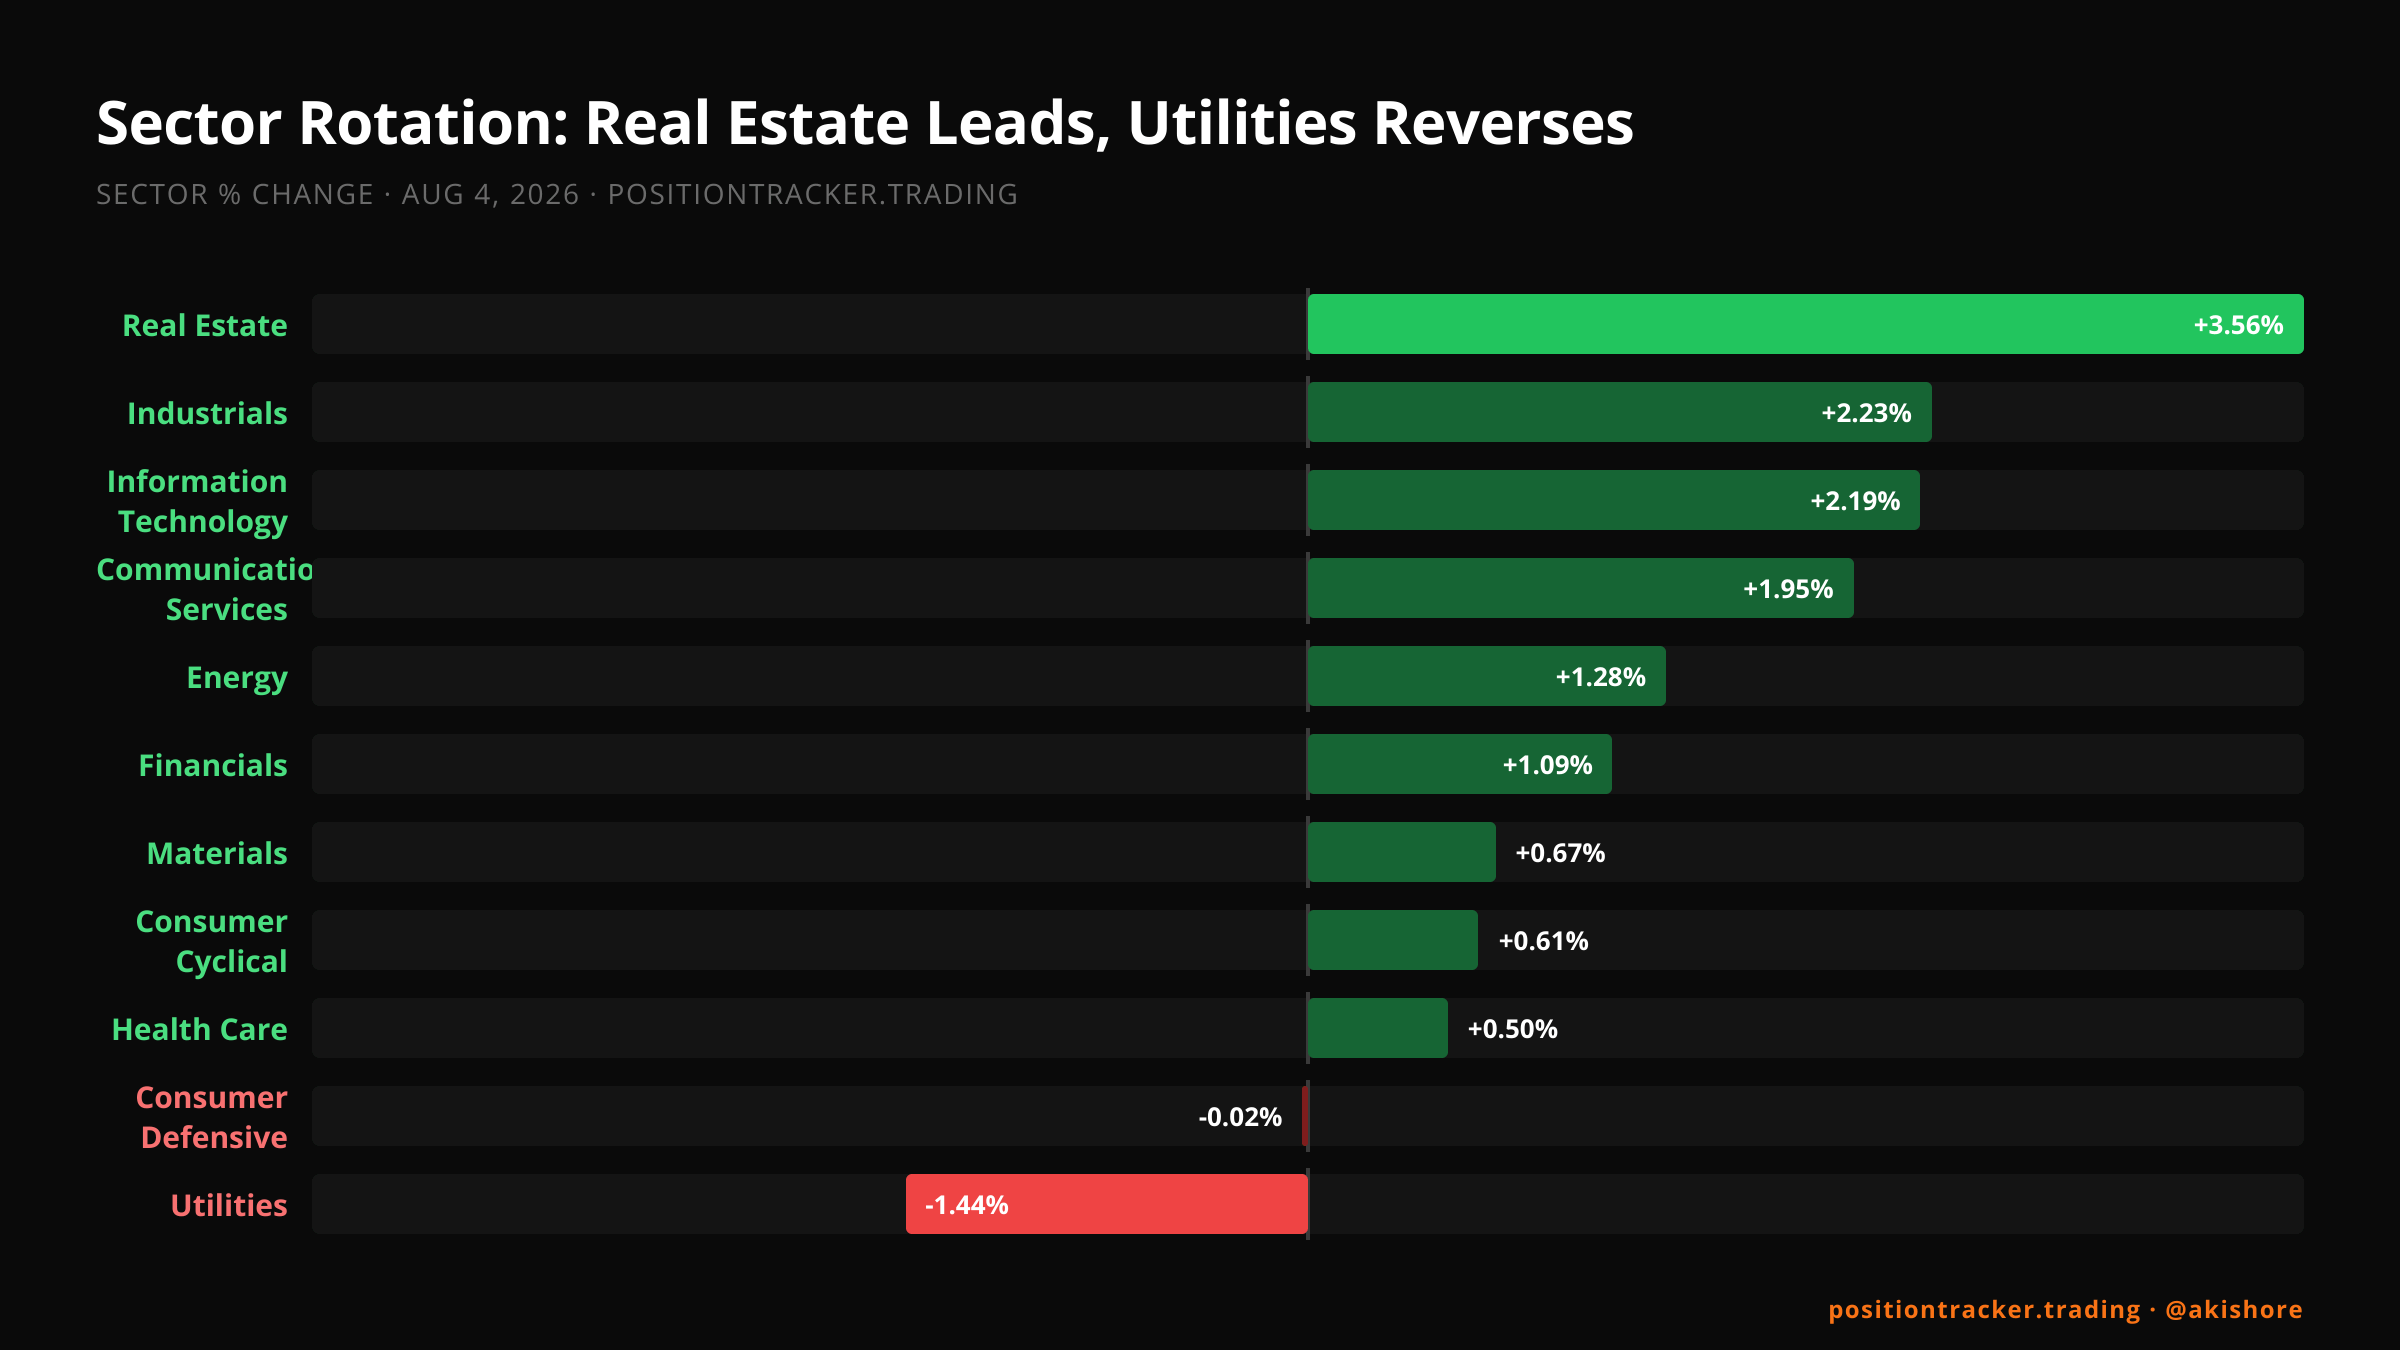
Energy returned +2.60% in Friday's session, the largest gain among all tracked sectors and more than five times the next-best, Information Technology at +0.49%. Only three of eleven sectors finished positive, with Real Estate barely in the green at +0.12%. The narrowness…