Semiconductors lost $1.3 trillion in market value last week.
Semiconductors lost $1.3 trillion in market value last week. The Philadelphia Semiconductor Index dropped 10.8% over 10 sessions, with SOXX down 8% in five days. $INTC fell 21%, $MU 22%, $AMD 8%. Samsung also declined. This is the sharpest sector-wide drop in years.
What stands out is the magnitude and breadth. The decline was driven by nearly everything falling together, suggesting a shift in market psychology and a broader reassessment of the sector's near-term outlook.
Part of the pressure traces to macro: rising bond yields, sticky inflation, and uncertainty around AI's near-term revenue impact. But the underlying story still hinges on demand. The market is asking whether the AI-driven capex cycle can sustain pricing, volume, and margins across memory, compute, and foundry segments.
$MU reports earnings this week. Its guidance will be critical. Memory pricing, inventory levels, and exposure to AI and PC's will all feed into whether this dip is a buying opportunity or the start of a longer correction.
Right now, investors are pricing in lower earnings and applying a lower multiple to future growth assumptions. That kind of de-rating takes time to reverse.
The sector may be overbought relative to near-term fundamentals. Until there's clarity on demand inflection, volatility stays high.
Watch $MU. Then watch capex plans from the cloud providers. That's where the next leg of the story unfolds.
Not financial advice. For informational and educational purposes only.
$DECK daily pick: sell Dec 18 $75 put (buy-side)
$DECK: I'm selling the Dec 18 $75 put and getting paid to wait on the @hoka and @UGG owner. As of Friday's close ($81.09, markets are closed today): 19% below the 200-day and 34% off the February high Credit $1.90 for ~2.5% in 54 days (~17% annualized) Breakeven $73.10, about 10% below Friday About 10.5x this fiscal year's EPS estimate…
S&P 500 up after all 19 midterms since 1950; at a 70% base rate that streak is roughly 1 in 880
With US midterms on November 3, traders are sharing the stat that the S&P 500 rose in the 12 months after all 19…
S&P Global US Manufacturing PMI hits 56.0 in October, beating the 55.5 consensus by half a point
US manufacturing PMI hit 56.0 in October, the highest since May 2022. The Street expected a dip. Factory hiring was…
Energy Leads Alone as Defensives Lag
Energy led all sectors at +2.60%, more than five times the next-best gain in Information Technology (+0.49%), while eight of eleven sectors finished negative.
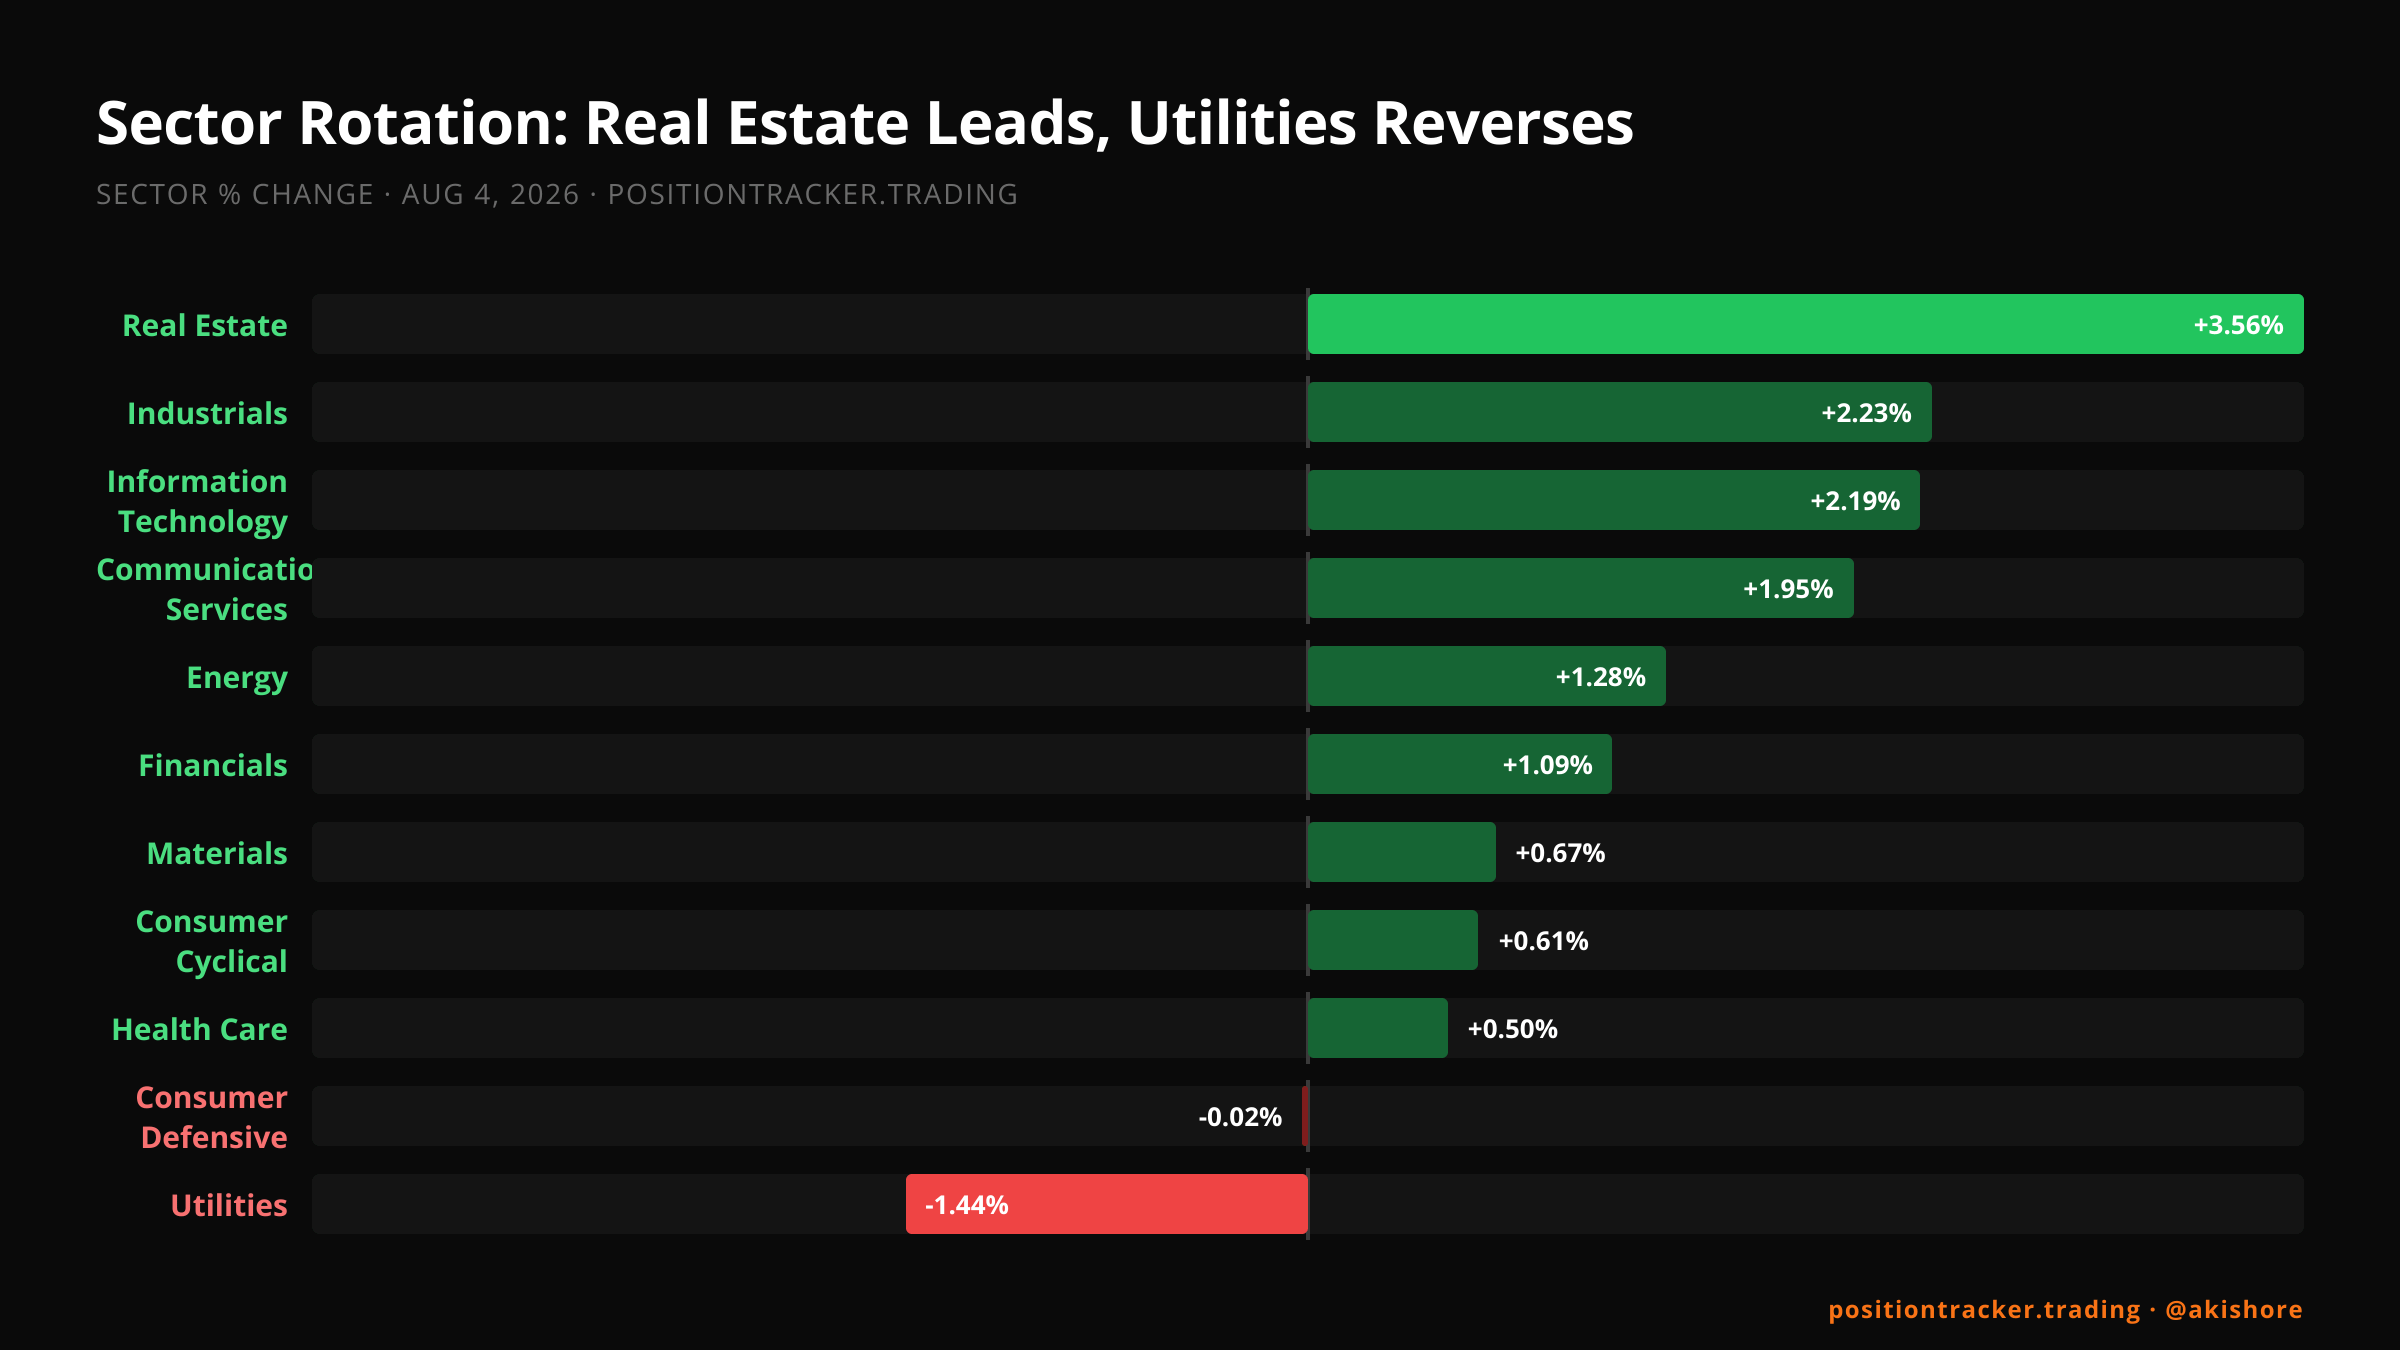
Energy returned +2.60% in Friday's session, the largest gain among all tracked sectors and more than five times the next-best, Information Technology at +0.49%. Only three of eleven sectors finished positive, with Real Estate barely in the green at +0.12%. The narrowness…