The people this quarter hits hardest are the ones buying fewer McDonald's meals, and the profit beat covers it up.
The people this quarter hits hardest are the ones buying fewer McDonald's meals, and the profit beat covers it up. $MCD's US guest counts went negative, and higher checks from the customers who still show up are carrying the topline.
- Adjusted EPS came in at $3.57 versus a $3.38 estimate. GAAP EPS was $3.51 after $0.06 a share of restructuring charges, so I'd quote the smaller number too.
- Revenue missed at $7.157B against estimates around $7.29B. US comparable sales fell 0.2%, with negative guest counts largely offset by check growth. Global comps rose 1.5%.
- Back in Q1, management said "the low-income consumer is absolutely still declining" while high-income spending held up. This release doesn't name the cause, but fewer visits and bigger bills fit that pattern.
- Shares were at $268.69 pre-market on Nov. 4, up 2.15% from the $263.04 close. CEO Chris Kempczinski said US performance improved as the quarter went on after the value interventions.
My read: the business is solid, and the market is paying for the EPS beat and global comps. The traffic number is what I'd watch. If value pricing brings visits back next quarter, this was a blip. If it doesn't, check growth can only cover for so long, though I could be wrong on how fast that shows up.
Sources:
Invezz: https://invezz.com/news/2026/11/04/mcdonalds-earnings-hide-a-key-story-about-consumer-spending/
Trefis: https://www.trefis.com/stock/mcd/articles2/615678/why-has-mcdonalds-gone-quiet-on-its-low-income-customer/2026-09-17
Not financial advice. For informational and educational purposes only.
Video explainer: AMD just guided to about $17 billion in revenue for Q4. Intel guided to $15 billion to $16 billion last week. If both land where they said, AMD outsells Intel for the first time ever.
AMD just guided to about $17 billion in revenue for Q4. Intel guided to $15 billion to $16 billion last week. If both land where they said, AMD outsells Intel for the first time ever. The…
Investors priced in AI-rule risk on Nov.
Investors priced in AI-rule risk on Nov. 4 that Congress probably can't turn into law anytime soon. I'd treat the Tesla and SpaceX premarket drop as a fear trade until I see an actual bill moving. As of 13:30 UTC, $TSLA was at $380.90 pre-market,…
Volcker Shock & the 1980s Bull — 20% Rates to 3.75%-4.00%
In June 1981, the Federal Reserve pushed the Fed Funds rate to 20% to break inflation running at 14.8%, the most aggressive tightening cycle in Fed…
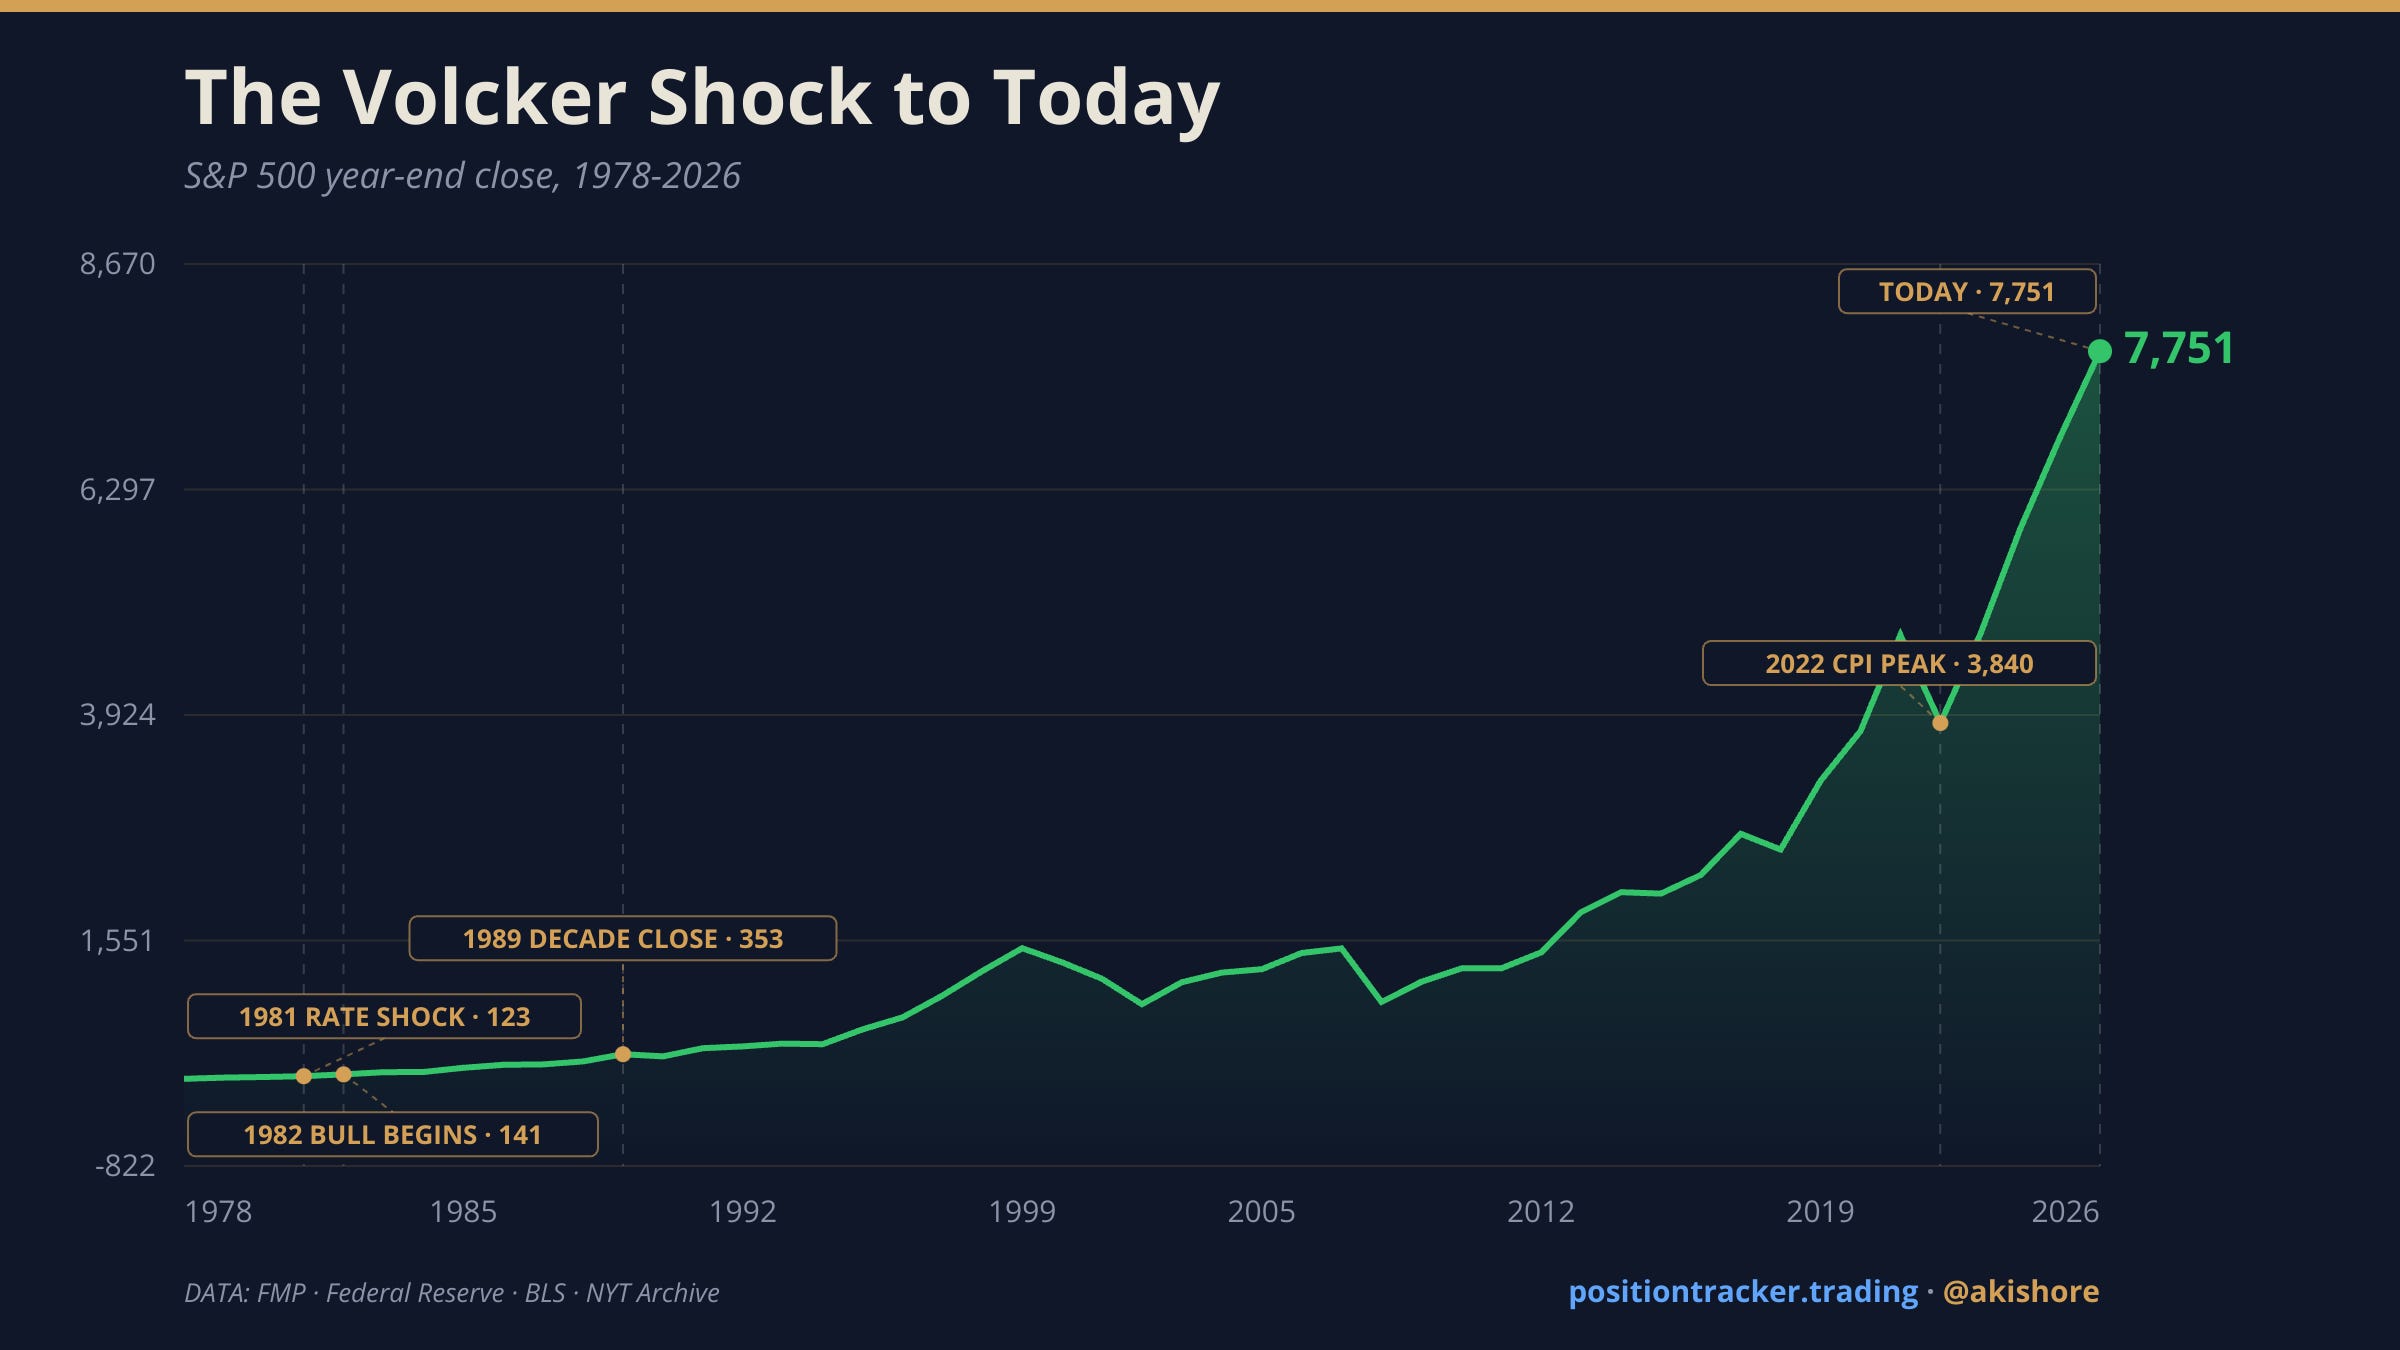
In June 1981, the Federal Reserve pushed the Fed Funds rate to 20% to break inflation running at 14.8%, the most aggressive tightening cycle in Fed history. The market absorbed the full cost of it. The S&P 500 bottomed at 102.42 on August…
Afternoon update
$LITE fell 16.57% and Marvell 10.68% this afternoon as investor skepticism grew over Marvell's $115B all-stock acquisition of Lumentum. • Lumentum…
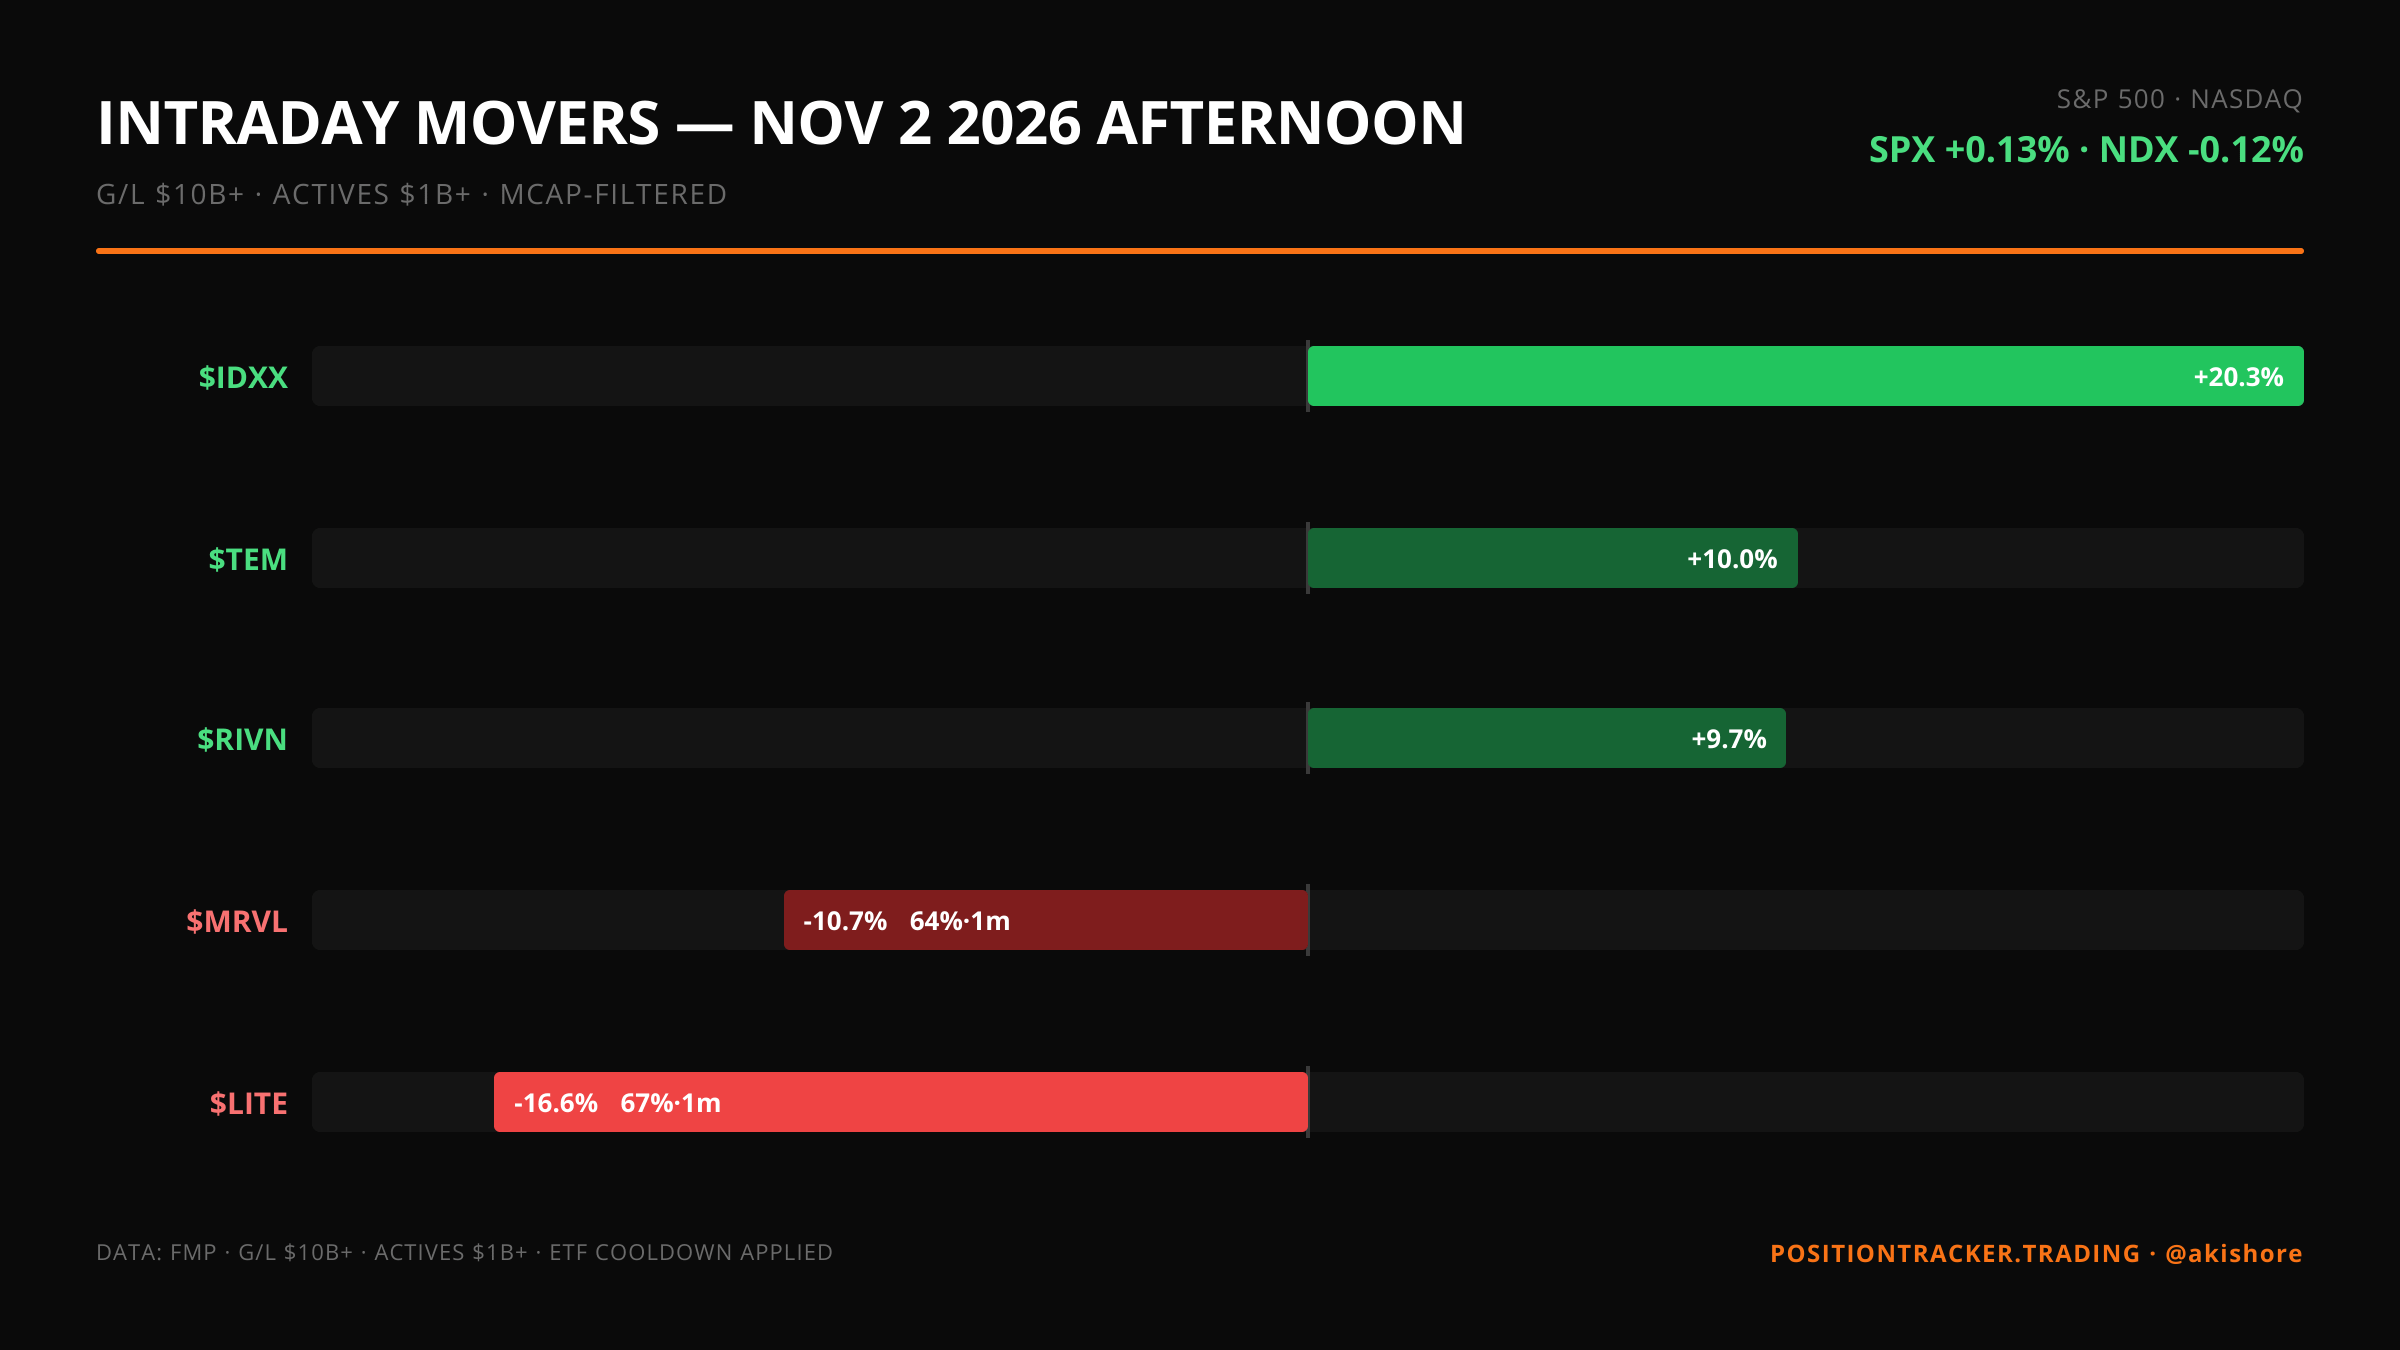
$LITE fell 16.57% and Marvell 10.68% this afternoon as investor skepticism grew over Marvell's $115B all-stock acquisition of Lumentum. Lumentum closed at $701.43 ($62.9B market cap). The deal, valued at $115B by enterprise value, gives Marvell shareholders 67% of the combined…