TSMC just posted a strong earnings beat for Q2 2026.
TSMC just posted a strong earnings beat for Q2 2026. Revenue hit NT$1.27 trillion. EPS came in at NT$27.25 against an estimate of NT$24.29. Yet the stock is down about 2% in premarket trading.
The market is focused on one thing. TSMC raised its 2026 capital expenditure guidance to $60-64 billion. This is the largest budget in company history. It sits about 15% above prior expectations. Investors worry this spending surge will hurt long-term returns. Management warned that overseas fab expansion will dilute gross margins by 2-3% at first. That gap could widen to 3-4% later.
TSMC guided Q3 revenue to $44.6-45.8 billion. That represents 37% year-over-year growth. Still, the sheer scale of upcoming costs is shaking confidence across the semiconductor supply chain. The fallout was fast and severe. South Korea's Kospi fell over 6%. SK Hynix dropped double digits in Seoul trading on the same day.
It is fascinating to watch this unfold. TSMC executed perfectly on operations. But the stock got punished anyway. The price of maintaining tech leadership keeps rising.
This reaction suggests a shift. The bar for rewarding capex-heavy growth stories has moved. This is true even when underlying demand signals remain incredibly strong.
Not financial advice. For informational and educational purposes only.
$DECK daily pick: sell Dec 18 $75 put (buy-side)
$DECK: I'm selling the Dec 18 $75 put and getting paid to wait on the @hoka and @UGG owner. As of Friday's close ($81.09, markets are closed today): 19% below the 200-day and 34% off the February high Credit $1.90 for ~2.5% in 54 days (~17% annualized) Breakeven $73.10, about 10% below Friday About 10.5x this fiscal year's EPS estimate…
S&P 500 up after all 19 midterms since 1950; at a 70% base rate that streak is roughly 1 in 880
With US midterms on November 3, traders are sharing the stat that the S&P 500 rose in the 12 months after all 19…
S&P Global US Manufacturing PMI hits 56.0 in October, beating the 55.5 consensus by half a point
US manufacturing PMI hit 56.0 in October, the highest since May 2022. The Street expected a dip. Factory hiring was…
Energy Leads Alone as Defensives Lag
Energy led all sectors at +2.60%, more than five times the next-best gain in Information Technology (+0.49%), while eight of eleven sectors finished negative.
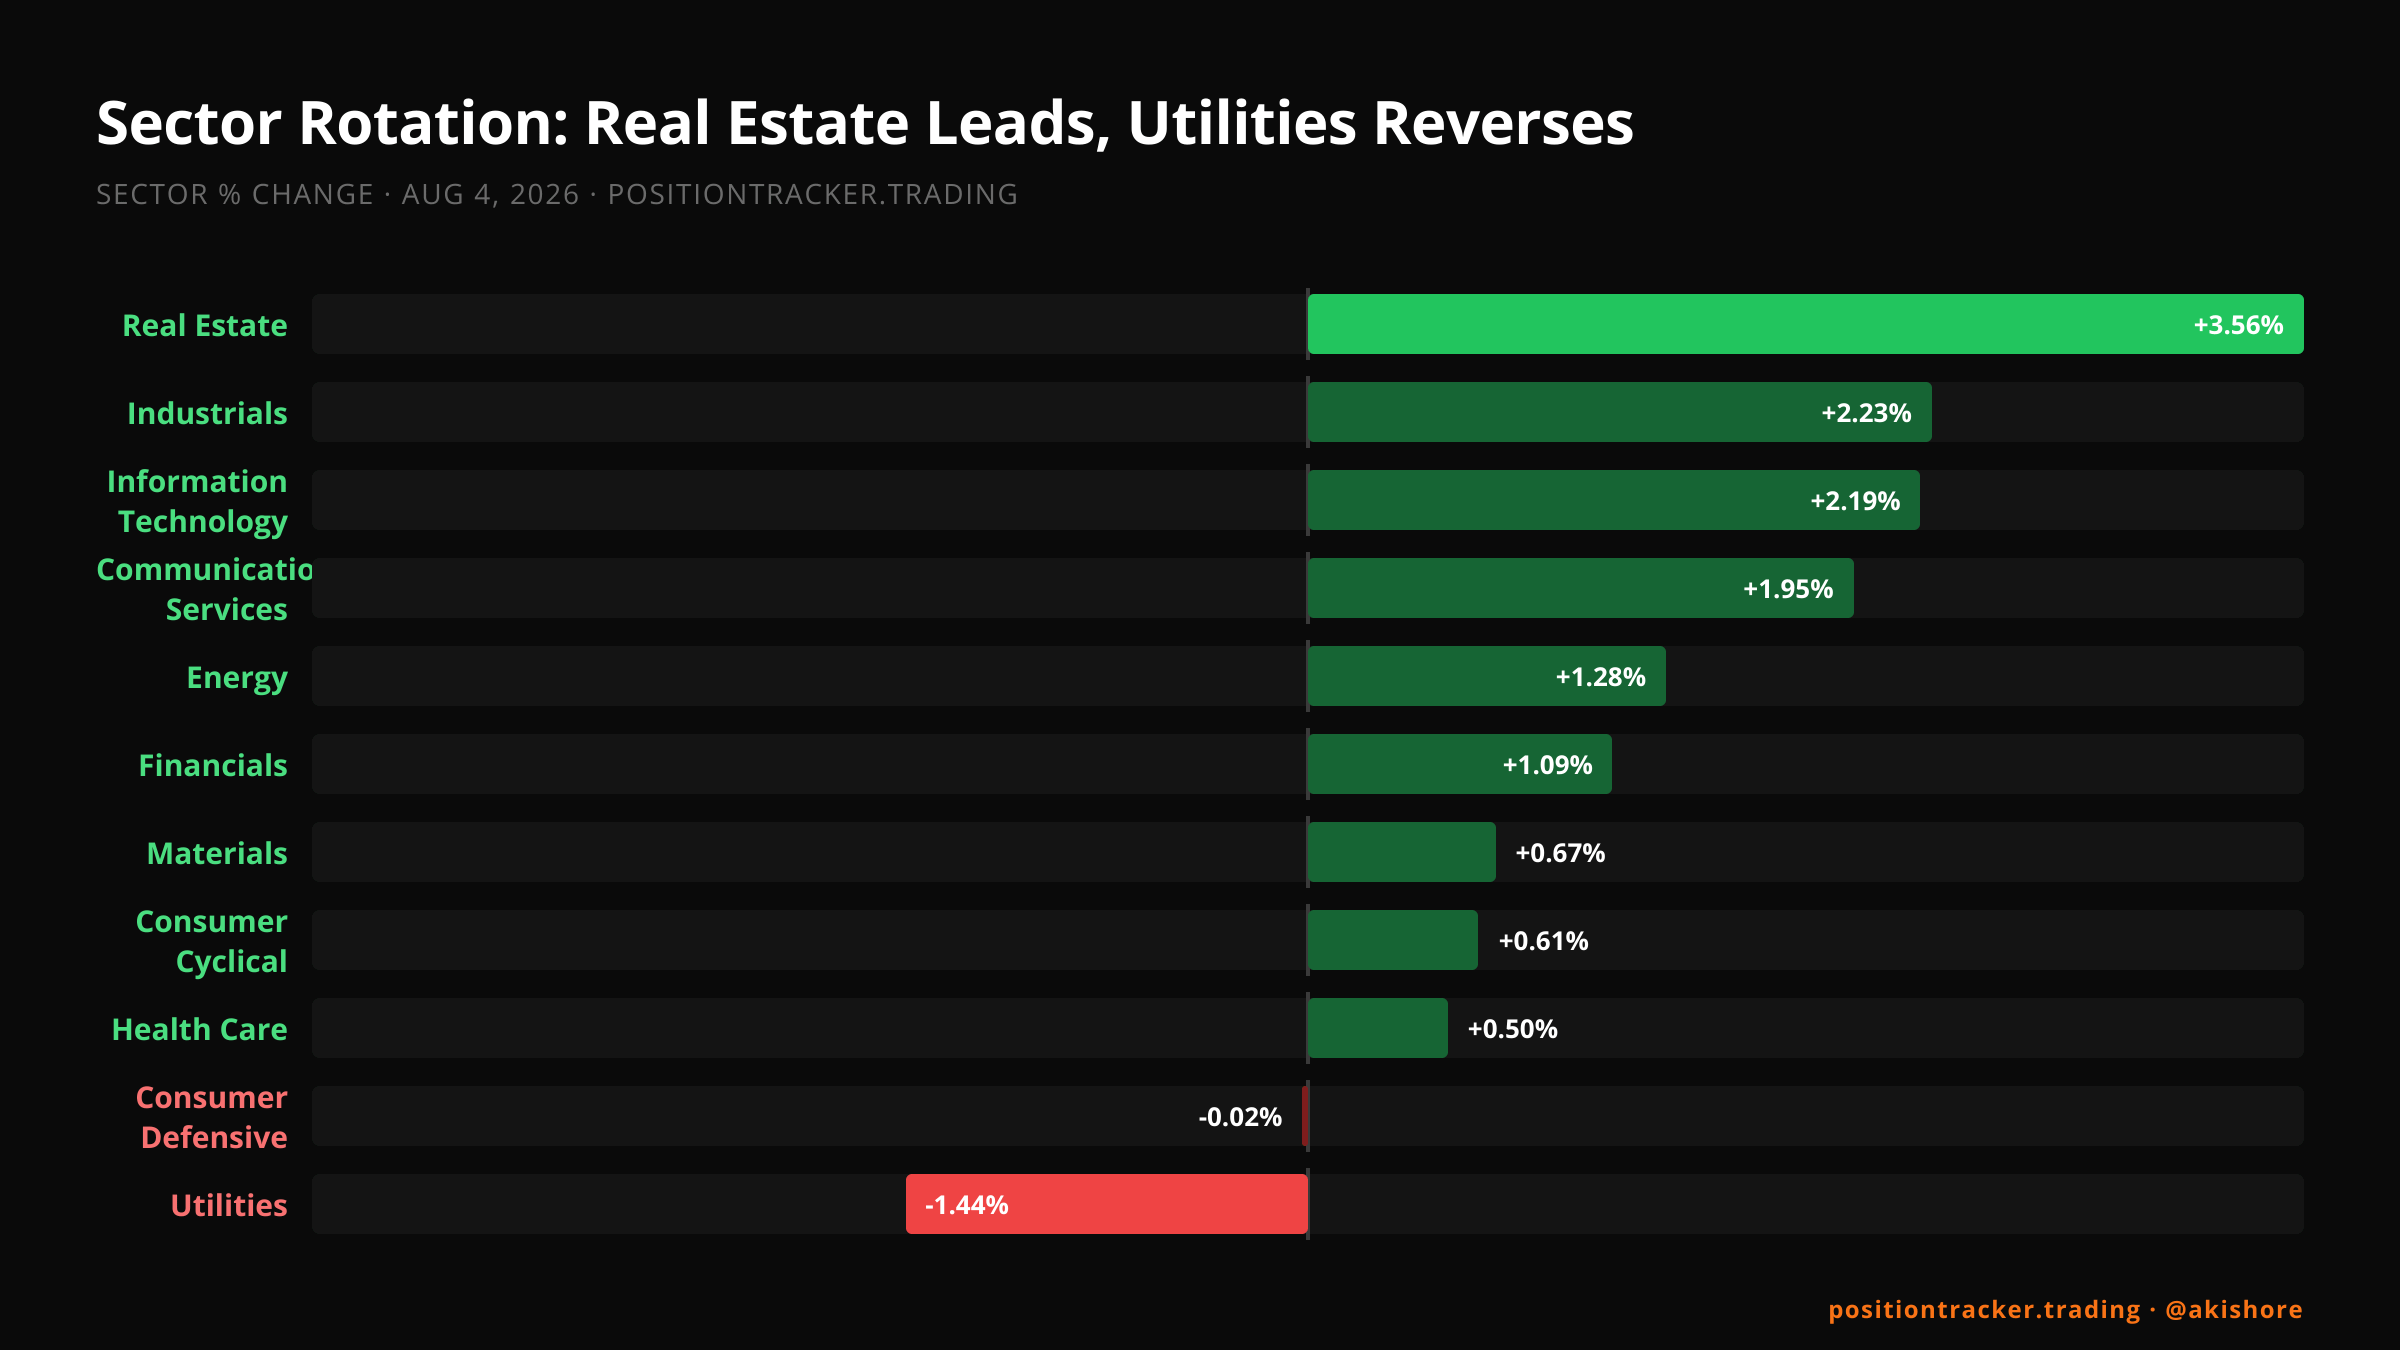
Energy returned +2.60% in Friday's session, the largest gain among all tracked sectors and more than five times the next-best, Information Technology at +0.49%. Only three of eleven sectors finished positive, with Real Estate barely in the green at +0.12%. The narrowness…